
How Long Can You Stay on Your Parents' Insurance?
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Most young adults are removed from their parents’ health insurance when they turn 26, requiring them to get coverage from an employer, the Health Insurance Marketplace or another alternative. Depending on where you live and whether you meet specific eligibility requirements, such as having a qualifying disability or being an active student, state laws may allow you to extend coverage under your parents’ plan for a few more years or indefinitely.
Read on to learn how long you can stay on your parents’ insurance and what your health insurance options are when you’re removed from the plan in order to retain essential coverage.
|
Key Takeaways
|
On This Page

Are There Exceptions When Staying on Your Parents' Health Plan?
Why Am I Cut Off From My Parents' Health Insurance at 26 Years Old?
Can I Have My Own Health Insurance Policy While Still on My Parents' Plan?
What To Do if You're Cut Off From Your Parents' Health Insurance at 26
How To Choose the Right Health Insurance When You're Dropped
FAQs

Are There Exceptions When Staying on Your Parents' Health Plan?
Most Americans listed as dependents on their parents’ insurance plan will need to find their own health coverage when turning 26, but there are a few exceptions. For example, if your parents’ coverage is through an employer with 20 or more employees, you may be eligible to enroll in COBRA coverage for up to 36 months after turning 26. However, you must enroll in this coverage within 60 days of your 26th birthday.[1]
In addition, certain states allow extended dependent coverage beyond age 26 — for one or more years, or indefinitely — if you have a qualifying disability or otherwise meet specific eligibility requirements. These states and their requirements for extended coverage under a parent’s health insurance include:
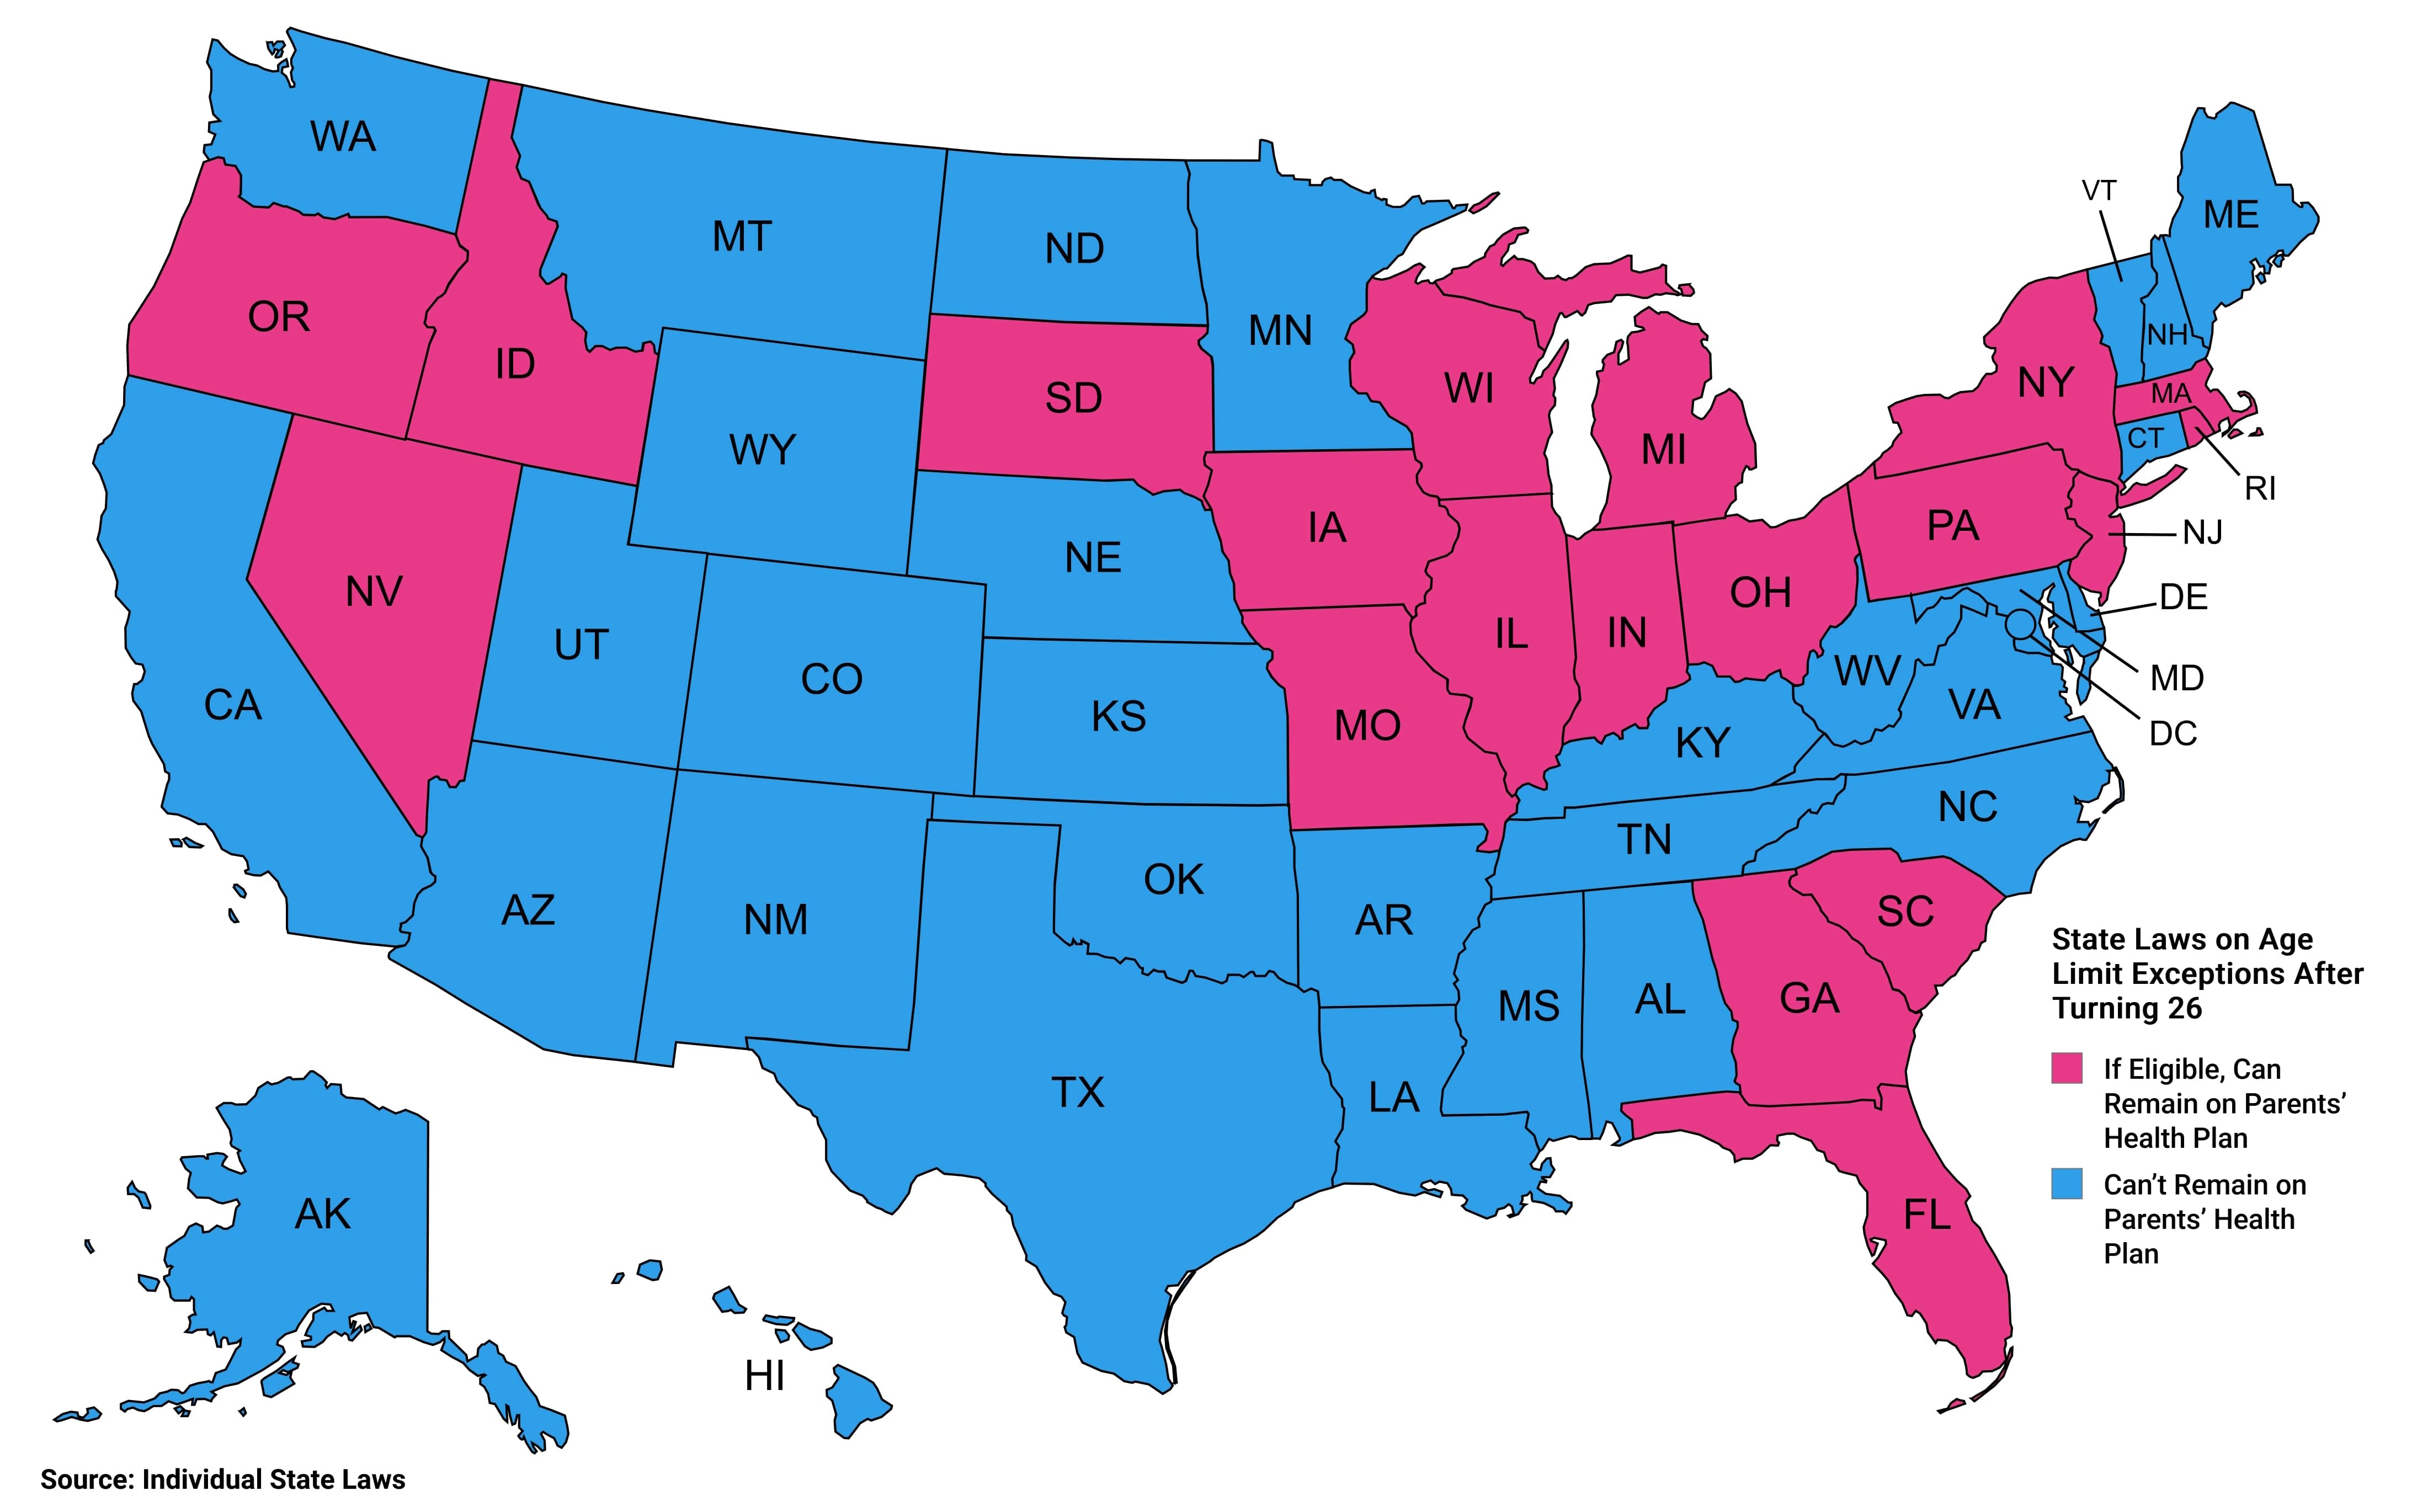
| State |
Age Limit Exceptions for Parents’ Coverage After Turning 26 |
|---|---|
|
Florida[2] |
Coverage lasts until the end of the year you turn 30, provided you are a Florida resident or a part-time or full-time student. Must remain unmarried, without dependents and have no other health insurance plan. |
|
Georgia[3] |
Coverage doesn’t end for disabled dependents, regardless of age. |
|
Idaho[4] |
Coverage doesn’t end for disabled dependents, regardless of age. |
|
Illinois[5] |
Coverage lasts until you turn 30, provided you are an unmarried Illinois resident and a veteran who did not receive a dishonorable discharge. |
|
Indiana[6] |
Coverage doesn’t end for disabled dependents who are unable to maintain self-sustaining employment, regardless of age. |
|
Iowa[7] |
Coverage doesn’t end for disabled dependents and full-time students, regardless of age. |
|
Massachusetts[8] |
Coverage doesn’t end for disabled dependents who are unable to maintain self-sustaining employment, regardless of age. |
|
Minnesota[9] |
Coverage doesn’t end for disabled dependents, regardless of age. |
|
Missouri[10] |
Coverage doesn’t end for disabled dependents who are unable to maintain self-sustaining employment, regardless of age. |
|
Nevada[11] |
Coverage doesn’t end for disabled dependents who are unable to maintain self-sustaining employment, regardless of age. |
|
New Jersey[12] |
Coverage lasts until you turn 31, provided you are unmarried with no dependents of your own. |
|
New York[13] |
Coverage lasts until you turn 30, provided you are unmarried, ineligible for employer-based insurance and live or work in the state or insurance’s service area. |
|
Ohio[14] |
Coverage doesn’t end for disabled dependents who are unable to maintain self-sustaining employment, regardless of age. |
|
Oregon[15] |
Coverage doesn’t end for disabled dependents, regardless of age, provided a medical provider confirmed the disability before you turn 26. |
|
Pennsylvania[16] |
Coverage lasts until you turn 30, provided you are unmarried, have no dependents of your own, are not covered by any other insurance plan and are a Pennsylvania resident or enrolled as a full-time student in higher education. |
|
Rhode Island[17] |
Coverage doesn’t end for disabled dependents who are unable to maintain self-sustaining employment and are unmarried, regardless of age. |
|
South Carolina[18] |
Coverage doesn’t end for disabled dependents who are unable to maintain self-sustaining employment, regardless of age. |
|
South Dakota[19] |
Coverage lasts until you turn 30, provided you are a full-time student, while parents’ coverage doesn’t end at any age for disabled dependents. |
|
Wisconsin[20] |
Coverage doesn’t end for full-time students, regardless of age, or for those called to active duty in the National Guard or U.S. Armed Forces while a full-time student before the age of 27. |
Why Am I Cut Off From My Parents' Health Insurance at 26 Years Old?
The Affordable Care Act (ACA), also known as Obamacare, only requires insurers to permit children to remain on their parents’ plans until they turn 26.[1] Because there are generally no federal requirements to extend this coverage — aside from specific state laws — most health insurance providers end dependent coverage at that point and require young adults to obtain their own policies, which include separate premiums, deductibles and copayments.
Losing coverage at 26 years old reflects a significant improvement in health insurance legislation compared to the period before the ACA was enacted in 2010. Prior to the ACA, many young adults lost coverage as early as age 19 — with only full-time college students occasionally retaining coverage until age 23 — unless state laws provided an extension.[21]
Can I Have My Own Health Insurance Policy While Still on My Parents' Plan?
You can usually purchase your own health insurance policy while remaining on your parents’ plan, a situation referred to as dual coverage. In this case, one policy serves as your primary insurance, while the other acts as secondary insurance, helping cover out-of-pocket costs not fully covered by the primary plan.[22]
The primary and secondary policies are determined by the insurance providers when a medical claim is filed.[22] Some insurers may place limitations on coverage if you have more than one policy, so review your plans carefully to avoid issues.[23]
What To Do if You're Cut Off From Your Parents' Health Insurance at 26
Below are a few options to consider when getting your own health insurance after turning 26 and losing coverage from your parents’ health insurance:
- Employer-based coverage: If you qualify for a special enrollment period, you can sign up for an employer-sponsored health insurance plan as a full-time employee. Some employers also extend coverage to part-time workers.
- Health Insurance Marketplace: The federal marketplace or your state exchange allows you to apply for a health plan. Depending on your income, you may qualify for a premium tax credit to help lower your monthly costs.
- Medicaid: You might be eligible for Medicaid based on your state’s income limits and other criteria.
- Joining a partner’s plan: If you’re married or in a domestic partnership, you may be eligible to enroll in your partner’s health insurance plan.
- Student health insurance: Many colleges and universities offer student health plans that provide affordable coverage for eligible students.
How To Choose the Right Health Insurance When You're Dropped
To get your own coverage that meets your needs, you’ll want to shop around for various insurance options. Get quotes from at least three to five different insurance providers in order to compare costs and benefits. You’ll typically need to provide information to each insurance company to determine your rates, which can include your location, age, marital status, health status, income and more.
You can speed up this process by using an insurance marketplace like SmartFinancial. After answering a brief questionnaire, we can connect you with a licensed insurance agent to help you get the coverage you need. Click here for free health insurance quotes today!
- Insurance quotes /
- Health /
- How Long Can You Stay On Your Parents Health Insurance
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Health Insurance Quote Online Now.
More on Health Insurance
Looking for Health Insurance?
Compare rates from dozens of companies in less than 3 minutes.