

How To Shop for an ACA Health Plan in 2025
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
You can shop for health insurance on the federal Health Insurance Marketplace or your state’s equivalent health exchange by sharing personal details about your household, comparing Affordable Care Act (ACA) health insurance plans based on their costs and benefits and signing in to fill out and submit an application online. As you shop for ACA Marketplace coverage, remember that you may qualify for government subsidies, depending on your income.
Keep reading for a detailed overview of the steps you need to take to shop for ACA health insurance and what information you should have at the ready before you begin.
|
Key Takeaways
|


What Is the ACA Marketplace?
The Marketplace refers to a government-run health exchange that insurance shoppers can use to enroll in health plans that comply with the regulations established by the ACA. Most states take advantage of the federal Marketplace at HealthCare.gov, but the District of Columbia and the following 20 states instead operate their own Marketplace websites:[1]
ACA-compliant health plans come with certain mandatory benefits. For example, health insurance companies that operate on the Marketplace must cover in-network preventive services with no copays or coinsurance — regardless of whether you’ve hit your deductible — and they cannot refuse to cover you on account of a preexisting condition.[2] In addition, all Marketplace plans are required to cover the following health care services:[3]
|
Ambulatory patient services |
Emergency services |
| Hospitalization | Pregnancy, maternity and newborn care |
| Mental health and substance use disorder services | Prescription drugs |
| Rehabilitative and habilitative services and devices | Laboratory services |
| Preventive and wellness services and chronic disease management | Pediatric services |
| Birth control | Services related to breastfeeding |
How Much Is Health Insurance Through the ACA Marketplace?
On average, benchmark health plans purchased through the Marketplace cost $625 per month.[4] While health insurance rates are customized based on your personal circumstances, insurers are only allowed to consider these five factors when determining how much you have to pay for a Marketplace plan:[5]
- Age: A Marketplace health insurance plan can be as much as three times more expensive for an older policyholder than for a younger one.
- Location: Where you live can affect your health insurance prices in numerous ways, as rates are influenced by factors like statewide rules, differences in competition and the cost of living in your area.
- Tobacco use: Your monthly payment for health insurance may be up to 50% higher if you are a smoker or use other tobacco products.
- Whether you choose individual or family coverage: Naturally, it’s cheaper to enroll in a plan that only covers yourself than to enroll in one that also covers your spouse and dependents.
- Plan categories: Marketplace plans are grouped into different tiers — also known as categories or metal levels — which indicate how health care costs are split between you and your insurance company. Lower-tiered bronze and silver plans have lower monthly premiums and higher out-of-pocket costs when you receive care, while higher-tiered gold and platinum plans have higher premiums and lower out-of-pocket costs.

What Do You Need To Shop for ACA Marketplace Plans?
To start comparing health insurance plans through HealthCare.gov, you will need to provide information like your ZIP code, household income and marriage status, along with the number of people living in your household and all of their ages and sexes.[6] Keep in mind that the information you need to share may differ if you use a state-run health exchange.
How To Shop for Health Insurance Through the ACA Marketplace
Read the following sections for a rundown of the steps you need to take as you look for the right major medical insurance plan on the Health Insurance Marketplace.
1. Determine if You’re Eligible
Most citizens, nationals and lawfully present noncitizens in the United States are eligible to use the Marketplace, but there are a few restrictions to note. Specifically, you cannot enroll in a health plan through the Marketplace if you are unlawfully present or have been convicted of a crime and are actively serving a prison sentence.[7]
Even if you are an American citizen, you cannot shop for plans on the Health Insurance Marketplace unless you reside in one of the 50 states or Washington, D.C. As a result, individuals who primarily live in a United States territory — such as Puerto Rico or American Samoa — are not able to use the Marketplace.[7]
2. Calculate Your Budget
Consider how much you are willing to spend on insurance and health care each month, and take this into account as you compare plans. The plan with the lowest monthly premiums may not be the cheapest in the long term, depending on your circumstances. For example, if you have a chronic condition and need regular medical attention, it may be cost-effective to get a plan with higher premiums but lower copay or coinsurance requirements each time you receive care.
3. Understand the Different Types of ACA Health Plans
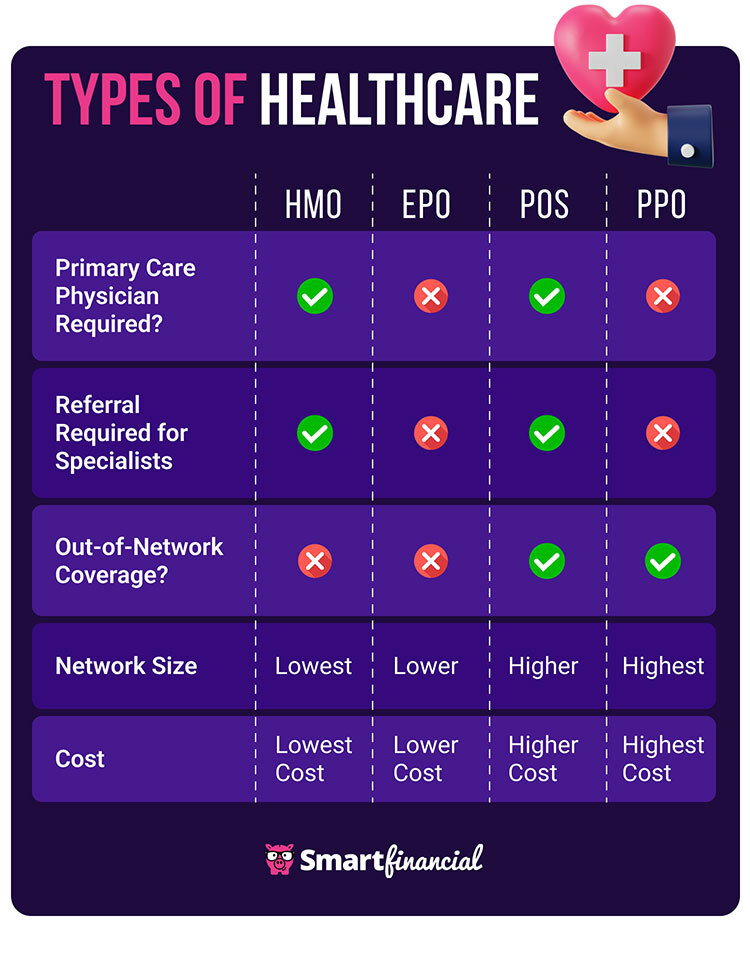
In addition to being categorized by their metal level, most Marketplace health plans are classified as either exclusive provider organization (EPO), health maintenance organization (HMO), point-of-service (POS) or preferred provider organization (PPO) plans. These plan types differ regarding their typical costs and benefits.
POS and PPO plans allow you to visit out-of-network health care providers as long as you cover a greater portion of the costs out of pocket, while EPO and HMO plans don’t cover routine care at all unless the provider is in your plan’s network. Additionally, you generally can’t visit a specialist without a referral from your primary care physician (PCP) if you have an HMO or POS plan, but you may be able to if you have an EPO or PPO plan.[8]
4. Take Advantage of Cost Assistance Programs
Depending on your location, your household income and the number of people in your household, you may qualify for a subsidy known as a premium tax credit that lowers your monthly health insurance bill. When you input your household information to shop on the Marketplace, an estimated tax credit will usually be calculated for you and automatically applied to the premium costs of the plans you compare.[6]
The enhanced premium tax credits established in response to the COVID-19 pandemic are scheduled to expire at the end of 2025 — meaning they won’t apply to 2026 plans you purchase during this year’s open enrollment period. If Congress doesn’t extend them, families with household incomes above 400% of the federal poverty level (FPL) will no longer qualify for tax credits, and those with lower incomes may only be eligible for smaller subsidies.[9]
You may also qualify for income-based cost-sharing reductions, which lower your deductibles, copays and coinsurance instead of your premium. Both premium tax credits and cost-sharing reductions can apply to the same plan, but you cannot claim the cost-sharing reductions unless you are enrolled in a plan in the silver tier.[10] Keep in mind that you can’t take advantage of either Marketplace subsidy if you are also enrolled in or eligible for Medicare.[11]
5. Navigate the ACA Health Insurance Marketplace
HealthCare.gov allows you to apply multiple filters to help you find plans that match your coverage needs. For example, you can organize plans based on their costs, their category or plan type, what insurer offers them and whether they are compatible with health savings accounts (HSAs). You can also search for Marketplace plans that cover specific prescription drugs, disease management programs and doctors or other medical providers.[6]
6. Compare Multiple ACA Health Plans
After inputting your information and applying relevant filters, you can begin to make specific comparisons among various health plans. When you click on a plan on HealthCare.gov, you can see detailed information about the plan, such as its star ratings, copay or coinsurance requirements for various services, estimated yearly costs based on your expected health care usage and plan documents — including lists of covered providers and drugs.[6]
7. Apply for an ACA Health Insurance Plan
Once you’ve settled on a plan, you can create a new account or log in to an existing account on the Marketplace website to begin filling out an application for that plan. You’ll generally need to have the following information and documents on hand as you enroll:[12]
- Your name and date of birth
- Personal information of everyone on the application, including their addresses, Social Security numbers (SSNs), employers and incomes
- Information about the insurance agent or other professional assisting you with your application, if applicable
- Immigration documents, if applicable
- Information about your tax filing status
- Details about your current health coverage
- Insurance quotes /
- Health /
- Shop Affordable Care Act Plan
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Health Insurance Quote Online Now.
More on Health Insurance
Looking for Health Insurance?
Compare rates from dozens of companies in less than 3 minutes.