

When Does Open Enrollment Begin and End?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Health insurance open enrollment lasts from Nov. 1 to Jan. 15 throughout most of the country, though some states have different enrollment periods. During open enrollment, you can shop for health insurance plans that comply with the Affordable Care Act (ACA), or you can change your existing coverage through the federal Health Insurance Marketplace or your state’s equivalent health exchange.
Keep reading to learn more about health insurance open enrollment, including how you can sign up for coverage and what options may be available to you if you miss your state’s enrollment window.
|
Key Takeaways
|
On This Page

What Is Open Enrollment?
How Often Does Open Enrollment Occur?
Who Is Open Enrollment For?
When Is Open Enrollment in 2025?
How Does Open Enrollment Work?
What Happens if I Miss Open Enrollment This Year?
What Types of Health Insurance Are Available During Open Enrollment?
How Do I Maximize the Open Enrollment Period This Year?
How Do I Sign Up for Health Insurance During Open Enrollment?
FAQs

What Is Open Enrollment?
Open enrollment is a period when anyone can freely sign up for an ACA-compliant health insurance plan or adjust their existing coverage. In most states, open enrollment lasts from Nov. 1 to Jan. 15 each year. Coverage takes effect at the beginning of the new year for shoppers who sign up by Dec. 15, while it starts on Feb. 1 for those who sign up from Dec. 16 to Jan. 15.[1]

If you are eligible for a type of health insurance other than Marketplace coverage, you may be able to sign up during a different enrollment window. For example, Medicare open enrollment occurs from Oct. 15 to Dec. 7. Meanwhile, Medicare Advantage open enrollment takes place from Jan. 1 to March 31.[2]
Why Does Open Enrollment Exist?
By limiting when customers can buy coverage, open enrollment periods help keep the health insurance market stable. Otherwise, people could enroll in a health plan only when they are already sick or injured, which would significantly increase the number of health insurance payouts per policyholder and likely require insurers to raise premiums.[3]
That said, some private insurance companies may allow you to sign up for an ACA-compliant health plan outside of open enrollment. However, you won’t be eligible for tax credits or other income-based savings opportunities if you enroll in one of these plans because they aren’t listed on the Health Insurance Marketplace.[4]
How Often Does Open Enrollment Occur?
Open enrollment only happens on the Marketplace once per year. Nevertheless, you may be able to sign up for Marketplace health insurance outside of open enrollment if you qualify for a special enrollment period (SEP). SEPs are triggered by major life events that can cause your health insurance needs to suddenly change, such as the following:[5]
- Getting married, divorced or separated
- Giving birth to or adopting a child
- Changing or losing your job
- Moving to a new home
- Losing your existing coverage due to the death of a family member
- Turning 26 and aging out of your parent’s health plan
- Gaining American citizenship
- Being released from prison

You should also note that certain types of health insurance have multiple enrollment periods per year. For example, if you have a Medicare plan and are also on Medicaid or qualify for the Extra Help program, you can make changes to your Medicare Part D prescription drug coverage once per month.[6]
Who Is Open Enrollment For?
Every American citizen, national and lawful resident is allowed to buy coverage through the Health Insurance Marketplace during open enrollment as long as they actively live in the United States, aren’t in prison and aren’t already enrolled in a Medicare plan.[7] Keep in mind that government-funded health care programs generally have additional eligibility requirements.
When Is Open Enrollment in 2025?
While open enrollment lasts from Nov. 1 to Jan. 15 in the majority of states, some states have different health insurance enrollment deadlines. The table below provides an overview of the regions with open enrollment dates that differ from the standard open enrollment period.
|
State/District |
Open Enrollment Period |
|
California[9] |
Nov. 1 to Jan. 31 |
|
District of Columbia[10] |
Nov. 1 to Jan. 31 |
|
Idaho[11] |
Oct. 15 to Dec. 15 |
|
Massachusetts[12] |
Nov. 1 to Jan. 23 |
|
New Jersey[13] |
Nov. 1 to Jan. 31 |
|
New York[14] |
Nov. 1 to Jan. 31 |
|
Rhode Island[15] |
Nov. 1 to Jan. 31 |
Furthermore, some states use the standard open enrollment dates of Nov. 1 to Jan. 15 but set a different deadline for shoppers who want their coverage to begin on Jan. 1. For example, individuals in Nevada can get health insurance that takes effect at the start of the year as long as they enroll by Dec. 31, rather than the standard date of Dec. 15.[16]
How Does Open Enrollment Work?
During open enrollment, you are free to make changes to your health insurance coverage, such as joining a health plan for the first time, switching to a different plan or adding eligible family members to your policy. You can also cancel an existing health plan, but you don’t have to wait until open enrollment to cancel your health insurance.[17]
To activate a new health plan, you’ll need to pay the premium for the first month of coverage up front. Meanwhile, if you already have a Marketplace plan and don’t intend to change your coverage, you’ll be automatically reenrolled in the same plan or switched over to a similar plan during the annual open enrollment period.[18]
What Happens if I Miss Open Enrollment This Year?
In some states, missing open enrollment and going without health insurance coverage could result in a financial penalty if you haven’t been approved for an exemption from the state’s individual mandate. See the table below for an overview of the regions where you may be fined if you fail to purchase and maintain health insurance.
|
State/District |
Penalty |
|
California[19] |
$900 per adult and $450 per child, or 2.5% of the amount of your gross income that exceeds your filing threshold requirements based on your tax filing status and number of dependents, whichever is higher |
|
District of Columbia[20] |
$695 per adult and $347.50 per child, or 2.5% of your household income, whichever is higher |
|
Massachusetts[21] |
$288 to $2,100 per year, depending on your household income relative to the federal poverty level |
|
New Jersey[22] |
$695 to $21,420, depending on factors like your household income and number of dependents |
|
Rhode Island[23] |
$695 per adult and $347.50 per child, or 2.5% of your household income, whichever is higher |
To tide yourself over until the next open enrollment period, you may be able to purchase a short-term health insurance policy from a private insurance company. However, these types of plans may not adhere to the minimum essential coverage standards outlined in the ACA, so they may not meet the health insurance requirements for the regions listed above.[24]
Alternatively, you could see if you or your family members are eligible for Medicaid or the Children’s Health Insurance Program (CHIP) since you can apply for these government-funded programs at any point during the year.[1] Otherwise, you may have to wait until the next open enrollment period or until you qualify for an SEP to get coverage.
What Types of Health Insurance Are Available During Open Enrollment?
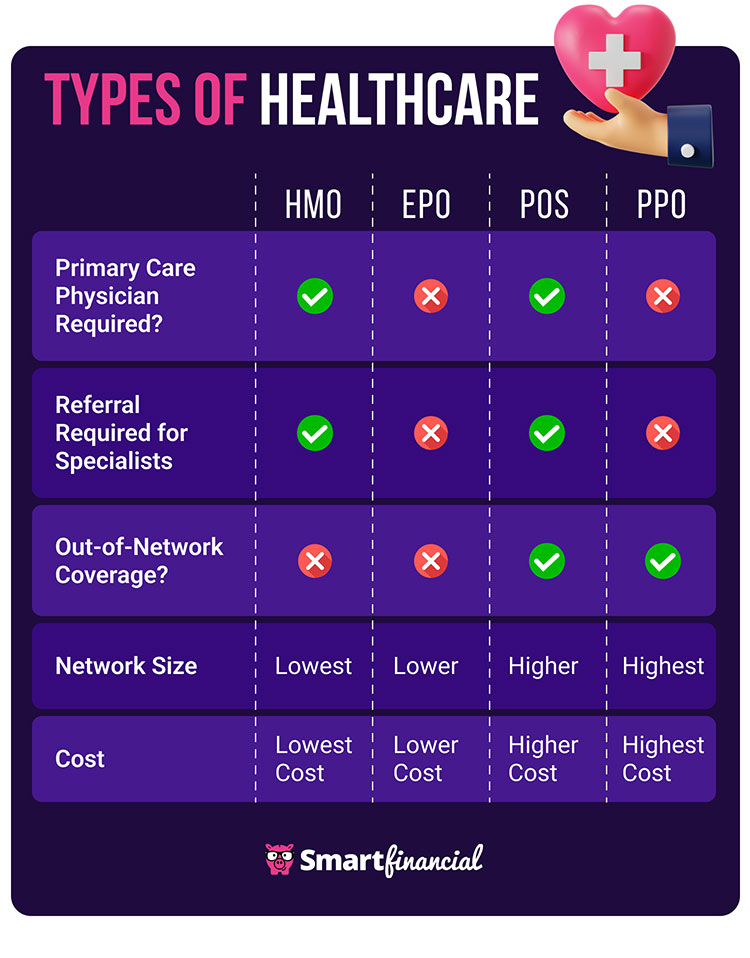
These are the most common types of ACA-compliant health insurance plans you are likely to come across as you shop on the Health Insurance Marketplace during open enrollment:[25]
- Health maintenance organization (HMO): HMOs tend to come with the lowest premiums because they only cover in-network care (except in emergencies) and don’t allow you to visit a specialist unless you’ve received a referral from your primary care physician (PCP).
- Exclusive provider organization (EPO): EPO plans also exclude coverage for routine out-of-network care, but they do allow you to see a specialist without a PCP referral.
- Point of service (POS): Your POS plan will cover care you receive from out-of-network providers — albeit with higher cost-sharing requirements — but it won’t cover treatments from a specialist unless your PCP referred you to them.
- Preferred provider organization (PPO): PPO insurance grants the greatest flexibility at the highest price, allowing you to receive treatment from providers outside of your plan’s network and visit specialists regardless of whether you have a referral.
How Do I Maximize the Open Enrollment Period This Year?
To best take advantage of this year’s open enrollment period, you should consider your family’s health insurance needs for the upcoming year, such as expected medical treatments and medication costs. Then, evaluate whether your current plan meets your coverage needs or if a different plan might be a better fit. If you are interested in changing plans, be sure to check whether any doctors you currently see are part of the new plan’s network.
You should also think about how often you are likely to use your health insurance and weigh plans based on the health insurance tier they fall into. Plans in the bronze and silver tiers have lower premiums but require you to pay more in deductibles, copays and coinsurance when you access health care. Conversely, gold and platinum plans are more expensive when it comes to regular premium payments, but they are cheaper when it comes to out-of-pocket costs.[26]

How Do I Sign Up for Health Insurance During Open Enrollment?
You may be able to sign up for Marketplace health insurance online, in person, over the phone, by mail or through an insurance company or other enrollment partner.[27] Every state either has its own health exchange website or uses the federal government’s Health Insurance Marketplace at HealthCare.gov.[28] When applying for coverage, you may need to share information like your Social Security Number, address, household income and more.
To simplify the process, consider shopping for health insurance through SmartFinancial. After you fill out a quick online questionnaire, we’ll share your coverage needs and budget with agents who can provide you with no-cost health insurance quotes. Click here to start comparing health insurance plans today.
- Insurance quotes /
- Health /
- When Is Open Enrollment
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Health Insurance Quote Online Now.
More on Health Insurance
Looking for Health Insurance?
Compare rates from dozens of companies in less than 3 minutes.