
When Is Medicare Open Enrollment?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Medicare open enrollment lasts from Oct. 15 to Dec. 7 each year. During open enrollment, current Medicare plan members can make changes to their coverage, such as joining a new prescription drug plan, dropping Medicare Advantage or switching from Original Medicare to Medicare Part C. Any new plan selections you make during open enrollment will take effect at the beginning of the new year.
Keep reading for more information about how Medicare open enrollment works and what you need to know to prepare.
|
Key Takeaways
|
On This Page

What Is Medicare Open Enrollment?
When Is Medicare Open Enrollment in 2026?
When Do 2027 Medicare Changes Take Effect?
What Can You Change During Medicare Open Enrollment?
Medicare Open Enrollment Is Not the Same as Initial Medicare Enrollment
Are There Penalties for Late Medicare Enrollment?
Are There New Medicare Plans for 2027?
Is It Worth Changing My Medicare Plan Style?
Is There an Automatic Medicare Reenrollment Process?
Original Medicare vs. Medicare Advantage
Medicare Open Enrollment at a Glance
Medicare Open Enrollment Checklist
Frequently Asked Questions

What Is Medicare Open Enrollment?
Medicare open enrollment refers to the limited window of time during which Medicare members can sign up for new plans or otherwise make changes to their health insurance coverage. Like Marketplace health insurance, Medicare doesn’t allow year-round enrollment, so you could be locked into your current coverage if you don’t make changes during the annual open enrollment period.
See below for answers to some of the most common questions eligible policyholders may have about 2026 Medicare open enrollment:[1]
|
Question |
Answer |
|---|---|
|
When does new coverage begin? |
Jan. 1, 2027 |
|
Can I switch to a Medicare Advantage plan? |
Yes |
|
Can I join a separate prescription drug plan? |
Only if you have Original Medicare |
|
Can I buy Medicare Supplement Insurance at any time? |
Maybe, but limitations may apply if you shop outside of your Medigap open enrollment period |
When Is Medicare Open Enrollment in 2026?
Medicare open enrollment lasts for a little under two months, beginning on Oct. 15 and ending on Dec. 7. Keep in mind that separate enrollment periods may apply for different types of Medicare plans, depending on the circumstances. Check the following table for examples of times when you may be able to purchase a certain type of Medicare coverage outside of the standard open enrollment window:[2][3]
|
Enrollment Period |
Dates |
Description |
|---|---|---|
|
Medicare Advantage open enrollment |
Jan. 1 to March 31 |
You can freely make changes to your Medicare Advantage plan during your first three months on Medicare — otherwise, you can only switch Medicare Advantage plans or go back to Original Medicare during Medicare or Medicare Advantage open enrollment |
|
Medigap open enrollment |
The first day of the month you are at least 65 years old and have enrolled in Medicare Part B to six months afterward |
You can only get guaranteed issue Medicare Supplement Insurance during your one-time Medigap open enrollment period, after which you could be denied or required to pay more for coverage based on the results of a medical examination |
|
Depends on the situation, but it generally begins after you experience a qualifying life event |
You can qualify for a special enrollment period and sign up for coverage at any point during the year if you face unique circumstances or experience a major life event, like being impacted by a natural disaster or losing your existing health coverage |
When Do 2027 Medicare Changes Take Effect?
As long as your enrollment request is completed by Dec. 7, 2026, your updated Medicare coverage will start on Jan. 1, 2027.[1] By Sept. 30, Part C and D plan members should receive an Annual Notice of Change letter from their provider going over updated premiums, new benefits and any other changes to their coverage slated to begin in January. Use the information in your ANOC to determine which coverage options work best for you come open enrollment.[4]
What Can You Change During Medicare Open Enrollment?
In general, you can do the following during the annual Medicare open enrollment period:[2]
- Join a Medicare Advantage plan for the first time, drop an existing Medicare Advantage plan or switch from one Medicare Advantage plan to another
- Add prescription drug coverage to or drop prescription drug coverage from a Medicare Advantage plan
- Switch from Medicare Advantage to Original Medicare or vice versa
- Join a standalone drug plan, drop an existing drug plan or switch from one drug plan to another (only if you’re covered by Original Medicare)
Medicare Open Enrollment Is Not the Same as Initial Medicare Enrollment
Medicare initial enrollment refers to the one-time window when you are generally supposed to join Medicare for the first time. Your initial enrollment dates last for seven months, beginning three months before the month you turn 65 and ending three months after the month you turn 65 — or four months before and two months after if your birthday is on the first day of the month.[5]
Are There Penalties for Late Medicare Enrollment?
If you fail to sign up for Original Medicare during your initial enrollment period, you can instead sign up during the general enrollment period from Jan. 1 to March 31 — however, a late enrollment surcharge may apply to your premiums.[5] The following table outlines the late enrollment penalties you can expect for the various parts of Medicare:[6]
|
Medicare Part |
Late Enrollment Penalty |
Example |
|---|---|---|
|
Part A (hospital insurance) |
Your premium will go up by 10% for two times the number of years you could have already been on Medicare Part A |
If you have a base premium of $311 per month for Part A but don’t purchase coverage until two years after becoming eligible, then your premium will instead be $342.10 per month for your first four years of coverage |
|
Part B (medical insurance) |
Your premium will permanently go up by 10% times the number of years you could have already been on Medicare Part B (rounded to the nearest 10 cents) |
If you have a base premium of $202.90 per month for Part B but don’t purchase coverage until three years after becoming eligible, then your premium will instead be $263.80 per month for as long as you have Medicare Part B |
|
Part D (drug coverage) |
Unless you have a comparable drug plan or qualify for Extra Help, your premium will permanently go up by 1% of the national base beneficiary premium times the number of months you could have already been on Medicare Part D (rounded to the nearest 10 cents) |
If you have a base premium of $38.99 per month for Part D but don’t purchase coverage until six months after becoming eligible, then your premium will instead be $41.30 per month for as long as you have Medicare Part D |
Keep in mind that Medicare Part A is free for most people, so the Part A late enrollment penalty only applies if you don’t qualify for premium-free coverage.[6] Meanwhile, if you’re covered by a group health insurance plan through your employer or your spouse’s employer past the age of 65, you can sign up for Part B without penalty whenever your work-based coverage ends.[7]
Are There New Medicare Plans for 2027?
A handful of changes to Medicare are slated to take effect in 2027, including reduced cost-sharing requirements for Medicare prescription drug coverage and revamped rating systems designed to make it easier to compare Part C and Part D plans.[8] In addition, the highest allowable deductible for prescription drug plans will increase by $85 in 2027, while the maximum out-of-pocket limit will rise by $300.[9]
Is It Worth Changing My Medicare Plan Style?
Whether you would benefit from changing your Medicare plan type depends on factors like your coverage requirements, your budget and how satisfied you are with your current plan. Consider the following factors when deciding whether a different type of Medicare plan would better suit your needs:[10]
-
Coverage: Certain types of Medicare may provide broader coverage than others. For example, Original Medicare doesn’t cover routine dental or vision care, but most Medicare Advantage plans do.[11] As a result, it may be worth switching to Medicare Advantage if you want claims for your dental, vision and medical care to all be covered under the same plan.
-
Costs: Next, consider whether you can afford your current plan’s premiums and out-of-pocket costs. For example, if you don’t take any prescription medicines and have minimal expected health care needs, it may be better to stick with Original Medicare than to pay more for a Medicare Advantage plan with extra benefits you don’t need.
-
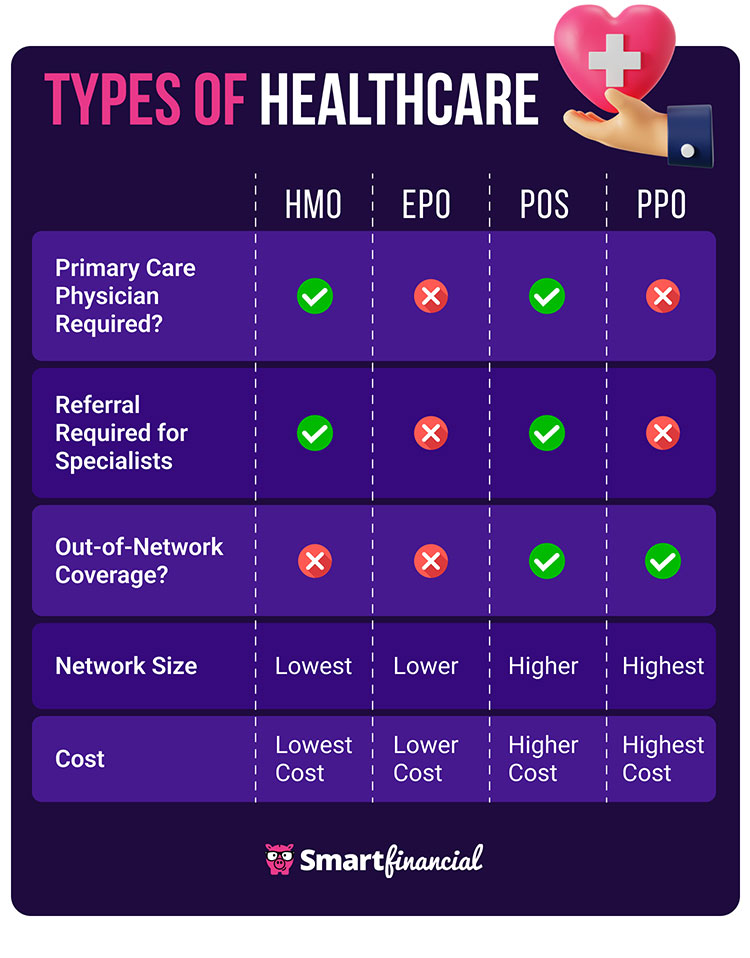
Convenience: You may want to make sure you select a plan that covers your preferred doctors, hospitals and pharmacies — especially if you opt for a Medicare Advantage health maintenance organization (HMO) plan that only covers in-network care. Conversely, you can visit out-of-network providers without restrictions if you opt for a preferred provider organization (PPO) plan, but you’ll also have to pay more.
Is There an Automatic Medicare Reenrollment Process?
Once you’ve enrolled in a Medicare plan, it generally renews itself automatically as long as you keep paying your premiums, which means you won’t need to track Medicare open enrollment dates and manually reenroll each year. The only exceptions are if your insurance company stops offering the type of Medicare Part C or D plan you have or if the federal government cancels its contract with your insurance carrier.[12]
Original Medicare vs. Medicare Advantage
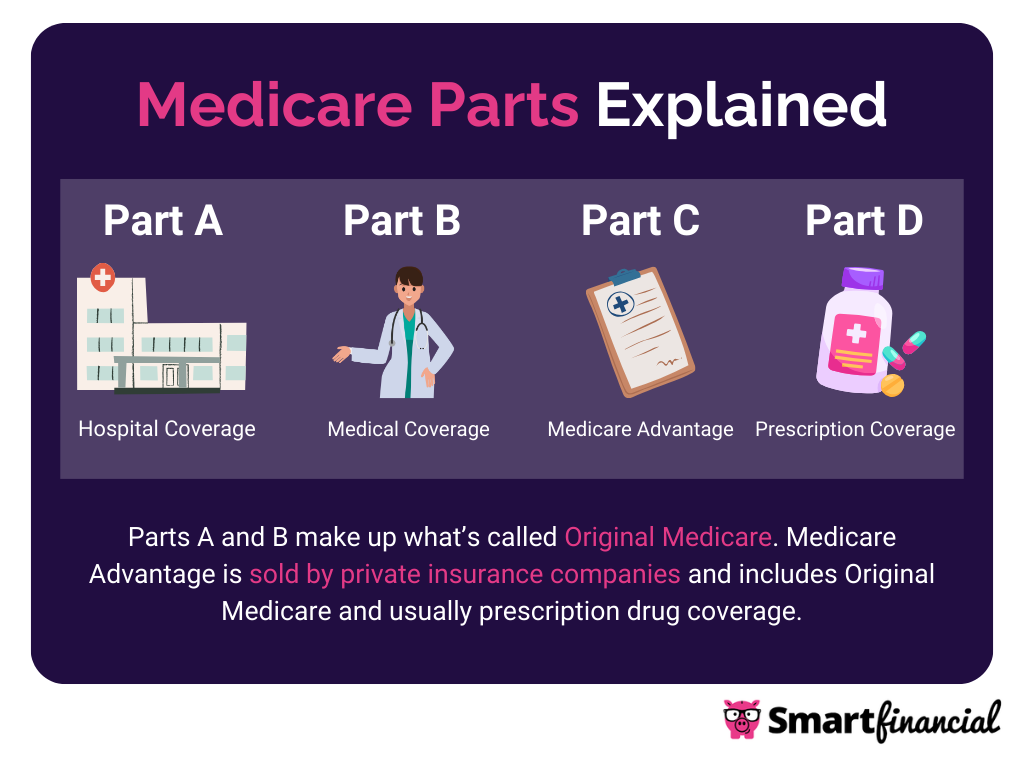
Original Medicare refers to Medicare Parts A and B as administered by the federal government, while Medicare Advantage — also known as Medicare Part C — refers to plans administered by private insurance companies that offer the same or more benefits. There are pros and cons to each type of Medicare coverage, so you need to evaluate all the potential costs and benefits to determine which type of coverage makes the most sense to you.[13]
|
|
Original Medicare |
Medicare Advantage |
|---|---|---|
|
Network |
Covers health care from every doctor and hospital in the United States that accepts Medicare without requiring referrals to see specialists |
May only cover routine care from providers in your plan’s network and may require a referral from your primary care physician before you can see a specialist |
|
Premiums |
You must pay a premium for Part B and potentially Part A — along with a separate premium if you opt for additional Part D coverage |
You must continue paying your Part B premium while also paying the Part C premium — though some plans don’t come with a separate premium and may even cover some or all of your Part B premium |
|
Out-of-Pocket Costs |
Most services covered by Part B require a 20% coinsurance payment after you surpass your annual deductible |
Out-of-pocket costs differ based on your plan’s details and the types of medical services you receive |
|
Out-of-Pocket Limits |
There’s no limit on how much you may have to spend out of pocket unless you purchase supplemental coverage, such as Medigap |
Your insurer will cover 100% of the costs for covered health care services after you reach your annual out-of-pocket maximum |
|
Benefits |
Covers most medically necessary treatments and medical supplies received during an inpatient hospital stay or a doctor’s appointment |
Covers everything covered by Original Medicare and often additional services, such as vision, dental and hearing care |
|
Drug Coverage |
Prescription drug coverage must be purchased separately through Medicare Part D |
Prescription drug coverage is typically included automatically |
Medicare Open Enrollment at a Glance
- Definition: Medicare open enrollment is an annual sign-up window when existing Medicare members can make changes to their coverage, such as adding prescription drug coverage or switching from Original Medicare to Medicare Advantage.
- Dates: Each year, Medicare open enrollment runs from Oct. 15 to Dec. 7. That said, separate enrollment dates may apply for certain types of Medicare, such as Medicare Advantage and Medicare Supplement Insurance.
- Eligibility: You can only sign up during open enrollment if you’re already on Medicare because you’re at least 65 years old or have a disability, end-stage renal disease or ALS. If you haven’t yet joined Medicare, you generally need to sign up during your initial enrollment period, which is a seven-month window surrounding your 65th birthday.
- Penalties: Medicare-eligible individuals who miss their initial enrollment period can instead sign up during general enrollment from Jan. 1 to March 31, but they’ll have to pay higher premiums as a penalty for joining late. Fortunately, if you’ve already enrolled in Medicare, you’ll generally be automatically reenrolled, even if you don’t take action during open enrollment.
- Plan changes: While Medicare plans shouldn’t undergo massive alterations in 2027, there are some changes to keep an eye out for, including lower costs associated with prescription drug coverage and updated star rating systems that may make it easier to compare certain Medicare plans.
- Plan options: Original Medicare is operated by the government, and its main benefit is that it covers medical care from the vast majority of medical providers in the United States. Conversely, Medicare Advantage is supplied by private companies that are reimbursed by the government, and it can be beneficial because it offers broader coverage, has $0 premium options and places a cap on your out-of-pocket spending.
Medicare Open Enrollment Checklist
Go over the following checklist to make sure you’re prepared before Medicare open enrollment begins in October:[14]
- Gather information: You’ll need to have a lot of information at the ready when applying for Medicare plans to confirm your eligibility and make sure the plan you want provides the right level of coverage. Be prepared to share your date of birth, your contact information, the policy number listed on your Medicare card and information about the long-term care facility you live in, if applicable.
- Review your ANOC: If your Medicare Advantage or standalone prescription drug plan undergoes any changes that could affect your costs or covered benefits, those changes should be explained in your plan’s Annual Notice of Change. Reviewing this before open enrollment is crucial to verify whether your current plan will still work for you or whether you need to shop around for a different plan.
- Evaluate your coverage needs: Your coverage needs may have changed since last year based on your current health status. For example, if you are currently receiving treatment for a chronic illness or have been prescribed multiple medications, you may want to look into plans that come with fewer out-of-pocket costs each time you receive care.
- Make a budget: Seniors on a fixed income need to make sure they aren’t weighed down by excessive premiums or out-of-pocket costs related to Medicare. At the same time, you need to make sure you have enough coverage to prevent devastating financial losses whenever you do need medical care. Be sure to weigh all of these cost factors when deciding which Medicare plan fits best within your budget.
- Decide how you want to pay: Once you’ve enrolled in a Medicare plan, you may have different options for how you’d like to pay your premiums. For example, you may be able to pay with an electronic funds transfer from your bank account, an automatic deduction from your Social Security benefits or an official Medicare payment coupon.
You can shop around for Medicare Advantage plans for free by using an online insurance marketplace, like SmartFinancial. Simply answer a few questions about your coverage needs, and then we’ll connect you with an insurance agent who can help you compare the best plans available in your area. Request a Medicare Advantage quote in as little as a few minutes today!
- Insurance quotes /
- Medicare /
- Medicare Open Enrollment
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Compare Medicare Plans Online Now.
More on Medicare
Looking for Medicare Plans?
Compare rates from dozens of companies in less than 3 minutes.