

How Do Special Enrollment Periods Work?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
A special enrollment period (SEP) is a window of time when you can sign up for health insurance through the Health Insurance Marketplace, your employer or Medicare outside of open enrollment. In general, you can only qualify for an SEP if you experience a major life event that substantially changes your health coverage needs, such as getting married or moving to a different state.
Keep reading for a breakdown of the various ways you can become eligible for special enrollment and what steps you need to take to obtain coverage during an SEP.
|
Key Takeaways
|
On This Page

What Is a Special Enrollment Period?
How Does Special Enrollment Work?
What Are Common Qualifications for Special Enrollment?
How Long Does the Special Enrollment Period Last?
What Should You Do if You’re Turned Down for Special Enrollment?
How To Enroll After You Qualify for a Special Enrollment Period
FAQs

What Is a Special Enrollment Period?
A special enrollment period is a limited time frame surrounding a major event in your life — such as having a baby or losing your job — during which you can buy a new health insurance plan or update your existing coverage through the federal Health Insurance Marketplace or your state’s corresponding health exchange. Special enrollment periods are also available if you are on Medicare or have employer-sponsored coverage.
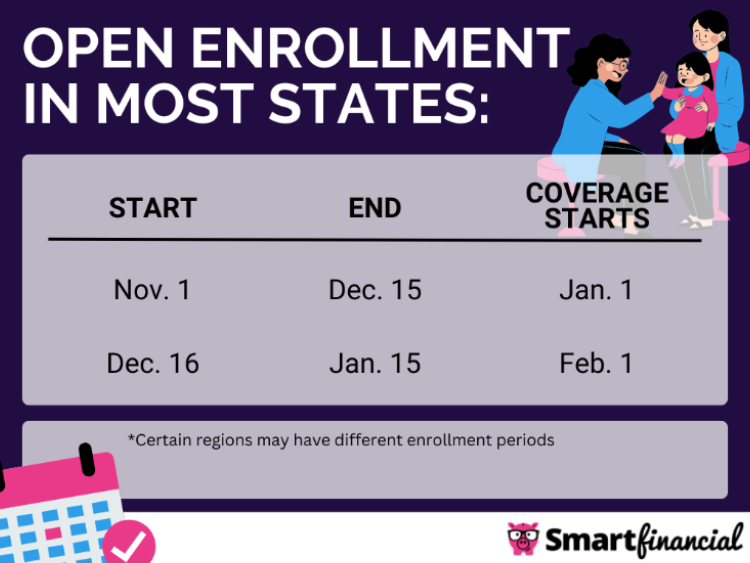
Unless you qualify for an SEP, you can only sign up for most kinds of Affordable Care Act (ACA) health insurance plans during open enrollment. In most states, open enrollment lasts from Nov. 1 to Jan. 15. Specifically, you can buy your plan between Nov. 1 and Dec. 15 for coverage beginning at the start of the new year, or you can enroll from Dec. 16 to Jan. 15 for coverage starting on Feb. 1.[1]
Keep in mind that you may be able to buy a health plan directly from a private health insurance company outside of open enrollment, even if you don’t qualify for an SEP. However, these plans usually don’t meet the ACA’s minimum essential coverage standards. Also, since these plans aren’t listed on the Marketplace, you can’t take advantage of tax credit subsidies or other income-based savings when you purchase one of them.[2]
How Does Special Enrollment Work?
When you apply for special enrollment, you may need to submit documents confirming you have experienced a qualifying life event that makes you eligible for an SEP.[3] For example, you may have to submit a wedding certificate if you recently got married or a birth certificate if you recently had a child. If you’re eligible, you can compare rates for various health insurance plans through the Marketplace before settling on and enrolling in one.
What Are Common Qualifications for Special Enrollment?
In the following sections, you’ll see examples of the major categories of qualifying life events that can enable you to participate in a special enrollment period on the Health Insurance Marketplace.

Loss of Coverage
If anyone in your household loses their existing health insurance, it will trigger an SEP, allowing affected plan members to choose a new health plan. Examples of situations where you have lost coverage and may be eligible for special enrollment include the following:[3]
- You get fired from or quit your job and lose your employer-sponsored group health insurance, or you are the dependent of someone who loses their work-based coverage
- Your insurance company discontinues your current Marketplace plan
- You lose eligibility for a university-sponsored student health insurance plan
- You decline to renew a plan that ends outside of open enrollment
- You are no longer eligible for Medicaid or the Children’s Health Insurance Program (CHIP), or you declined to sign up for a private plan during open enrollment because you were incorrectly told you might be eligible for Medicaid or CHIP
- You lose premium-free Medicare Part A coverage
- You age out of your parents’ health insurance upon turning 26 or otherwise cease to be their dependent
- You are no longer eligible to receive coverage through a family member due to death or divorce
You should note that you won’t qualify for an SEP if you choose to unenroll from someone else’s health insurance plan while you are still their dependent — unless you become eligible for Marketplace savings due to a drop in household income or a change to your previous coverage. Additionally, you won’t qualify for an SEP if you lose coverage because you failed to provide mandatory enrollment or verification documents.[3]
New Benefit Offers
It will also trigger a special enrollment period if an employer offers to help anyone in your household pay for medical services. For example, you may be able to update your Marketplace health insurance if an employer enrolls you in an Individual Coverage Health Reimbursement Arrangement (ICHRA) or Qualified Small Employer Health Reimbursement Arrangement (QSEHRA) to help cover health care services and other related expenses.[3]
Changes in Your Household
Anytime there is a change in the membership of your household, it may affect your family’s health coverage needs and make you eligible for special enrollment. For example, you could change your health insurance plan at any point in the year following life events like these:[3]
- You get married
- Someone in your household gives birth, adopts a child or takes in a foster care child
- You lose coverage after someone in your household dies
Remember that losing your existing health insurance coverage may be a prerequisite for special enrollment, even if you have experienced a major life event. For example, you will not necessarily qualify for an SEP after getting divorced or legally separated — you will, however, qualify for one if you lose your coverage because of your divorce or legal separation.[3]
Changes in Your Residence
Since health plan service areas are often limited to specific geographic regions, you will typically qualify for an SEP if you move to a different ZIP code or county. This type of SEP can also apply to students who move for school, seasonal workers who move for employment opportunities and anyone who moves from a shelter or some other type of transitional housing.[3]
To qualify for a moving-based SEP, you generally need to show proof that you were enrolled in an ACA-compliant health plan for at least one day during the 60-day period leading up to your move — unless you are moving from a foreign country to the United States or from an American territory to a state or Washington, D.C.[3]
Other Qualifying Life Events
Several other qualifying life events can potentially allow you to make changes to your health insurance coverage, including the following:[3][4]
- You gain membership in an indigenous tribe recognized by the federal government
- You become an Alaska Native Claims Settlement Act (ANCSA) Corporation shareholder
- You become a United States citizen
- You are released from prison
- Your service in AmeriCorps State and National, Volunteers in Service to America (VISTA) or National Civilian Community Corps (NCCC) begins or ends
- An unexpected hospitalization or natural disaster prevents you from signing up for coverage during open enrollment
- You fail to correctly sign up for coverage during open enrollment because of a technical error on the Marketplace website or an insurance agent’s mistake or intentional misrepresentation
- The Marketplace website presents inaccurate information about a plan you sign up for
- You become newly eligible for savings on a Marketplace plan
- You gain a dependent or become someone else’s dependent due to a court order
- Your spouse has abandoned or abused you, and you want to remove yourself from their health plan
- The Marketplace Appeals Center approves your request for an SEP
In addition, some states that operate their own health exchange websites may offer an even wider list of qualifying life events. For example, if you live in California, you may become eligible for an SEP through Covered California due to situations like these:[5]
- You age out of a child-only plan upon turning 19
- You pay the Individual Shared Responsibility Penalty for not having health insurance during the previous tax year
- The government declares a state of emergency due to a crisis, such as a wildfire outbreak
- You qualify for a health insurance stipend through your gig as an independent contractor for a rideshare or delivery service
- You enter into a domestic partnership
- You lose coverage after leaving active duty in the military, the reserves or the California National Guard
- You learn that you met the requirements for an SEP previously but were not informed of your eligibility in a timely manner
- You lose eligibility for the hardship exemption to California’s individual mandate outside of the annual open enrollment period
- You have met your share of the costs for your Medi-Cal plan in one of the last two months (this type of SEP can only be triggered once per year)
- Your health care provider leaves your insurance plan’s network while you are receiving treatment related to pregnancy, a terminal illness, an acute condition, a serious chronic condition, the care of a child under the age of 3 or a surgery or procedure that will occur within 180 days of the plan’s termination or start date
How Long Does the Special Enrollment Period Last?
Special enrollment periods on the Marketplace usually last from 60 days before the qualifying life event to the day the event takes place, or they may last from the day the event takes place to 60 days after.[6] Some SEPs — such as one triggered by losing coverage from Medicaid or CHIP — may last up to 90 days after the qualifying life event.[3] Meanwhile, job-based plans are only required to offer SEPs lasting at least 30 days.[6]
What Should You Do if You’re Turned Down for Special Enrollment?
If you believe you should qualify for a special enrollment period but your initial application is rejected, you can file an appeal through the Health Insurance Marketplace. You generally need to submit your appeal within 90 days of receiving an Eligibility Notice, although you may be able to get an extension if you can prove that you had a legitimate reason for missing the deadline.[7]
How To Enroll After You Qualify for a Special Enrollment Period
There are various ways to compare health insurance quotes and apply for health plans once you have determined you are eligible to enroll. For many shoppers, the most straightforward option may be to apply online at HealthCare.gov or their state’s equivalent health insurance exchange website. You can also enroll over the phone or send a paper application in the mail.[8]
Alternatively, you can work with an agent to get help comparing quotes or take advantage of an independent insurance marketplace, such as SmartFinancial. If you fill out a simple online questionnaire, we can get you in touch with local agents who can provide you with quotes for health plans that match your coverage needs and budget. Click here to get started on comparing health insurance quotes at no cost in as little as a few minutes!
- Insurance quotes /
- Health /
- Special Enrollment Period
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Health Insurance Quote Online Now.
More on Health Insurance
Looking for Health Insurance?
Compare rates from dozens of companies in less than 3 minutes.