
What Are the Different Parts of Medicare?
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
The different parts of Medicare cover hospital visits (Part A), medical services (Part B) and prescription drugs (Part D), with supplemental options to help pay out-of-pocket costs (Medigap) and alternatives for coverage through private insurers (Medicare Advantage). Many parts of Medicare can be combined to fill coverage gaps, although there are limitations between the types.
Those who are about to meet Medicare eligibility requirements should read on to learn more about the different coverage options for each part of Medicare and their costs.
|
Key Takeaways
|
On This Page

What Are the Different Parts of Medicare?
Medicare Part A (Hospital Services)
Medicare Part B (Medical Services)
Medicare Part C (Medicare Advantage)
Medicare Part D (Prescription Drugs)
Medicare Supplement Plans (Medigap)
How the Parts of Medicare Work Together
Original Medicare vs. Medicare Advantage
Which Parts of Medicare Do I Need?
Parts of Medicare at a Glance
Will Medicare Cover All of My Medical Needs?
Frequently Asked Questions

|
Part of Medicare |
What Is It For? |
What It Covers |
Costs |
|---|---|---|---|
|
Part A |
Hospital services |
Inpatient care, skilled nursing, hospice, limited home health and blood tests |
$0 if you've paid 10 years of taxes, or $311 to $565 if you’ve paid less; $1,735 deductible |
|
Part B |
Medical services |
Doctor visits, outpatient care, home health, preventive services and medical equipment |
$202.90 per month or more; $283 deductible |
|
Part C |
Medicare Advantage |
Both Medicare Parts A and B, with some plans including Part D; may also add coverage for vision, dental and hearing |
Varies between plans and insurers |
|
Part D |
Prescription drugs |
Prescription medication costs |
Varies between plans; $615 deductible cap; $2,100 out-of-pocket cap |
|
Medigap |
Out-of-pocket costs |
Copayments, coinsurance and deductibles for Original Medicare services |
Varies between plans and location |
What Are the Different Parts of Medicare?
Medicare has four different parts:
- Part A (hospital services)
- Part B (medical services)
- Part C (Medicare Advantage)
- Part D (prescription drugs)
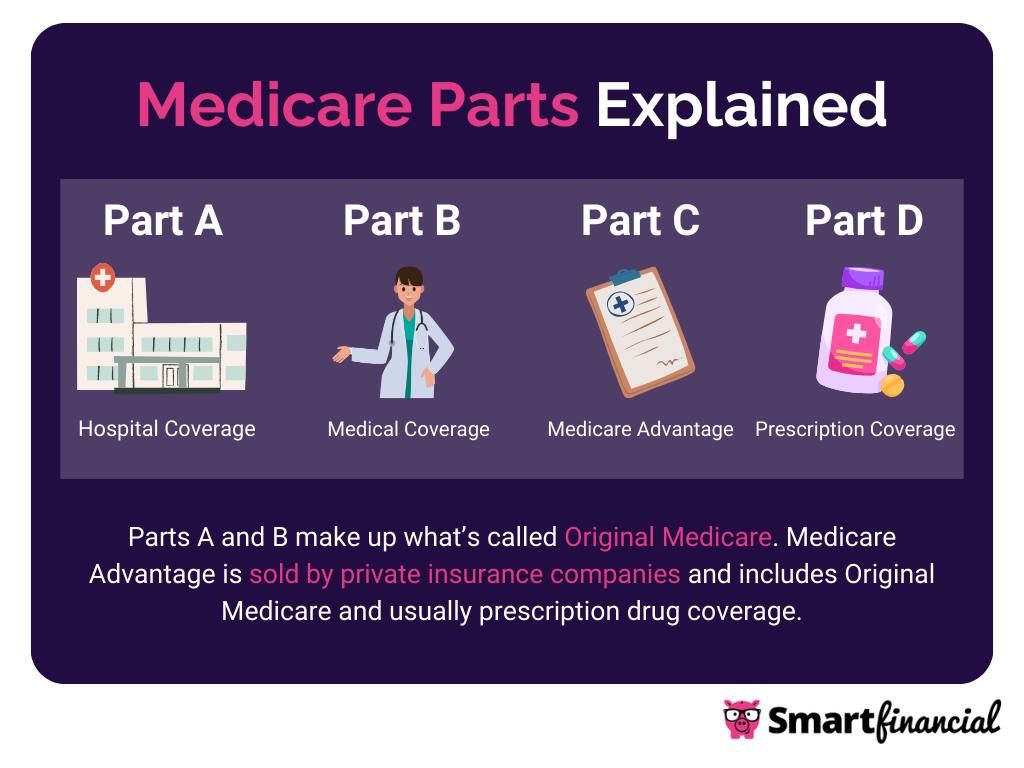
Part A and B are collectively called Original Medicare and run by a federal agency, the Centers for Medicare & Medicaid Services (CMS). Original Medicare covers most healthcare services but has gaps that additional options can fill.
One option is Part C, also called Medicare Advantage, a standalone health plan that offers Medicare coverage and is sold by private companies regulated by Medicare. Another is Part D, an optional addition to Original Medicare offered by private insurers that helps cover prescription drugs. Medigap (Medicare Supplemental Plan) also helps those on Original Medicare fill coverage gaps for an additional cost.
Medicare Part A (Hospital Services)
Medicare Part A covers inpatient care for hospital visits, hospice care and skilled nursing facility care. See below for an overview of what Medicare Part A covers and does not cover.
What’s Covered
Here’s what is covered under Medicare Part A:[1]
- Inpatient hospital care
- Skilled nursing facility care
- Hospice care
- Some home health care (e.g., physical therapy, occupational therapy services)
- Blood tests
What Isn’t Covered
Here’s what isn’t covered under Medicare Part A:[2]
- Long-term care (also called custodial care)
- Concierge care (concierge medicine, retainer-based medicine, boutique medicine or direct care)
- Non-medical care and non-skilled personal care assistance (e.g., home-delivered meals, adult day health care)
Additionally, some potential aspects of inpatient stay and hospice care also don’t receive coverage, such as:[3]
- Private-duty nurses
- In-room televisions and phones
- Private rooms (unless deemed medically necessary)
- At-home hospice care (including nursing homes)
Part A Costs
Most people don’t pay a Medicare Part A premium if they or their spouse paid Medicare taxes for at least 40 quarters (10 years). Otherwise, Medicare will cost $311 if you’ve paid taxes for at least 7.5 years or $565 if you’ve paid taxes for less than that. A $1,736 deductible — your out-of-pocket cost when receiving approved healthcare services — will apply for each benefit period.[4][5]
Medicare Part B (Medical Services)
Medicare Part B covers a variety of outpatient medical services and doctor visits. Below, we highlight which Medicare services are covered and excluded under Medicare Part B.
What’s Covered
Here’s what is covered under Medicare Part B:[6]
- Medically necessary services
- Clinical research studies
- Mental health and substance use services and programs, including up to four face-to-face alcohol misuse screenings and counseling sessions each year[7]
- Ground ambulance transportation to a hospital or other healthcare facility
- Bariatric surgeries (gastric bypass surgery, laparoscopic banding surgery or some other type of procedure related to morbid obesity)[8]
- Preventive services (flu shots, glaucoma tests and screenings for HIV and Hepatitis B and C and other early illness detection services)[9]
- Up to 12 acupuncture visits for eligible chronic low back pain[10]
- Chemotherapy[11]
- Chiropractic services[12]
- Chronic care management (treatment for chronic conditions such as arthritis and diabetes, comprehensive care plans, medication and other support)[13]
- Colorectal cancer screening (colonoscopies, fecal occult blood tests and flexible sigmoidoscopies)[9]
- Three-month trial of a continuous positive airway pressure (CPAP) device[14]
What Isn’t Covered
Here’s what isn’t covered under Medicare Part B:[2]
- Most dental care (including dental implants and dentures)
- Eye exams
- Cosmetic surgery
- Massage therapy
- Routine physical exams
- Hearing aids and their fitting exams
- Routine foot care
Part B Costs
The Part B premium will cost $202.90 per month in 2026. You are responsible for a $283 deductible plus a 20% coinsurance payment for most covered services. If you fail to sign up during your initial enrollment without a qualifying exemption, your Part B premium will increase by 10% for each 12-month period after you become eligible as a late enrollment penalty.[4]
Medicare Part C (Medicare Advantage)
Part C, also called Medicare Advantage, is an alternative to Original Medicare that bundles Part A, Part B and sometimes Part D into a single health plan. Instead of receiving Original Medicare coverage directly through the federal government, Medicare Advantage plans are sold by private insurance companies and regulated by the federal government. A Medicare Advantage plan may include benefits otherwise excluded from Original Medicare, such as vision, hearing and dental coverage.[15]
Keep in mind that with Medicare Advantage, you may only get coverage from doctors within your plan's network. With Original Medicare, you can use any doctor or hospital that accepts Medicare.[16]
Part C Costs
On average, the Medicare Advantage premium in 2026 is $15 per month with prescription drug coverage (Part D), although costs range from $0 to over $100. Costs can vary between insurers and plan types. You will still need to cover the premium for Part B as an additional cost to your Medicare Advantage plan’s premium.[17]
Medicare Part D (Prescription Drugs)
Medicare Part D pays for prescription drugs, including generic and brand-name drugs. Part D is optional and can be purchased at an additional cost to supplement Original Medicare plans. Like Part C, private insurers offer Part D plans, and the federal government regulates them.
Medicare Advantage (Part C) plans may already include Part D coverage, but not always. You should confirm with your Medicare Advantage plan provider if you require prescription drug coverage, as you cannot buy Part D and Part C simultaneously.[18]
Part D Costs
The national average monthly premium for Part D is $38.99 in 2026, though higher-income enrollees may pay more. However, Part D coverage has no fixed premium, and costs vary by individual and may change each year.[18]
Medicare Supplement Plans (Medigap)
Medigap, also called Medicare Supplement Insurance, is a policy sold by private insurers to cover gaps not covered in an Original Medicare plan, like copayments, coinsurance and deductibles. Medigap may even cover medical care when you travel outside the U.S.[19] You must have Medicare Part A and Part B to qualify for Medigap.[20][21]
Medigap policies will not include prescription drug coverage. To cover prescription drug costs, you must purchase a prescription drug plan (Part D), which may result in separate premiums for Medigap and Part D if you purchase both. Additionally, you can’t have Medigap and Medicare Advantage plans at the same time.[21]
Medigap Costs
Medigap benefits are identified by plan types or letters, and each letter has the same benefits regardless of the insurer. The premium is the only difference between different insurers’ Medigap plans with the same letter. For example, California’s Medigap Plan A’s premiums range between $120 and $896, depending on your age, health status and other factors.[22][23]
How the Parts of Medicare Work Together
Parts A and B (Original Medicare) help cover hospital visits and routine medical care, while Part D adds prescription drug coverage. Medigap helps supplement Original Medicare by covering out-of-pocket costs. Medicare Advantage can be an alternative option, providing the same coverage as Original Medicare and the option to include Part D coverage plus added benefits, such as dental, vision and hearing.
Original Medicare vs. Medicare Advantage
Here’s a breakdown of the differences between Original Medicare and Medicare Advantage:[16]
|
|
Original Medicare |
Medicare Advantage |
|---|---|---|
|
Doctor and Hospital Choice |
Any doctor or hospital that accepts Medicare. |
May be limited to doctors and hospitals within your plan’s network. |
|
Specialist Coverage |
Typically doesn’t require a specialist referral. |
May require a specialist referral. |
|
Cost |
Typically pays Part B’s monthly premium. Features 20% coinsurance after meeting your deductible. |
Typically pays Part B’s monthly premium and the Medicare Advantage premium. Out-of-pocket costs vary between plans. |
|
Yearly Limit on Out-of-Pocket Costs |
There is no yearly limit unless you have Medigap or other insurance (like Medicaid). |
Yearly limit varies by plan. |
|
Can You Get Medigap |
You can purchase Medigap to help pay for out-of-pocket costs not covered by Medicare. |
You cannot purchase Medigap. |
|
What’s Covered? |
Most medically necessary services and supplies in hospitals, doctors’ offices and other health care facilities. |
The same services covered by Original Medicare, alongside other benefits such as vision, hearing and dental. |
|
Prior Authorization |
You typically don’t need prior authorization to cover services or supplies. |
You may need prior authorization for coverage of certain services or supplies. |
|
International Coverage |
Typically doesn’t cover care outside of the U.S. |
Typically doesn’t cover care outside of the U.S. |
Which Parts of Medicare Do I Need?
You can choose two different pathways for Medicare, depending on whether you want coverage from private insurers or through the federal government:
- You can get Parts A and B (Original Medicare), with the option of getting Part D for prescription drug coverage. You may also get Medigap to help cover extra out-of-pocket costs.
- You can choose Medicare Advantage (Part C), which may include prescription drug coverage (Part D).
Your choice will depend on your needs. For example, if you want coverage for vision and dental, it may be preferable to get Medicare Advantage. However, if you only need basic medical coverage and don’t use prescription drugs, you may be able to choose only Original Medicare.
Parts of Medicare at a Glance
Below is the essential information you should know about the different parts of Medicare:
- Medicare Part A (hospital insurance) and Part B (medical insurance) are called Original Medicare and are run by the federal government.
- Part C, also called Medicare Advantage, replaces Original Medicare and is offered by private insurers.
- Part D is optional prescription drug coverage that can be added to Original Medicare and is sold by private insurers.
- Medicare Advantage plans may include prescription drug coverage as part of their benefits.
- Medigap, or Medicare Supplemental Insurance, helps cover gaps in Original Medicare but doesn’t include drug coverage and can’t be combined with Part C.
- While Part C bundles some parts of Medicare into a single plan, you are still responsible for paying your Part B premium.
Will Medicare Cover All of My Medical Needs?
Original Medicare may not cover all your needs if you need specific coverage, such as dental or vision. If you need more robust coverage, you may want to consider enrolling in a Medicare Advantage plan through a private insurer instead of Original Medicare.
Even with Medigap, Original Medicare won't cover all costs and services. As a result, always compare plans to ensure the one you choose best meets your coverage needs.
- Insurance quotes /
- Medicare /
- Parts Of Medicare
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Compare Medicare Plans Online Now.
More on Medicare
Looking for Medicare Plans?
Compare rates from dozens of companies in less than 3 minutes.