
Medicare vs. Medicaid: What’s the Difference?
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Medicare is a federal health insurance program typically available to people age 65 and older, while Medicaid is a joint federal-state-run program for low-income and other qualifying individuals. While both programs provide affordable health coverage, their benefits don’t fully overlap, which can leave gaps in care.
If you qualify for either Medicare or Medicaid, read on for a comprehensive overview and comparison of the two programs, including the benefits of dual enrollment if you qualify.
|
Key Takeaways
|


Medicare vs. Medicaid: What Are the Differences?
Medicare is a federal program that provides health insurance coverage for people ages 65 and older and others who meet eligibility requirements, while Medicaid is a joint federal-state program that provides health insurance coverage for low-income families and other qualifying individuals who meet state requirements. Below, we’ll go over the differences between these two forms of health coverage in more detail:[1][2][3][4][5][6]
|
Medicare |
Medicaid |
|
|---|---|---|
|
Eligibility |
Those age 65 and older, those with certain disabilities and those with end-stage renal disease (ESRD) or amyotrophic lateral sclerosis (ALS). |
Certain low-income families, children, pregnant women and other federally mandated eligibility groups. States may expand eligibility to additional qualifying populations. |
|
Coverage |
Hospital services, medical services, prescription drugs and limited skilled nursing facility care. |
Coverage for doctor visits, inpatient hospital services and outpatient hospital services is mandatory. Each state may add additional benefits. |
|
Additional coverage |
Depends on whether the individual purchased Medicare Part D (prescription drug coverage). Medicare Advantage members may also get extra benefits, like vision and dental. |
Depends on the state and local government, except for what the federal government deems mandatory coverage. |
|
Cost per month |
The standard Medicare Part B premium is $202.90 per month in 2026, although higher-income beneficiaries may pay more. Part A is premium-free for most eligible individuals. Additional premiums, deductibles and out-of-pocket costs depend on coverage selections. |
Varies by state and income, but is often available at low or no cost. Some states may have copayments. |
|
Funding |
Funded through payroll taxes, federal revenues, beneficiary premiums and other sources. |
State and federal governments. |
What Is Medicare?
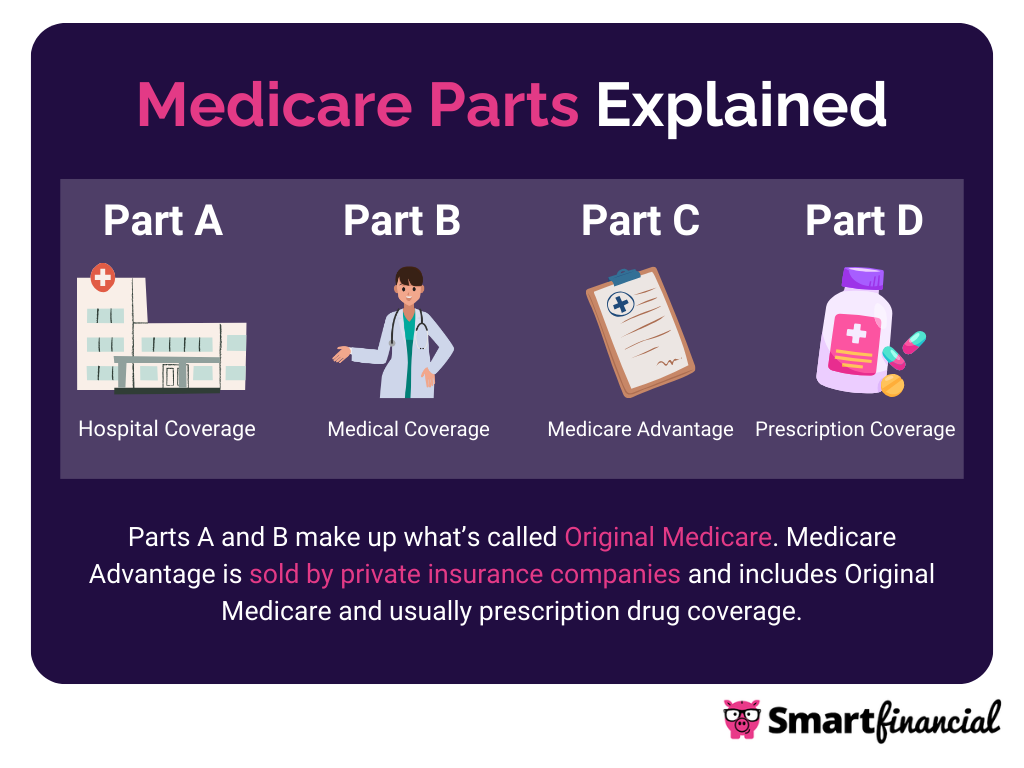
Medicare is a federal program that provides several types of coverage, including hospital insurance (Part A) and medical insurance (Part B). Parts A and B are collectively referred to as “Original Medicare.”[1] Medicare Advantage combines Parts A and B into a single plan called Part C.
Below, you will find a breakdown of coverage for Parts A, B and C:
|
Hospital Insurance (Part A) |
Medical Insurance (Part B) |
Medicare Advantage (Part C) |
|---|---|---|
|
Inpatient care in a hospital |
Clinical research: testing new surgical treatments, medicines, diagnostic care and more |
Inpatient care in a hospital and clinical research: testing new surgical treatments, medicines, diagnostic care and more |
|
Skilled nursing facility care |
Skilled nursing facility care and ambulance services |
|
|
Nursing home care (not custodial or long-term) |
Durable medical equipment (DME) |
Nursing home care (not custodial or long-term) and durable medical equipment (DME) |
|
Hospice care |
Mental health: inpatient, outpatient, partial hospitalization (PHP) |
Mental health: inpatient, outpatient, partial hospitalization (PHP). Hospice care is covered by Original Medicare for eligible Medicare Advantage enrollees. |
|
Home health care |
Limited outpatient prescription drugs |
Most prescription drugs |
What Is Part D in Medicare?
Most Medicare Advantage plans also include prescription drug coverage through Medicare Part D. Medicare Advantage (Part C) and Medicare Part D plans are offered by private insurers. However, you must qualify for Medicare at the federal level to enroll in these parts. Original Medicare users can purchase Part D separately.[1]
To help with prescription costs, Medicare Part D plans generally use drug formularies organized into tiers:[8]
- Tier 1: Lowest copayment, covers most generic prescription drugs
- Tier 2: Medium copayment, covers preferred, brand-name prescription drugs that aren’t necessarily available in a generic form
- Tier 3: Higher copayment, covers non-preferred, brand-name prescription drugs
- Specialty tier: Highest copayment, covers high-cost prescription drugs
You can apply for an exception if your doctor requires a brand-name medication, even if a similar drug is in a lower tier. This exception may lower your copayment.[9] Once your annual out-of-pocket costs reach $2,100, the remaining costs for covered Part D medications are covered for the year.[10]
What Is Medigap?
Private insurers sell Medigap, also known as Medicare Supplement Insurance, to fill in the gaps left by Original Medicare coverage, such as deductibles, copayments and coinsurance. Medigap may even cover medical care while you travel outside the United States. To be eligible for Medigap, you must have both Medicare Part A and Part B.[11]
Medigap does not cover prescription medication. To cover prescription drugs, you must get a prescription drug plan (Part D); if you purchase both Medigap and Part D coverage, you may have to pay separate premiums for each. Additionally, you cannot have Medicare Advantage and Medigap insurance at the same time.[11]
What Is Medicaid?
Medicaid is a public insurance program that provides health coverage to low-income families and individuals. This includes adults, children, seniors and those with disabilities – including people on Medicare.
Medicaid covers hospital care, physician care, lab services and home and nursing services. Medicaid also covers prescription drugs in all states. Other benefits, such as vision care, dental care, personal care services and hearing aids, are typically also covered.[12][13]
Medicaid is jointly funded by the state and federal governments, so it operates differently from state to state. However, all states must still use federal guidelines.[14]
Federal guidelines are broad, giving states flexibility in how they design and implement their programs. As a result, eligibility and benefits vary from one state to another. For example, some states have expanded Medicaid to adults with incomes up to 138% of the federal poverty level.[13][14]
What Does Medicaid Cover?
While Medicaid is operated at the state level, every state must offer certain services through Medicaid. Below is a list of required services:[12]
- Inpatient hospital services
- Outpatient hospital services
- Early and periodic screening, diagnostic and treatment services
- Nursing facility services
- Home health services
- Physician services
- Rural health clinic services
- Federally qualified health center services
- Laboratory and X-ray services
- Family planning services
- Nurse-midwife services
- Certified pediatric and family nurse practitioner services
- Freestanding birth center services (when licensed or otherwise recognized by the state)
- Transportation to medical care
- Tobacco cessation counseling for pregnant women
Optional benefits that may be included as part of your state’s Medicaid program can include:[12]
- Prescription drugs
- Clinic services
- Physical therapy
- Occupational therapy
- Speech, hearing and language disorder services
- Respiratory care services
- Other diagnostic, screening, preventive and rehabilitative services
- Dental services
- Dentures
- Prosthetics
- Eyeglasses
- Other practitioner services
- Private duty nursing services
- Personal care
- Hospice
- Case management
- Services for individuals aged 65 or older in an institution for mental disease
- Services in an intermediate care facility for Individuals with intellectual disabilities
- State plan home and community-based services
- Self-directed personal assistance services
- Community first choice option
- Tuberculosis-related services
- Inpatient psychiatric services for individuals under age 21
- Health homes for enrollees with chronic conditions
Medicare vs. Medicaid for Long-Term Care
When it comes to long-term care, Medicare and Medicaid offer different benefits. For example, Medicaid is the primary payer for long-term nursing home care. Medicare, on the other hand, is intended to cover costs related to short-term injuries and illnesses, along with preventive care, and covers up to 100 days of qualifying skilled nursing facility care per benefit period.[15]
Medicare Advantage may offer limited nonmedical services for home care, but these vary by plan. A supplemental Medigap policy alongside Original Medicare may help pay for some out-of-pocket costs associated with Medicare-covered care.[15]
Should I Apply for Medicare or Medicaid?
While it’s not required to apply for either Medicare or Medicaid, you should consider applying to both if you qualify. In many cases, people who qualify for Medicare may not meet Medicaid's income requirements. However, if you do qualify for both, dual enrollment could help cover out-of-pocket costs not included in your Medicare benefits, lowering your overall medical expenses.
Who Pays First?
If you’re dual-enrolled in Medicare and Medicaid, Medicare generally pays first for covered health services while Medicaid may help cover eligible Medicare out-of-pocket payments, such as your deductibles, copayments and coinsurance. Medicaid may also cover long-term care services and other benefits that Medicare doesn’t cover, including hearing, dental and vision services, depending on eligibility and state coverage rules.[16]
Medicare vs. Medicaid at a Glance
Below is the essential information you should know about Medicare versus Medicaid:
- Medicare helps with health costs for those who are 65 or older or meet other eligibility requirements, while Medicaid does the same for low-income families, those with certain disabilities, children and pregnant women.
- The federal government runs Medicare, while the federal and state governments jointly operate Medicaid.
- Original Medicare combines hospital insurance (Part A) and medical insurance (Part B).
- Private insurers offer Medicare Advantage (Part C) and prescription drug coverage (Part D), although Part D is often included in Part C plans.
- Eligibility for Medicaid varies by state, but it typically offers low- or no-cost coverage for medical services, long-term care, dental, vision and hearing.
- You can be dually enrolled in both Medicare and Medicaid, provided you meet the eligibility requirements for both programs.
- If you have dual enrollment, Medicare will generally be your primary payer, with Medicaid potentially helping cover eligible out-of-pocket payments like deductibles, copays and coinsurance.
- Insurance quotes /
- Medicare /
- Medicare Vs Medicaid
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Compare Medicare Plans Online Now.
More on Medicare
Looking for Medicare Plans?
Compare rates from dozens of companies in less than 3 minutes.