
What’s the Difference Between Medicare Advantage and Medicare Supplement (Medigap)?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Medicare Advantage covers the same services as Original Medicare and often includes additional benefits — such as vision and dental coverage — while Medicare Supplement Insurance covers a portion of your copays, coinsurance and/or deductibles if you’re on Original Medicare. Both types of plans are sold by private insurance companies, but you can’t have both at the same time.
Keep reading for more Medicare Advantage versus Medicare Supplement comparisons to help you decide which type of plan may be a better fit for you.
|
Key Takeaways
|
On This Page

What Are the Differences Between Medicare Advantage and Medicare Supplement?
What Is a Medicare Advantage Plan?
What Is Medicare Supplement Insurance?
Medicare Supplement vs. Medicare Advantage: Which Is Better for You?
Medicare Trial Period Explained
Medicare Advantage vs. Medicare Supplement at a Glance
How To Enroll in a Medicare Plan
Frequently Asked Questions

What Are the Differences Between Medicare Advantage and Medicare Supplement?
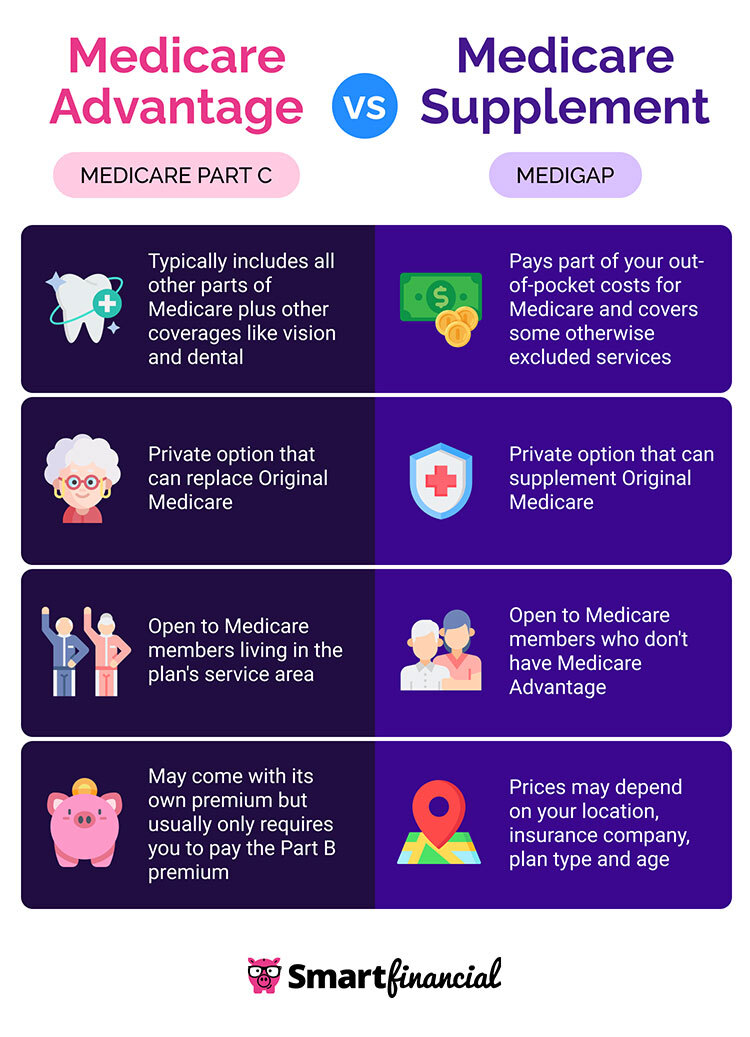
See the table and infographic below for an introduction to the differences between a Medicare Advantage plan and a Medicare Supplement plan:
|
Medicare Advantage |
Medicare Supplement |
|
|---|---|---|
|
Coverage |
Always includes Medicare Parts A and B, usually includes Part D and can include other coverages, such as vision and dental insurance |
Covers part of your out-of-pocket costs plus some services not covered by Original Medicare |
|
Program Administrator |
Private insurance companies |
Private insurance companies |
|
Provider Network |
Only providers that contract with your insurance company |
Every provider in the nation that accepts Medicare |
|
Open Enrollment Dates |
Jan. 1 to March 31 |
The first day of the month you’re at least 65 years old and have enrolled in Medicare Part B to six months afterward |
|
Prior Authorization Requirements |
Prior authorization may be necessary for some services — especially expensive ones |
Prior authorization generally isn’t required |
|
Travel Coverage |
Most plans don’t cover emergency international care, but some do |
Emergency international care is covered by most plans |
|
Prescription Drug Coverage |
Typically included automatically |
You need to purchase separate Medicare Part D coverage |
|
Total Annual Cost |
$0 to $60 per month on average — plus the cost of Medicare Part B, unless your plan covers it |
$30 to $630 per month — plus the cost of Original Medicare |
|
Out-of-Pocket Exposure |
You’ll generally have to pay a deductible to unlock coverage and copays or coinsurance when you receive care |
Some or all of your Medicare deductibles, copays and coinsurance are covered by the plan |
What Is a Medicare Advantage Plan?
Medicare Advantage — also known as Medicare Part C — is a type of Medicare health insurance plan that is administered by a private insurance company rather than the federal government. Part C typically includes all of the other parts of Medicare, making it a private option that can effectively replace Original Medicare for most health care services.
All Medicare Advantage plans cover inpatient hospital care (Part A) and outpatient medical services (Part B), and most of them also include prescription drug coverage (Part D).[1] In addition, many Medicare Advantage plans come with extra benefits that aren’t included in Original Medicare, such as vision, dental, hearing and even gym membership coverage.[2][3]
Keep in mind that each health insurance carrier has its own network of doctors, hospitals, and other health care providers that it contracts with to provide medical services to its policyholders. As a result, your Medicare Advantage plan may only cover in-network routine care — or it may require you to cover a higher percentage of the costs when you receive out-of-network care.[2]
Who Is Eligible for Medicare Advantage?
You can only join Medicare Part C if you already have Parts A and B — so you must meet the general Medicare eligibility requirements by being at least 65 years old or having a disability, permanent kidney failure or ALS.[4] To qualify for a given Medicare Advantage plan, you must also be a citizen or lawful resident of the United States living in that plan’s service area.[5]
How Much Does Medicare Advantage Cost?
The majority of Medicare Advantage plans don’t come with a premium, meaning most plan members are only required to pay their Part B premium. That said, some plans cover a portion of your Part B premium, resulting in less spending for more coverage in certain cases. Among plans that do require a separate Part C premium, the average cost of Medicare Advantage is just under $60 per month.[6]
Medicare Part B costs $202.90 to $689.90 per month, depending on your income. Meanwhile, most Medicare members get Part A at no cost, but those who don’t qualify for free coverage must pay $311 or $565 per month, depending on how long they or their spouse spent paying Medicare taxes.[7] Part C enrollees may have out-of-pocket costs when they receive care, depending on the type of service and whether they receive it from an in-network provider.[2]
How To Choose the Right Medicare Advantage Plan
Cost and coverage are two of the most important factors to consider when shopping for a Medicare Advantage plan. Before settling on a plan, pay attention to whether it comes with an additional premium for Part C or whether you would need to buy prescription drug coverage separately. Also, note whether the plan includes vision insurance, dental insurance or any other optional coverage types that you’re interested in and can afford.
Since private insurers partner with far fewer medical providers than the federal government, it’s important to check whether any doctors you currently see are in a Medicare Advantage plan’s network before committing to that plan. Keep in mind that, while Original Medicare generally doesn’t require you to receive prior authorization before it covers your health care, almost all Medicare Advantage plans require upfront approval for certain expensive services.[2][6]
Lastly, if you frequently travel internationally, you need to pay attention to the level of coverage your Medicare plan provides for out-of-country care. Original Medicare doesn’t cover medical services received outside of the United States in most cases. Most Part C plans also exclude coverage for international care, but some plans include extra travel health coverage, which may be worthwhile in case you have a medical emergency while vacationing overseas.[2]
What Is Medicare Supplement Insurance?
Medicare Supplement Insurance — also known as Medigap — helps fill in the gaps in Original Medicare by paying part of your share of the costs. In rare cases, a Medigap plan may also extend your coverage to pay for treatments that wouldn’t be covered at all under Original Medicare.[8] However, Medigap plans sold since 2005 haven’t included prescription drug coverage, so you’ll need to purchase Part D separately.[9]
Every type of Medigap plan covers your Part A coinsurance and some or all of your Part B coinsurance or copays. Meanwhile, most Medicare Supplement plans cover part or all of your Part A deductible. Medigap Plans C and F also cover your Part B deductible, but you aren’t allowed to purchase these plans anymore unless you qualified for Medicare before 2020.[10]
Other covered expenses may include excess charges above the Medicare-approved amount for a given service, the first three pints of blood for transfusions in a given year and out-of-pocket costs related to hospice or skilled nursing care.[10] Although Medigap is sold by private insurers, you can only buy it if you’re also on Original Medicare. As a result, Medigap covers services from every health care provider in the United States that accepts Medicare.[11]
Who Is Eligible for Medicare Supplement Insurance?
In general, you can purchase Medicare Supplement Insurance if you meet the eligibility criteria for Medicare and have enrolled in Parts A and B already. Since Medicare Supplement Insurance is designed to complement and fill the holes in Original Medicare coverage, you aren’t allowed to purchase a Medigap plan if you have Medicare Advantage instead.[9]
You’re only eligible for guaranteed-issue Medicare Supplement coverage during your Medigap open enrollment period, which is a six-month window beginning the first day of the month when you’re at least 65 years old and have signed up for Medicare Part B. If you shop for coverage outside of your open enrollment window, you’ll have to undergo medical underwriting and could face higher rates or be denied coverage, depending on the results of your medical exam.[12]
How Much Does Medicare Supplement Insurance Cost?
Medigap costs may range from around $30 to $630 per month, depending on where you live and the type of plan you select.[13] Your premiums may also depend on your age and your insurer’s rating method. Community-rated plans cost the same for all policyholders regardless of age, issue-age-rated plans are priced based on your age when you buy the policy and attained-age-rated plan costs depend on your current age and can go up over time.[14]
How To Choose the Right Medicare Supplement Plan
Like you would do with Medicare Advantage, you should primarily pay attention to price and depth of coverage when shopping for Medicare Supplement Insurance plans. Comparing Medigap quotes from different health insurance companies is generally straightforward, since every Medigap plan with the same letter name offers the same level of coverage.[11]
There are other benefits that may make Medigap appealing for you. For example, Medicare Supplement plans typically don’t require you to get prior authorization from your insurance carrier.[15] Also, Medigap is a good choice if you regularly travel, since most plans cover 80% of the costs for medically necessary emergency care outside of the United States after you pay a $250 annual deductible — up to a $50,000 lifetime limit.[8]
Medicare Supplement vs. Medicare Advantage: Which Is Better for You?
You need to weigh all the potential costs and benefits to figure out whether Medicare Advantage or Medicare Supplement Insurance would make the most sense for you. Review the following sections for a rundown of the types of Medicare members who may benefit from each type of plan.
Who Should Consider Medicare Advantage?
You may prefer Medicare Advantage coverage if any of the following apply to you:
- You want claims for prescription drugs and medical, dental and vision care to be covered under the same plan
- You live in the service area of a highly-rated Medicare Advantage plan
- You want the lowest possible premiums for a high level of coverage
- You don’t want to be on Original Medicare
- Your six-month Medigap open enrollment period has passed and you can’t afford a Medigap plan due to your health status
Who Should Consider Medigap?
On the other hand, Medigap coverage may make sense in these situations:
- You want to stay on Original Medicare while cutting out-of-pocket costs when possible
- You want broad coverage throughout the United States without having to worry about whether a certain provider is in your plan’s network
- You already have affordable dental and vision insurance plans and don’t need to bundle these coverages with your health insurance
- You want to receive medical care freely without first requesting prior authorization
- You want to be covered in case of a medical emergency while traveling in a foreign country
Medicare Trial Period Explained
Though joining Medicare Advantage requires you to drop Medigap, you may be able to return to your previous plan if you decide Part C isn’t a good fit during your trial right period. Specifically, first-time Medicare Advantage enrollees can switch back to Original Medicare within their first year of coverage. If they do so, they have the right to buy a Medigap plan without being denied due to medical underwriting — even if their Medigap open enrollment period has passed.[16]
Medicare Advantage vs. Medicare Supplement at a Glance
- While Medicare Advantage and Medicare Supplement Insurance are both administered by private health insurance providers, they differ in terms of their costs and the level of coverage they offer.
- Medicare Advantage bundles the other three parts of Medicare together into a single policy. In addition, it often adds extra coverages, such as hearing, vision and dental coverage.
- Medicare Supplement Insurance covers a portion of your out-of-pocket costs for Original Medicare, leading to lower deductibles, copays and coinsurance payments.
- Since you have to be on Original Medicare to qualify for Medicare Supplemental Insurance, you can’t have both Medicare Part C and Medigap at the same time.
- Medicare Part C may be a better option if you want to pay lower premiums relative to the amount of coverage your plan provides, while Medigap may be a better option if you want access to a broader network that includes most doctors and hospitals across the United States.
- Some Medicare Advantage plans cover international health care, but Medigap generally offers the most comprehensive Medicare coverage for overseas travel.
How To Enroll in a Medicare Plan
You can sign up for Medicare over the phone or through the Social Security Administration’s website. First-time enrollees should generally sign up during their initial enrollment period — a seven-month window that begins three months before the month they turn 65. Afterward, Medicare members can update their coverage during open enrollment from Oct. 15 to Dec. 7 or anytime a qualifying life event triggers a special enrollment period.[5]
Read below to see how you can sign up for Medigap or Medicare Advantage once you’ve enrolled in Parts A and B.
Medicare Supplement
You can type in your ZIP code and other personal information at Medicare.gov to find Medigap plans offered by insurance companies operating in your area. The website shows you starting rates for various plans and insurers’ contact information so you can reach out to sign up.[17] Remember, it’s best to shop for Medicare Supplemental Insurance within six months of obtaining Medicare Part B so you can skip the medical underwriting process.
Medicare Advantage
You can join a new Medicare Advantage plan or make changes to your coverage at any point during your first three months on Medicare. Afterward, you can only adjust your coverage or switch plans during the standard Medicare open enrollment period or Medicare Advantage open enrollment from Jan. 1 to March 31.[5] To find the right plan at the lowest possible price, compare quotes from at least three to five different insurance companies.
SmartFinancial makes comparison shopping for Medicare plans easy. Simply type in your ZIP code and answer a brief questionnaire about the kind of coverage you’re looking for, and we’ll connect you with an insurance agent who can help you find the best Medicare plan for your circumstances. Request free Medicare Advantage quotes in as little as a few minutes today!
- Insurance quotes /
- Medicare /
- Medicare Advantage Vs Medicare Supplement
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Compare Medicare Plans Online Now.
More on Medicare
Looking for Medicare Plans?
Compare rates from dozens of companies in less than 3 minutes.