
Does Homeowners Insurance Cover Fire Damage?
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Dan Marticio Dan MarticioDan Marticio is the content manager at SmartFinancial and has written 150+ articles across multiple insurance verticals.... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Standard homeowners insurance covers fire damage to your dwelling, personal property and outbuildings. While many causes of fire damage are covered under a standard homeowners policy, instances of intentional fires or fires due to negligence won’t be covered, and wildfire coverage may vary depending on the risk of a wildfire in your area.
Keep reading to learn when home insurance covers fire damage, the types of fire damage covered and how to help prevent a house fire from starting.
|
Key Takeaways
|


When Does Homeowners Insurance Cover Fire Damage?
Standard homeowners insurance covers fire damage when the cause is sudden and accidental. Most policies typically cover fire as a named peril, meaning your homeowners insurance will likely cover your home's repair or replacement costs if a fire or smoke damages its structure. In addition to your dwelling, policies will typically cover damages to outbuildings, like a shed or garage, alongside your personal property.
Standard homeowners insurance policies will typically cover fire damages even if they result from an event not covered under your policy. For instance, standard named and open peril homeowners policies won't cover earthquakes or mudslides, but your insurance will likely cover fire caused by your electrical wiring damaged by an earthquake.
When Won’t Home Insurance Cover Fire Damage?
Your homeowners insurance typically won’t cover fire damage caused by poor maintenance or negligence, such as a chimney fire that began due to a lack of cleaning out flammable materials. This is because insurance is meant to cover situations and accidents that are sudden and unexpected, and your insurance is unlikely to cover you for a situation that you could have avoided.
Similarly, a home that falls into disrepair or has poor construction may also result in a fire claim denial, as these may be viewed as unnecessarily increasing the risk of fire through negligence.[1] Likewise, an intentional act of fire damage likely won’t be covered. Your claim may be denied if the cause of the fire is found to be arson, as insurers could see this as potential fraud.[2] Additionally, fire damage caused by acts of war or nuclear hazards is also unlikely to be covered.[3]
While wildfire-based fire damage is typically covered under a homeowners insurance policy, some policies may limit or exclude coverage based on where you live. For example, California had over 9,000 wildfires in 2024, nearly 70% more than the next most frequent state.[4] So, some areas within the state may lack wildfire coverage in their standard home policy due to the significantly increased risk.[5]
Types of Fire Damage Covered by Homeowners Insurance
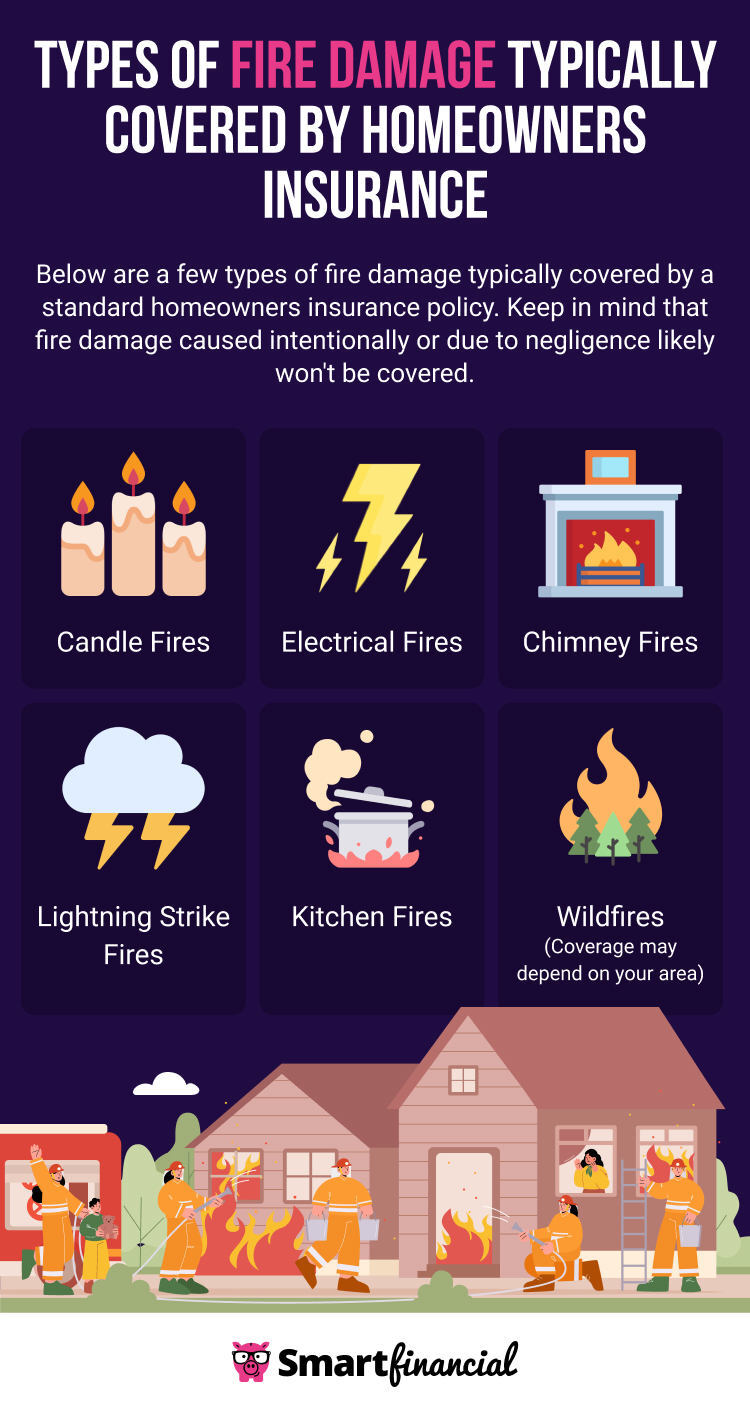
Your home insurance covers several types of blazes, including:
- Candle fires: If someone knocks over a candle in your home, your homeowners insurance typically covers the resulting fire damage.
- Electrical fires: These fires can occur due to power surges or short circuits in an electrical system.
- Chimney fires: A blocked chimney flute from an animal unexpectedly building a nest inside could lead to fire damage, although you may need to prove you perform regular maintenance on your chimney.
- Lightning strike fires: Homeowners insurance will cover fires that result from a lightning strike. For instance, lightning may strike a tree and cause it to fall, damaging your home and causing a fire.
- Kitchen fires: Homeowners insurance covers damage from kitchen fires and grease fires.
- Wildfires: Damage caused by a wildfire is typically covered by home insurance, but some policies may exclude or limit coverage depending on the area's wildfire risk.
Do I Need Additional Coverage for Fire Damage?
In general, you won’t need additional coverage for fire damage. However, as mentioned above, getting coverage for wildfires from your standard homeowners insurance may be more challenging, depending on where you live.
Some insurers require homeowners in wildfire-prone areas to buy a separate policy or endorsement for wildfire coverage. However, finding a carrier to insure a high-risk property can sometimes be challenging. Fortunately, some states offer last-resort insurance coverage, such as the California FAIR plan, which helps those in high-risk areas get temporary insurance coverage when they cannot get it from the standard marketplace.[6]
The ongoing Franklin Fire in Malibu, California, is a strong reminder of why wildfire insurance is so important. Over 20,000 residents have been evacuated, and several homes have been lost, showing just how unpredictable wildfires can be. Having the right insurance coverage can make a big difference in recovering from the damage. (If you’d like to help those affected, consider donating to local relief efforts or organizations.)[7]
How To Enhance Your Home Insurance for Fire Risks
Many insurers apply a sublimit on certain valuables, such as jewelry, antiques or artwork, meaning you will only be reimbursed at a certain amount even if the item is worth much more. Consider scheduling your high-value personal property, which can help increase coverage beyond the policy’s standard limits if it is damaged in a fire or another covered peril.

If you aren’t sure if your dwelling coverage limits are enough to cover your home if it is burned down in a house fire, it may be worth purchasing extended or guaranteed replacement coverage to increase these limits or cover the full cost of rebuilding, respectively.
What To Do After a House Fire
After a house fire, you’ll want to obtain the fire report, which is prepared by your local fire department and indicates when the fire happened, when authorities were notified, photos of the damages and emergency personnel involved.[8] Your insurer may also require a fire investigation report prepared by independent investigators, which details how the fire progressed and what possibly caused it, including whether it was due to negligence.[9] Both of these reports may be required when making an insurance claim.
Notify local law enforcement if your home is rendered vacant due to needing repairs or is unlivable due to fire damage, such as if doors were burned off or windows shattered, as it could be vulnerable to vandalism or theft. Avoid returning home until it’s safe, and possibly wait for confirmation from the fire department to avoid accidentally injuring yourself.
Ensure you hold on to receipts for hotels and meals you had to eat outside the home for your homeowners insurance additional living expenses (ALE) coverage if your home was rendered unlivable due to fire damage.
Tips for Fire Prevention at Home
While your homeowners insurance will often cover you for damages and additional living expenses in the wake of a destructive house fire, it is far better to prevent a fire from occurring in the first place. Here are a few tips to help prevent fire damage in your home:
- Keep flammable materials, like paint thinners or gasoline, stored in well-ventilated areas that are unlikely to catch fire or easily spread to other parts of your home if they do, like an outdoor shed.
- Install smoke alarms on every level of your home and in each bedroom, ensuring you check the batteries and dust them at least once a year.[[10]
- Only use candles and other open flames, such as a fireplace, when you’re in the room and can monitor them.
- Use safe techniques when cooking on the stove, and always monitor the stovetop, turning it off if you need to leave it unsupervised.
- Keep anything flammable at least three feet away from heaters, furnaces or fireplaces and don’t fall asleep or leave your home while they are in use.
- Clean your chimney professionally at least once a year.[10]
- Replace your roof with fire-resistant materials and install fire-resistant windows.
- Insurance quotes /
- Home /
- Does Homeowners Insurance Cover Fires
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Home Insurance Quote Online Now.
More on Home Insurance
Looking for Home Insurance?
Compare rates from dozens of companies in less than 3 minutes.