

Blizzards and Homeowners Insurance: Everything You Need To Know
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Blizzards can be destructive, with heavy snowfall, low visibility and high winds. Fortunately, homeowners insurance typically covers many of the damages they cause, as well as those from other winter storms, such as roof damage and fallen trees.
Read on to learn when home insurance covers blizzard damage and how to make an insurance claim for it.
|
Key Takeaways
|


What Type of Blizzard Damage Is Covered by Home Insurance?
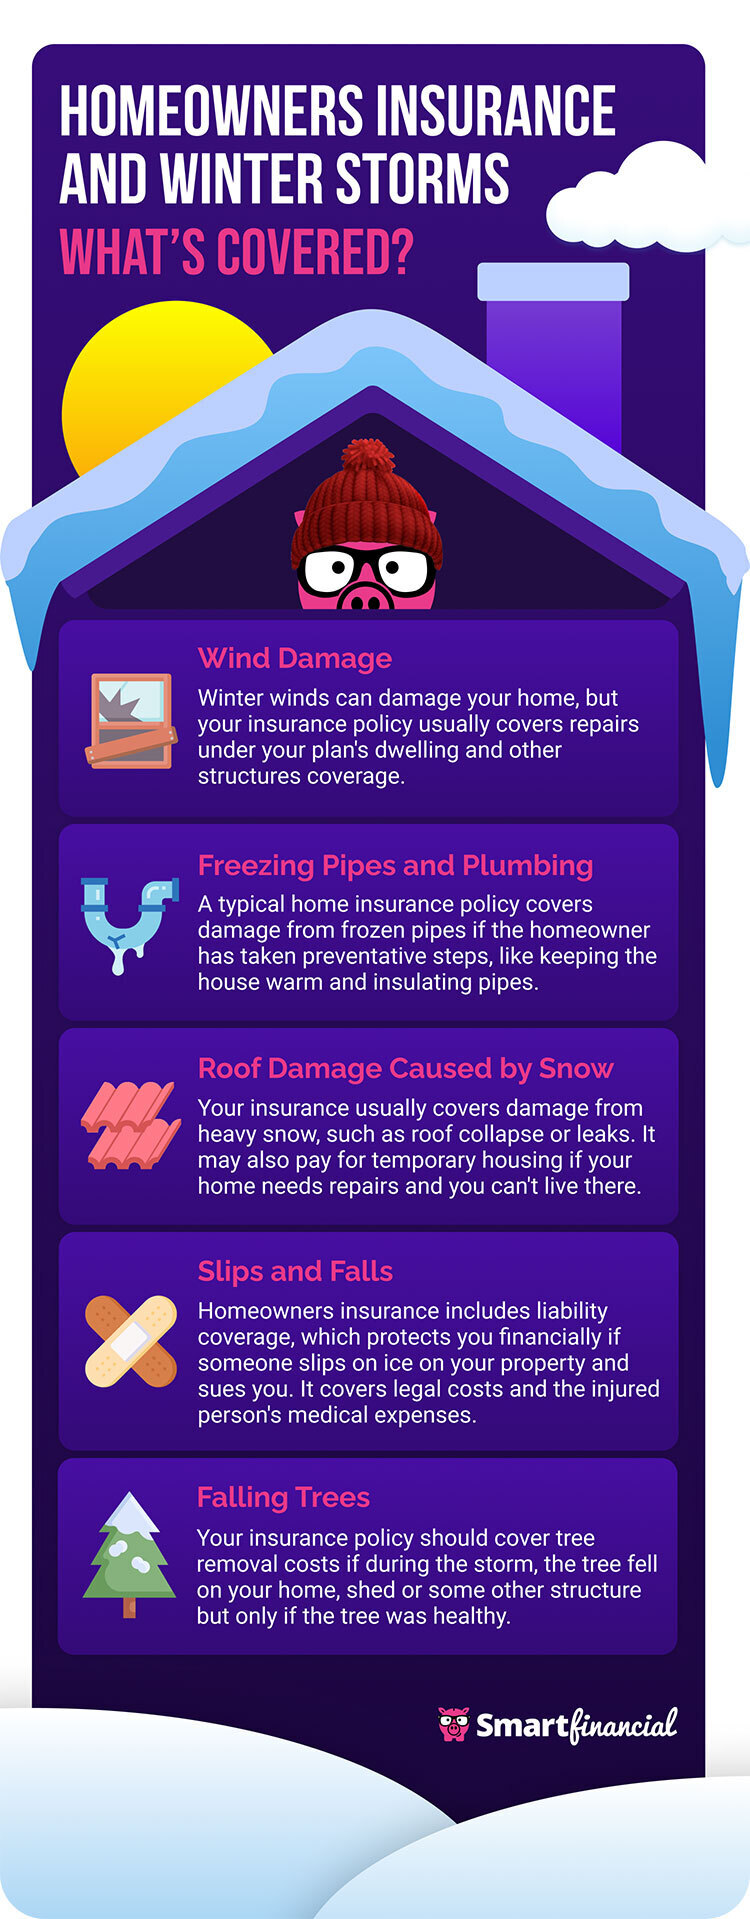
Homeowners insurance typically covers damage caused by heavy winds and snow from blizzards and other winter storms. Below, we’ll break down some of the common types of damage your home insurance may cover after a blizzard.
Wind Damage
To qualify as a blizzard, a winter storm must reach wind speeds of at least 35 miles per hour.[1] Winds at this speed can cause lawn furniture, branches and other debris to fly through the air and potentially damage your home.[2] However, blizzards can reach wind speeds much higher, such as a 2024 storm in the Sierra Nevada, an area extending through portions of California and Nevada, that featured blizzard winds of 145 miles per hour.[3]
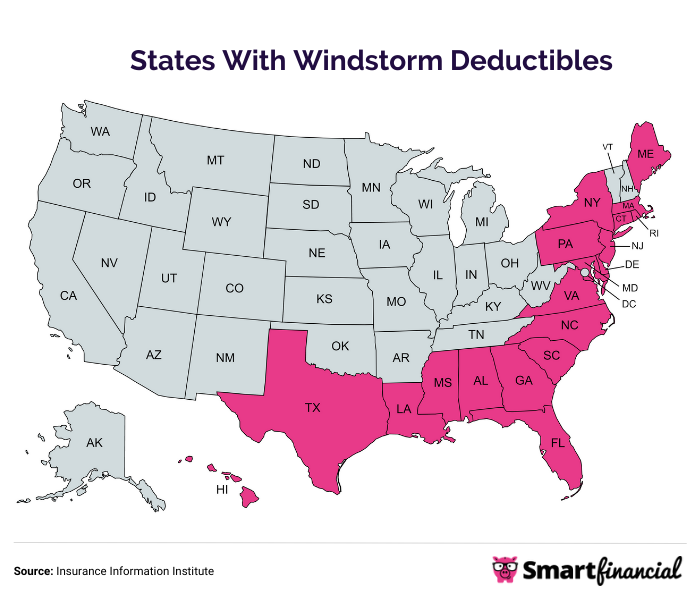
Damage from wind can include torn-off shingles and broken windows from flying debris, but this damage is typically covered under a standard homeowners policy as a common peril. In fact, 42.5% of all home insurance claims were due to property damage caused by wind and hail in 2023.[4] However, ensure you review your policy, as you may need to cover a separate windstorm deductible before you receive a claim settlement for wind damage, depending on your state.[5]
Frozen Pipes and Plumbing
A standard homeowners insurance policy typically covers damage from frozen or burst pipes caused by the freezing blizzard conditions. About 23% of homeowners insurance claims in 2023 were due to water damage and freezing.[4] Additionally, if a burst pipe soaks your personal belongings, such as furniture, they’ll generally be covered under your policy’s personal property coverage.
Roof Damage Caused by Snow
Blizzards can produce significant snowfall, with some dropping two to six inches per hour, which can damage your roof due to the added weight.[6] Most roofs can support the weight of around four feet of fresh, unpacked snow, so blizzards with high levels of snowfall that rage for multiple hours could lead to roof collapse or cracks resulting in water leakage into your home.[7] Damage to your home’s structure, including the roof and interior, and your personal belongings inside, is typically covered under a standard homeowners insurance policy for snow damage.
Slips and Falls Due to Icy Conditions
The combination of low visibility, high winds and icy snow can make it difficult to walk outside, potentially leading to a guest slipping and falling on your property. The liability coverage portion of your homeowners policy can help cover expenses from their medical bills and cover your legal fees if you’re sued. To avoid a potential lawsuit and make your property safer, ensure you shovel and remove snow from walkways after a blizzard has passed to help prevent slip-and-fall accidents.
Fallen Trees
Blizzards with strong winds can topple trees, and small trees may be uprooted at wind speeds of 55 miles per hour or higher.[8] A fallen tree can land on your home, garage or detached structure, causing significant damage. However, your policy will typically cover the cost of repairing the property damage, provided the tree was healthy when it was uprooted.[9]
Many homeowners insurance policies will cover the cost of removing a fallen tree, but typically only up to $500 to $1,000, depending on the specific policy and insurance company. This coverage only applies if the tree fell and damaged your property – a tree that simply fell in your yard is unlikely to qualify for removal reimbursement. However, some insurance companies may cover an uprooted tree that didn’t damage your property if it falls and blocks a driveway or access ramp.[9]
Home insurance policies may cover the cost of replacing a fallen tree or shrub due to a covered peril, but typically only up to 5% of your dwelling coverage for any single tree.[9]
What Isn't Covered?
Damage caused by flooding from melting snow and ice after a blizzard is typically not covered by standard homeowners insurance policies. You’ll likely need to purchase flood insurance as a separate policy to be covered for this scenario, either through the National Flood Insurance Program (NFIP) or a private insurer. Excess water from melting blizzard snow could also result in mold, which likely won’t be covered for removal by your homeowners policy.[10]
Generally, homeowners insurance won’t cover damage due to negligence, so issues caused by long-term deterioration likely won’t be covered. For example, a tree that fell but was dead before the blizzard likely wouldn’t be covered. Additionally, if you did not insulate your pipes or take other precautions to prevent freezing, you may not be covered for frozen plumbing.
Not all homeowners policies will cover damage from blizzards. For example, an HO-1 policy is more limited in coverage and excludes reimbursement for damage caused by falling trees, snow weight, and frozen pipes.[10] While HO-1 policies may be a cheaper alternative to other, more substantial policies, they may not be worth the risk if you live in an area with frequent blizzards and other winter storms.[11]
Types of Winter Storms Commonly Covered by Homeowners Insurance
Blizzards aren’t the only winter storms commonly covered by homeowners insurance; many produce similar weather conditions and resulting damage. Some winter storms that are often covered by home insurance include:[12][13][14]
- Blizzards
- Snowstorms
- Ice storms
- Lake-effect storms
- Bomb cyclones
- Nor’easters
- Thundersnow
What Can I Do To Protect My Home From Blizzard Damage?
While blizzards can damage your home in various ways, you can reduce potential damage and increase your odds of home insurance claim approval by being proactive ahead of an oncoming winter storm. Below are a few tips to consider to help protect your home from blizzard damage:
- Install storm windows and doors to help protect against flying debris from high winds.
- Install insulation in your attic, crawl spaces and basement to help your home retain heat and prevent ice dams.
- Place salt on your roof and gutters before a blizzard strikes to prevent snow from accumulating.
- Insulate your pipes to help prevent them from freezing. Take special care with any plumbing that runs along exterior walls or through unheated portions of your home, as these are more likely to freeze in cold weather.
- Trim loose branches from trees on your property to reduce the odds of them snapping off and flying through a window or into your siding.
- Check any trees or shrubbery for signs of poor health, decay or rot. Consider preemptively removing trees to avoid potential damage from falling if they’re not recoverable or already dead.
- Secure any outdoor furniture or loose items that could be thrown as projectiles in a blizzard’s high winds.
- If you’ve already had significant snowfall, try to clean your roof before another blizzard arrives to prevent too much weight from accumulating on your roof and causing a collapse.
- Shovel your walkways safely after the blizzard has passed to reduce the risk of slip-and-fall accidents.
- Review your home insurance policy to check for any peril exclusions that include possible blizzard damage. Shop around for an alternative policy or endorsements to cover any gaps.
- Take pictures and document your home before a blizzard as evidence for your insurer of the damage caused after the blizzard if you need to make a claim.
How To Document Blizzard Damage
After the blizzard has passed, you’ll want to check your home for damage and document it for use in a claim. Review your home for any potential water leaks that could have come from your roof or a burst pipe. Check your water faucets to ensure the pressure is normal – if you only get a trickle of water or nothing comes out when you turn on the faucet, it may mean you have a burst pipe and you should turn off your water supply until a professional can check it.[15]
Check your home’s siding, detached structures, windows and garage for any damage caused by debris. You should also check your roof and, if you have one, your chimney for any damage, using a professional if you’re not comfortable safely scaling your roof. If you notice anything unusual, take pictures of the damage from various angles, which you can submit when you make a claim.
How To File a Home Insurance Claim for Blizzard Damage
After documenting the damage from a blizzard, file a home insurance claim as soon as possible. Some insurance companies may have limitations on how long you have to file a claim after the blizzard has occurred. You’ll typically schedule a time for a claims adjuster to visit your home and review the damage to ensure it matches up with your claim description.
After meeting with the claims adjuster and performing any emergency repairs necessary to prevent more damage from occurring, your insurance company will review the claim and provide a settlement amount. You can then accept the settlement or dispute the claim with the help of a public claims adjuster or independently.
- Insurance quotes /
- Home /
- Homeowners Insurance Blizzard Damage
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Home Insurance Quote Online Now.
More on Home Insurance

Looking for Home Insurance?
Compare rates from dozens of companies in less than 3 minutes.