
How To Create a Home Inventory List for Insurance: 5-Step Guide
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
By creating a home inventory, you can determine whether you have enough personal property coverage and support your claim after a covered peril damages your belongings. Your home inventory list should record basic information about your valuable items, such as what they are, when you bought them and how much they are worth.
Review our guide for more information on why you should complete a home inventory and what options you may have for setting up a home inventory system.
|
Key Takeaways
|


How Do You Create a Home Inventory List?
Read below for the steps you need to follow to create your homeowners insurance inventory list.
1. Determine What You Want To Include
In general, your home inventory should include every item in your home that you would want your insurance company to replace in the event of a destructive peril. For example, you may want to document your electronics, furniture, appliances, equipment and collectibles. In addition, it’s a good idea to add your most valuable shoes and apparel to your home inventory list.
That said, it may be needlessly time-consuming to document every single item you own. For example, you may not need to record cheap items that you could easily replace out of pocket, such as hand-me-down T-shirts or worn-out sneakers. Also, you won’t need to list possessions that aren’t covered by your homeowners insurance, like cars and animals.[1]
2. Choose Your Method
There are various options for creating a home inventory, and you should consider the pros and cons of each before settling on a method. For example, an online spreadsheet allows you to comprehensively record details about your belongings and store that information digitally. Conversely, writing out your inventory with a pen and paper may be simpler if you aren’t tech-savvy, but you may not be able to include pictures or update your inventory easily.
If you want to finish your inventory quickly, you could simply film a walk-through of your house that includes video footage of all your valuables — keep in mind, though, that this option may leave you with less comprehensive information than a written record. Additionally, you could use a home inventory app. For example, Magic Home Inventory and Memento Database let you upload and organize photos of and information about your possessions for free.[2][3]
3. Start Itemizing Your Belongings
Once you’ve identified which items to include, you can start recording relevant information, including a summary of what each item is, when you purchased it and how much you paid for it. You should also include a picture of the item, mention its serial number — if applicable — and note the quantity if you own multiple of the same item. For valuables, consider adding recent appraisals to ensure your inventory accurately reflects how much each item is currently worth.[4]
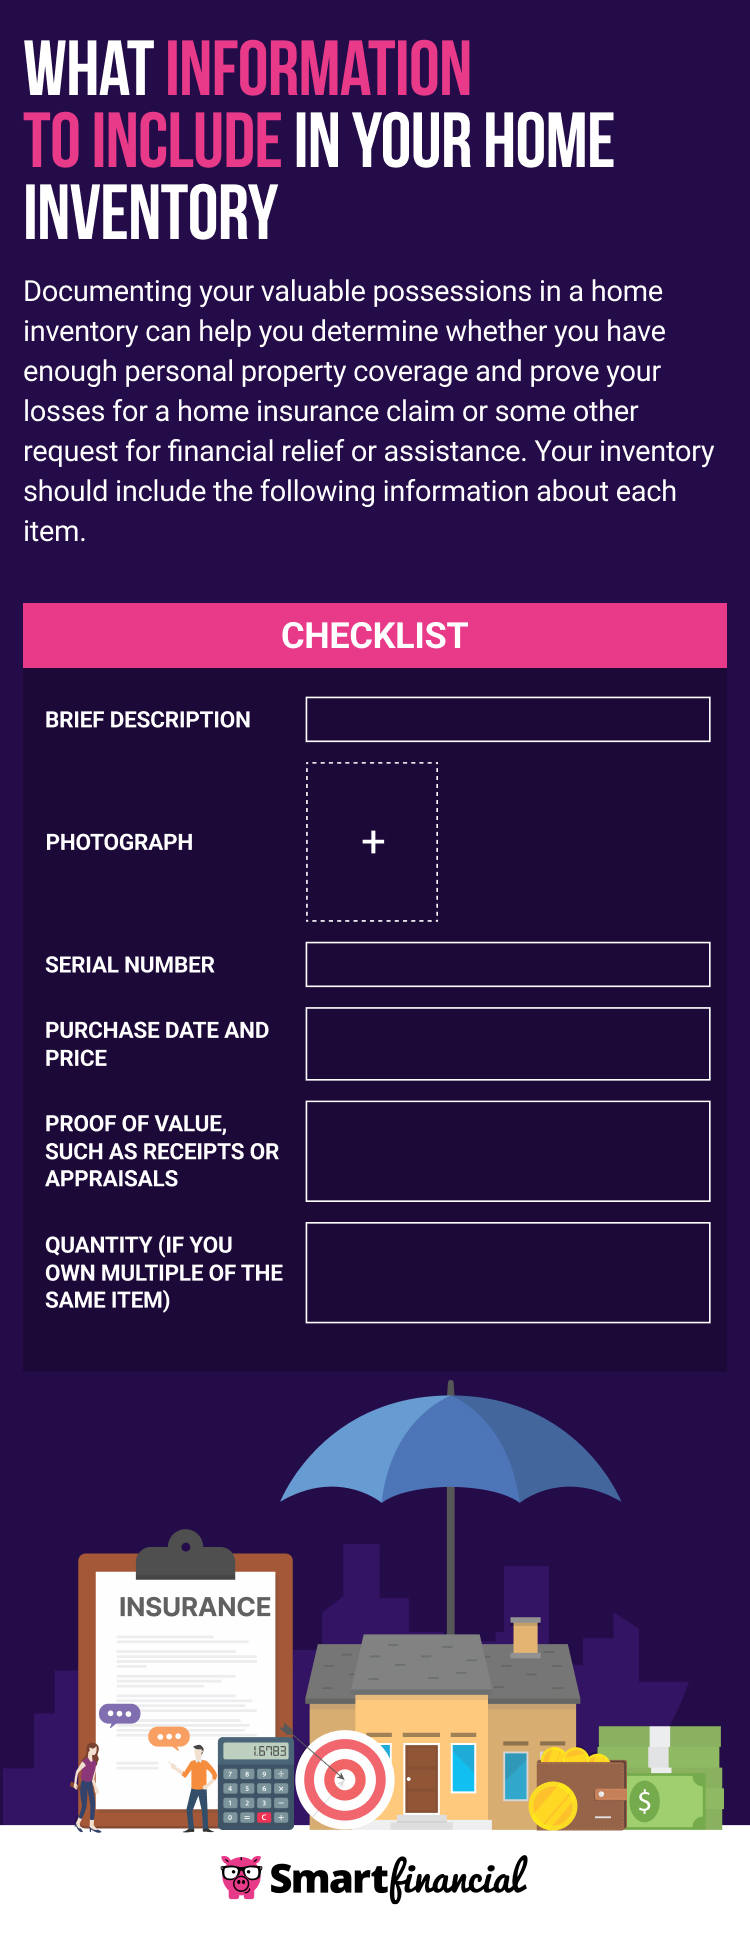
While cataloging all of your belongings may be a daunting task, it can be helpful to start small. For example, you could begin with your most recent purchases before revisiting older items, or you could start with the items in a single room and then work your way throughout your home. Also, remember that homeowners insurance covers your belongings outside of your home, so you need to document items located in a storage facility or your child’s college dorm room.[4]
4. Store Your List Safely
After completing your inventory list, it’s important to store it securely so it isn’t destroyed in the event of a peril that severely damages your home. This is fairly straightforward if you use an app or spreadsheet that stores data in the cloud, since you can access these lists through any device with an internet connection. If you opt for a physical copy, consider storing it in a fireproof or waterproof safe or somewhere outside of your home — like a safe deposit box at a bank.
5. Update Your List Regularly
Your home inventory is only useful if it’s accurate, so you will likely need to update it frequently. For example, you should add new items whenever you make major purchases and edit the information listed for valuable items that you periodically have appraised. In general, it’s recommended that you review your home inventory and make necessary updates at least once per year.[5]
Why Is It Important To Have a Home Inventory List for Insurance?
An up-to-date home inventory can help you choose appropriate insurance coverage limits and substantiate your losses after a covered peril. For example, most home insurance policies set your personal property coverage limit between 50% and 70% of your dwelling coverage limit.[6] However, if you have $800,000 worth of dwelling coverage but your home inventory reveals that you have $600,000 worth of belongings, you may need to raise your coverage limit.
A home inventory can also expedite the home insurance claims process because it can help you show which items were destroyed by a covered peril and how much your insurance company should reimburse you for them. Similarly, the list can help you prove what items were destroyed if you need to do so when applying for disaster aid or tax relief following a catastrophic loss.[7]
What Information Does Your Insurance Company Need When You File a Claim?
Be prepared to share the following information anytime you file a homeowners insurance claim:[8]
- Your policy number or other information your insurer can use to identify your policy, such as your name, address and phone number
- Summary of the damaging peril and the extent of your losses
- Contact information for where you are temporarily staying if the peril has rendered your home uninhabitable
- Evidence to support your claim, including photos or videos, home inventories and repair estimates
- Insurance quotes /
- Home /
- Home Inventory Homeowners Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Home Insurance Quote Online Now.
More on Home Insurance
Looking for Home Insurance?
Compare rates from dozens of companies in less than 3 minutes.