

Collectibles Insurance: Are My Valuables Covered at Home?
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Collectibles insurance can protect your high-value household items from various perils, such as accidental breakage, fire or theft. While your homeowners or renters insurance typically protects against personal property losses to a degree, many policies won’t give you the needed coverage for the full value of your collectibles.
If you have valuables that need extra protection, keep reading to see what collectibles insurance can do for you and how to get it.
|
Key Takeaways
|


What Is Collectibles Insurance?
Collectibles insurance provides financial protection for your collectibles in the event of a covered peril, such as theft, accidental breakage, flooding, fire or other natural disasters.[1] Renters and homeowners insurance policies typically include personal property coverage, but they may feature limits lower than what your collectibles are worth. For example, some policies may only cover up to $1,000 to $1,500 per item, which may not cover your rare No. 1 Issue comic book or high-value fine artwork worth several thousand dollars.[2]
Collectibles Insurance Types
Coverage for collectibles insurance can come in the form of a separate, stand-alone collectibles policy or as an additional schedule or rider to your current homeowners insurance policy. Below, we’ll break down the differences.
Scheduled Property Coverage
This is optional coverage you can add to an existing homeowners policy through an endorsement, also called a rider, that provides more comprehensive coverage than a basic homeowners plan. Items that could be covered include:
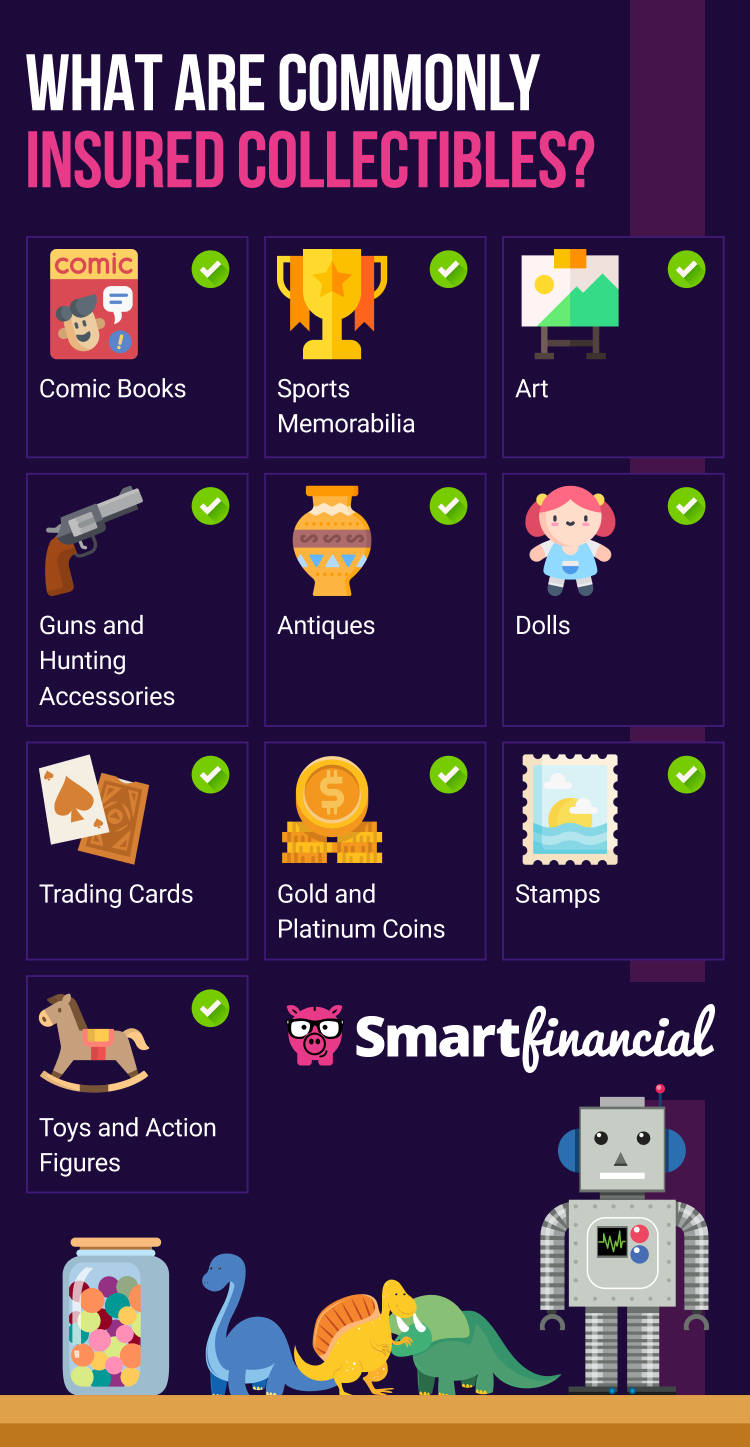
- Antiques
- Art
- Coin and bullion collections
- Firearms
- Furs
- Jewelry
- Musical instruments
- Stamp collections
To get a rider for your collectibles, you will typically need to provide your carrier with an appraisal of the item or a recent receipt. Benefits of getting a rider include:[3]
- Broader protection: A rider can provide coverage for events your homeowners insurance may not typically handle. For example, losing your wedding ring down a sink drain.
- Replacement cost value coverage: Most homeowners and renters policies cover personal property losses for their actual cash value (ACV), which accounts for depreciation and may mean your claim is less than what you paid for it. Riders are typically covered for an item's replacement cost value (RCV), which reflects what an equivalent item purchased today might cost.
- No deductible: It is possible to get a rider with either a low deductible or no deductible.
Be sure to get appraisals for your insured belongings, as their value can rise or fall over time, potentially changing your rates.
Stand-Alone Collectibles Insurance
This is a separate insurance policy you can buy from a carrier that specializes in collectibles. Types of items covered may include:[4]
|
Advertising collectibles |
Militaria |
|
Antique radios and phonographs |
Movie props |
|
Antique tools |
Musical instruments |
|
Art (comics, animation, lithographs, prints) |
Native American items, including arrowheads |
|
Teddy bears |
Paper and ephemera |
|
Books and manuscripts |
Petroliana |
|
Club and organization memorabilia |
Political memorabilia |
|
Coin-operated devices |
Records and CDs |
|
Coins and bullion |
Sports cards and memorabilia |
|
Comic books |
Stamps |
|
Dolls |
Toys and action figures |
|
Entertainment memorabilia |
Trains, including layouts |
|
Fine art |
Video games |
|
Furniture |
Vintage clothing |
|
Glass and pottery |
Vintage sewing and textiles |
|
Guns, knives, other arms and accessories |
Western Americana |
|
Hunting and fishing accessories |
Writing instruments |
|
Limited edition items |
Zippo lighters |
A separate collectibles policy can also help protect your belongings if they are away from home. Coverage may include:[4]
- Transit coverage: Helps protect items while traveling, up to policy limits.
- Show or display coverage: Collectibles on display are protected while being shown and while traveling to and from events.
- Storage Facilities: Items that are stored at public, off-site facilities will be covered. An additional premium may apply.
How To Insure a Collection at Home
There are several things you’ll have to do in order to cover your collectibles.
Step 1: Create an Inventory
The first thing you'll want to do is create an inventory of all the belongings you wish to insure. Make sure you find any documentation that may help establish the value of your property. This could be receipts or something known as provenance, a document that tells the history of the item in question. Information can include the item's origin, historical value or previous owner or owners. When creating your inventory, ensure that you:
- Gather as much detail as possible for each item you wish to insure.
- Take pictures of the items you want to insure.
- Gather any receipts that can help establish value.
- Keep the documentation, including any receipts and photos, in a safe place such as a personal safe or hard drive.
Step 2: Get Your Items Appraised
An appraisal of your collectibles will help you get an accurate value, enabling you to get the right amount of insurance to protect your valuables. Most insurance companies typically want recent appraisals from within the last five years to ensure their assessment is up to date, so a 15-year-old receipt for your favorite baseball card may not be enough.[5]
Step 3: Shop for Insurance
Look for an insurance company that offers the best protection. Talk to your current insurance company about buying separate riders for your collectibles and adding them to your homeowners policy to increase limits and broaden coverage. Another option is to find a carrier that specializes in insuring collector items. You’ll also need to decide on a policy with an agreed value or a stated value for your items.
- Agreed value: The value of the insured item is agreed upon by you and your carrier.
- Stated value: The value of the item is determined by you. However, your provider may not pay the full amount, as the payout is typically determined by the market value at the time of loss.
Talk to your insurance agent about how your plan handles inflation, as this could affect your collection’s value down the line.
Step 4: Reappraise Your Collection
The value of your collection can change over time, which means you should regularly appraise your belongings. Changes in the value can cause your insurance to adjust, either higher or lower. Additionally, be sure to store your items in a safe place to help maintain their value.
How Much Does Collectibles Insurance Cost?
The cost of collectibles insurance can vary widely depending on the insurance company, the value of the item, your coverage limits and deductible choice. For example, protecting your jewelry could cost 1% to 2% of its value, depending on the company.[6] It's also possible there's no deductible for a plan, depending on the insurer, although this could lead to higher costs.
Which Companies Cover Collectibles?
There are many insurance companies that provide coverage for your collectibles either through a separate policy or through a rider on your existing plan. These companies include:
- Allstate[1]
- American Family[7]
- Chubb[8]
- Collectibles Insurance Services[4]
- Liberty Mutual[5]
- Nationwide[9]
- State Farm[10]
- Travelers[2]
- USAA[11]
- Insurance quotes /
- Home /
- Collectibles Insurance
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Home Insurance Quote Online Now.
More on Home Insurance

Looking for Home Insurance?
Compare rates from dozens of companies in less than 3 minutes.