

Which Types of Commercial Insurance Does My Business Need?
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Companies often rely on a number of different types of business insurance to protect themselves from potential lawsuits or receive reimbursement for covered property damage claims. Not all types of commercial insurance are necessary for each company, so it’s critical to understand what options you may need to safeguard your business.
Keep reading to learn more about the different types of commercial insurance and what businesses may need them.
|
Key Takeaways
|


1. General Liability Insurance
General liability insurance helps protect your business from financial losses when you’re liable for a customer or client’s injuries or property damage. For example, if a customer slips and falls on a patch of recently mopped floor in your retail store, breaking their tailbone and shattering their cell phone, then general liability insurance would cover the cost of medical treatments and phone repairs. It can also cover potential legal expenses if the customer sues your business.
Additionally, general liability insurance coverage protects against personal and advertising injury and copyright infringement claims. For example, this coverage could take care of your legal expenses if you were sued for defaming another business or individual or infringing on their copyrights.
While there typically aren’t state laws requiring general liability insurance, it may be necessary if you work with other businesses or organizations. For example, if your business signs a contract, leases office space or applies for a professional license, you might be required to have this coverage.[1] Businesses in nearly every industry can benefit from this coverage, including real estate, janitorial, landscaping, retail and consulting
2. Commercial Property Insurance
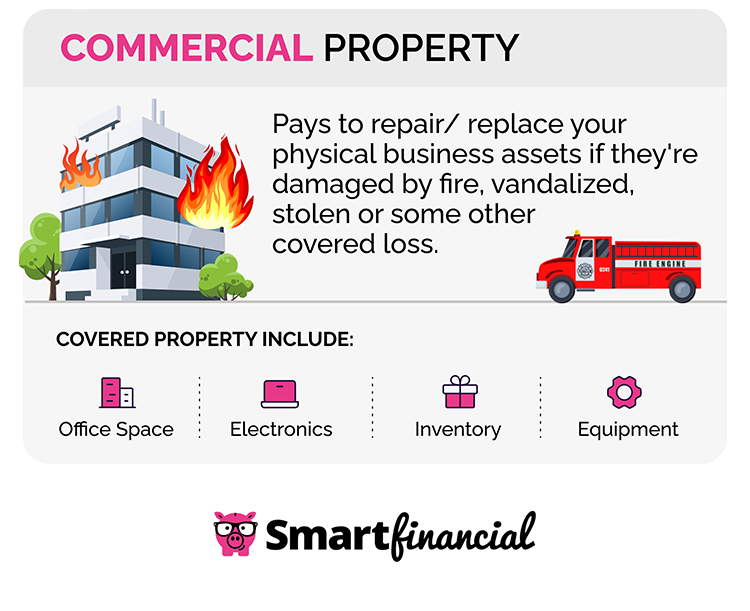
Commercial property insurance covers you if a sudden covered peril damages or destroys your company’s physical assets, including equipment, inventory, furniture and the commercial building itself. For example, if someone broke into your store and vandalized your inventory and furniture, this commercial insurance policy would cover repairing or replacing the damaged items.
Businesses that benefit from commercial property insurance include any businesses that wants to protect the physical assets they own, such as expensive construction equipment for contractors or commercial dishwashers for food vendors.
Although commercial property insurance isn’t required by law, landlords may require it as part of a rental or lease agreement.[2] Certain types of loans, such as loans from the Small Business Administration, may also require this coverage.[3]
3. Workers’ Compensation Insurance
Workers’ compensation insurance helps cover medical bills, lost wages, death benefits and other costs when an employee is injured, gets sick or dies on the job, regardless of who is at fault.[4] For example, suppose an employee injures their back while lifting a box incorrectly at a warehouse. In that case, workers’ compensation will typically cover the costs of their medical bills and lost income while recovering.
While each state has different regulations, businesses with more than one employee will generally need to have workers’ compensation insurance. Texas, Wyoming and South Dakota are the only states that exempt most businesses from this requirement.[5]
4. Business Owners Policy (BOP)
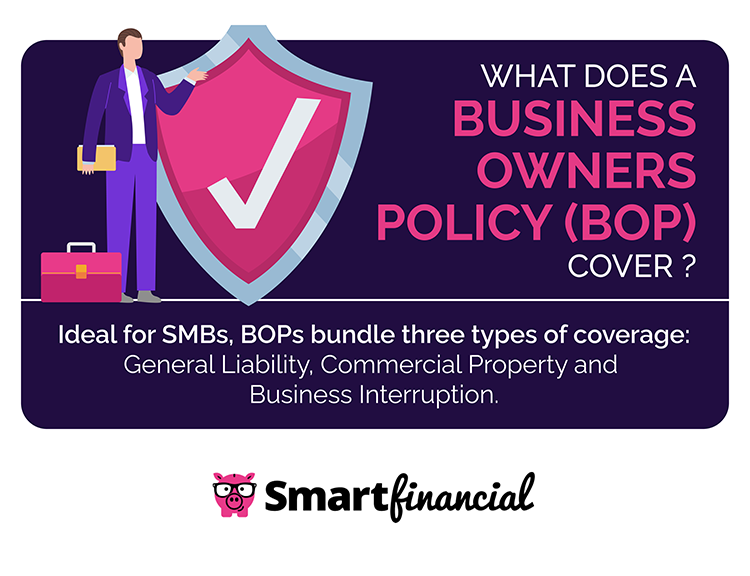
A business owners policy (BOP) is a commercial insurance bundle combining multiple different insurance types into one policy. In addition to general liability and commercial property insurance, a BOP includes business interruption insurance, which can cover lost revenue, payroll, relocation costs and other expenses if a covered peril forces you to close temporarily. Some BOPs may also allow you to add other coverage types as endorsements.[6]
While BOPs are not required by law, they can help businesses meet certain requirements with other businesses, lenders and landlords, such as potentially needing business interruption coverage as part of an agreement if you’re renting a commercial property. BOPs are typically more cost-efficient than getting each included policy piecemeal but are only available to smaller, lower-risk businesses.[7]
5. Commercial Auto Insurance
Commercial auto insurance typically covers physical damage or injuries caused by you or an employee while driving a commercial vehicle. If you use a vehicle as part of your business, including driving between jobsites, delivering products or ferrying customers or clients, you’ll want commercial auto insurance to protect your business from potential liability if there’s an accident.
Businesses that use commercial vehicles will need commercial auto coverage to meet the minimum auto insurance requirements mandated in every state except New Hampshire.[8] Depending on where your business is located, you may need to purchase additional coverage, including uninsured and underinsured motorist coverage.[9]
6. Commercial Umbrella Insurance
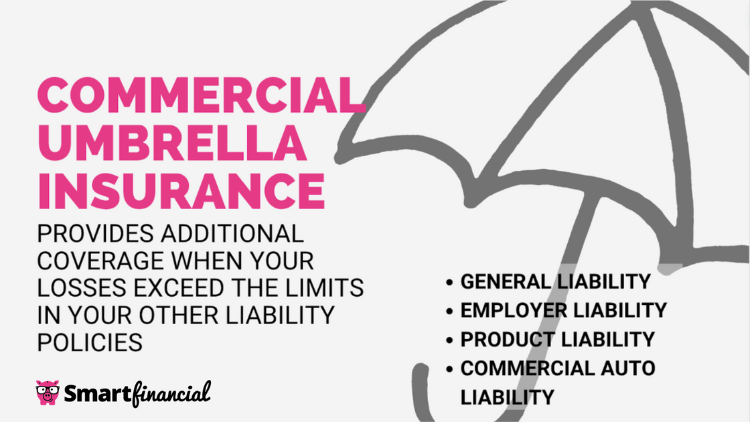
Commercial umbrella insurance covers liability claims after you’ve already exceeded the limits of other commercial liability policies. This can include liabilities like personal injury, property damage and advertising injury. For example, if your business is sued for a $1.5 million construction accident and your general liability policy only covers you up to $1 million, then commercial umbrella insurance could cover the remaining amount of the settlement payment.
Businesses with the potential for high liability exposure, such as construction, property management, and manufacturing companies, should consider commercial umbrella insurance to help protect themselves.
7. Cyber Insurance
Cyber insurance helps cover your business if it is hit by a cyber attack, including a data breach. For example, if a hacker breaks into your e-commerce store’s database and steals confidential customer data, like banking information and credit card data, this insurance can help cover the costs of investigating how the breach occurred, improving your cyber security and reaching legal settlements with affected customers.
Cyber insurance isn’t a requirement for businesses, but many that utilize the internet or databases may want to consider purchasing this coverage. For example, IT industry professionals, hospitals and other health care businesses, law firms, banks and financial consultants that regularly store confidential customer, client and company data could benefit from this protection.
8. Key Person Insurance
Key person insurance is a form of commercial life insurance that can help protect your business in case a critical employee or executive passes away. The insurance payout for key person insurance can be used to reimburse the company for lost income, help repay debts, pay for the replacement hiring process or help close the company. Some policies may also allow you to add an endorsement to this policy to cover the key person becoming too disabled to work.
Companies that have indispensable employees, such as specialized engineers or critical product development leads, may want to consider key person insurance to cover the company’s losses in the event that the employee unexpectedly dies. While it’s not required by law, some businesses may need to get key person insurance to meet the requirements of a lender’s financing agreement to protect their investments.[10]
9. D&O Insurance
Directors and officers (D&O) liability insurance helps protect your managers, board members or other corporate leaders if they are sued for alleged misconduct or poor management by covering the cost of associated legal fees. For example, it could cover your company’s legal expenses if an executive is sued by a supplier for requesting an increase in production and then suddenly switching to a different supplier for cheaper rates, essentially misrepresenting an agreement between the two businesses.
D&O insurance can be beneficial for businesses and nonprofits that want to protect their executives against alleged wrongdoing lawsuits, such as retailers, financial institutions and other companies that may work with investors. While D&O insurance isn’t a requirement for businesses to have, it can offer peace of mind and may help you recruit talented executives who are enticed by this protection.
- Insurance quotes /
- Commercial /
- Types Of Commercial Insurance Which Does Your Business Need
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Commercial Insurance Quote.
More on Commercial Insurance

Looking for Commercial Insurance?
Compare rates from dozens of companies in less than 3 minutes.