

Types of Small Business Insurance: 13 Policies You Should Consider
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
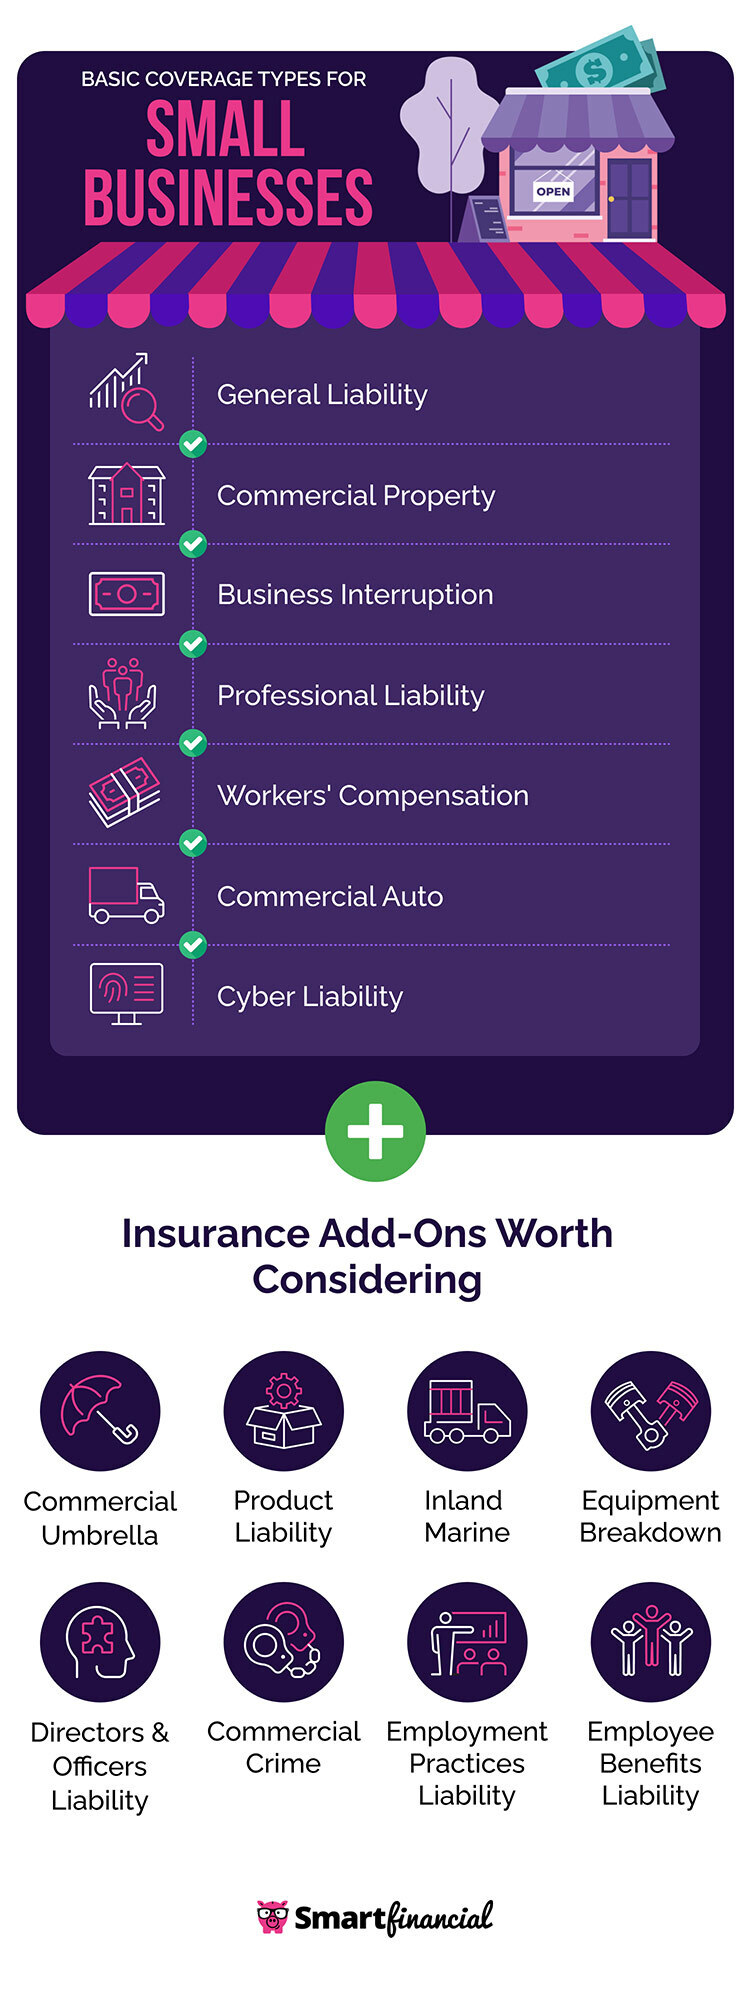
As a small business owner, you should maintain multiple types of commercial insurance, from policies that account for your biggest liability exposures to those that broadly protect your business-owned property. Some types of insurance for small business owners are required by law, while others may only be recommended depending on the risks in your industry.
Read on to learn more about the most important small business insurance policies and what they cover.
|
Key Takeaways
|
On This Page

Essential Types of Small Business Insurance
1. General Liability Insurance
2. Professional Liability Insurance (Errors & Omissions)
3. Workers' Compensation Insurance
4. Business Owner's Policy (BOP)
5. Product Liability Insurance
6. Commercial Auto Insurance
7. Business Income Insurance
8. Employment Practices Liability Insurance (EPLI)
9. Cyber Liability Insurance
10. Commercial Property Insurance
11. Directors and Officers Insurance (D&O)
12. Key Person Insurance
13. Commercial Umbrella Insurance
Specialized Coverage Types of Small Business Insurance
Types of Small Business Insurance at a Glance
How To Get the Right Type of Insurance for Your Small Business
FAQs

Essential Types of Small Business Insurance
Below are some of the most important types of small business insurance. Keep in mind that each business’s insurance needs may vary, and it’s worth speaking with an insurance agent to understand which coverages are most beneficial.
1. General Liability Insurance
General liability insurance protects your business from financial loss if you are held liable for a guest’s injury or damage to their property. For example, if a customer at your restaurant slips on the floor and breaks both their arm and their cell phone, your general liability insurance could cover their medical bills and property repairs, along with your legal expenses if they decide to sue your business. Additionally, general liability insurance includes coverage for personal and advertising injury, such as a lawsuit for defamation of another person or business, or for infringing on their intellectual property or copyrights.
2. Professional Liability Insurance (Errors & Omissions)
Professional liability insurance, also known as errors and omissions (E&O) insurance, covers your business against lawsuits arising from failures in the performance of your professional duties, such as malpractice, errors and negligence. For example, it could cover a trucking business that is sued for negligently mishandling cargo or for breaching a contractual obligation by failing to deliver freight on time. Some states even require professional liability coverage for businesses that provide professional services, like consulting.[1]
3. Workers' Compensation Insurance
Purchasing workers’ compensation insurance can protect your business from employee lawsuits by ensuring that your employees have coverage for lost wages, medical expenses and disability payouts as needed if they become sick or injured while working. It can also provide a death benefit for an employee’s dependents if the employee dies on the job. Workers’ compensation insurance is a legal requirement for most businesses with multiple employees throughout most states, excluding Texas, South Dakota and Wyoming.[2]
4. Business Owner's Policy (BOP)
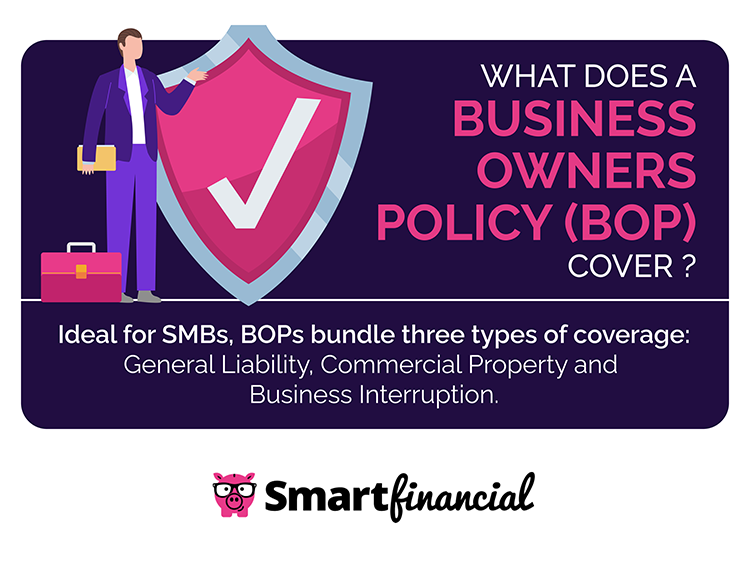
Many small and midsize businesses opt to cover their most basic risks by purchasing a business owners policy (BOP), which bundles general liability, commercial property and often business interruption coverage into one convenient commercial insurance package. Not every business qualifies to purchase a BOP – eligibility is generally limited to small and midsize businesses in low- to medium-risk industries.[3]
5. Product Liability Insurance
Businesses that manufacture or distribute goods may benefit from obtaining product liability insurance, which covers liability claims arising from defects in the design, manufacture or marketing of a product. For example, it could cover a legal settlement for a toy company that releases a product with an unlabeled choking hazard.
Product liability insurance may be included in a general liability policy or available as a standalone purchase, depending on your insurer.[4]
6. Commercial Auto Insurance
If you use any type of car, van or truck to conduct business activities, you need to purchase a commercial auto insurance policy, as consistent business use won’t be covered under standard car insurance.[5] A commercial auto policy typically includes liability coverage, along with other legally required forms of coverage in your state, although optional coverages like physical damage can often be purchased for an increased premium.
7. Business Income Insurance
Business income insurance, also called business interruption insurance, covers lost income, employee payroll, temporary relocation costs and other costs that arise if a sudden peril prevents your business from operating as usual. For example, in the case of an office fire, business interruption insurance could pay for you to temporarily rent a new office space or reimburse lost revenue while your business is transitioning to a new location and is unable to operate.
Business income insurance typically isn’t available as standalone coverage and must instead be purchased as an endorsement to an existing commercial policy or as part of a business owners policy.[7]
8. Employment Practices Liability Insurance (EPLI)
Employment practices liability insurance (EPLI) covers your business when it’s taken to court over a claim of violating an employee’s rights. Common reasons for EPLI claims include allegations of wrongful termination, discrimination, harassment and retaliation.
9. Cyber Liability Insurance
Cyber insurance can help you handle the burden of unexpected expenses that come up when your company is the victim of a cybercrime, such as a data breach. For example, cyber liability insurance may cover expenses related to investigation, litigation, crisis management and security improvements after a hacker steals customer information from your e-commerce shop.
10. Commercial Property Insurance
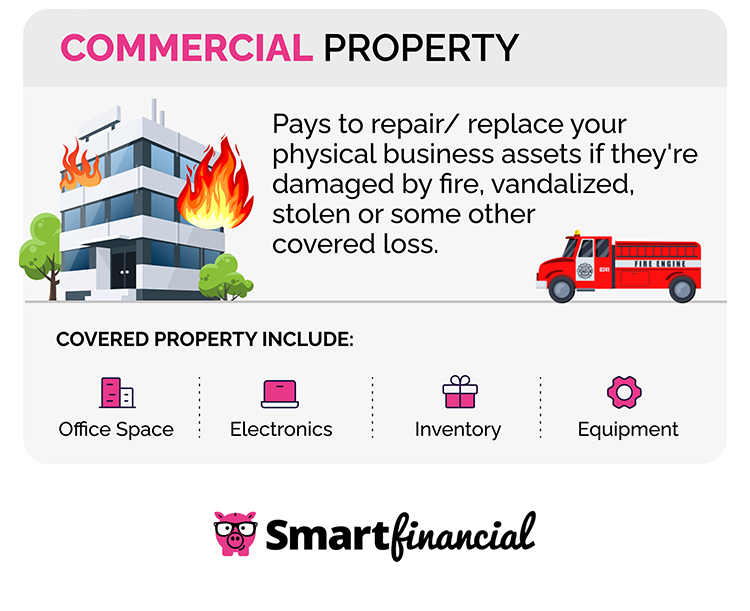
If a sudden peril damages or destroys your commercial building or the items stored inside it, commercial property insurance can cover repairs or replacements. For example, your commercial property coverage could pay to rebuild part of your office building and replace all your damaged computers and furniture after a fire.
11. Directors and Officers Insurance (D&O)
Directors and officers (D&O) liability insurance protects your managers, board members and other corporate leaders in case they are sued for misconduct or poor management. For example, your D&O insurance could cover your business’s legal defense if your chief operating officer (COO) is accused of misusing company funds.
12. Key Person Insurance
Key person insurance is a commercial life insurance policy that can help your business avoid financial strife if a critical employee, including CEOs and company founders, passes away or experiences a work-ending disability. For example, key person insurance could help cover lost income until a replacement is found or pay off remaining debts and expenses to close the business. Key person coverage can be set for a term, typically 10 to 30 years, or be permanent, offering a payout as long as premiums are paid.[8]
13. Commercial Umbrella Insurance
Commercial umbrella insurance provides excess liability coverage, stepping in if a significant accident or lawsuit exhausts the coverage limits on your general, professional, auto or other commercial liability insurance policies. For example, if you face a lawsuit settlement of $1.5 million, but have a general liability policy limit of $1 million, commercial umbrella insurance could help you cover the remaining $500,000.
Specialized Coverage Types of Small Business Insurance
Below, we’ll cover a few additional specialized commercial coverage types that may benefit small businesses.
Commercial Crime Insurance
Commercial crime insurance protects your business if it faces losses due to employee criminal acts, including theft from your business, customers and your clients. For example, if an employee is found to have embezzled from the company, commercial crime insurance could help reimburse you for the money taken.
Home-Based Business Insurance
Home-based business insurance consists of various commercial coverages needed for working out of your residential home, as opposed to a commercial building you own or rent. Coverage can vary based on the policies you select, either as a homeowners endorsement or standalone coverage, but often includes general liability coverage for guests and clients visiting your home-based business and business property coverage for equipment and inventory you store in your home.[9]
Because each home-based business may need different forms of coverage depending on its industry, number of employees and other factors, consider speaking with a licensed insurance agent to help determine which home-based business insurance policies are necessary and beneficial.
Equipment Breakdown Insurance
Equipment breakdown coverage can cover your business equipment against certain sudden perils not covered by commercial property insurance, such as internal mechanical or electrical failures. For example, if an office HVAC unit fails due to an internal mechanical issue, equipment breakdown coverage could help pay for repairs.
Inland Marine and Cargo Insurance
Inland marine insurance covers business property while it is in transit, such as a contractor’s tools while they travel between different job sites. Motor truck cargo insurance is a type of inland marine coverage that specifically covers freight hauled by truck drivers. Under federal law, all motor carriers and freight forwarders that participate in the transportation of household goods must maintain cargo insurance.[10]
Employee Benefits Liability
Employee benefits liability (EBL) insurance covers claims arising from errors in the administration of employee benefits. For example, it could cover legal fees if you are sued for prematurely canceling an outgoing employee’s health insurance or giving an employee incorrect information about the company’s paid time off (PTO) policy.
Commercial Flood Insurance
Commercial property insurance often excludes coverage for damage caused by floods, so you may need to purchase a separate commercial flood insurance policy, depending on the natural disaster risk in your area.
Types of Small Business Insurance at a Glance
Below is a brief overview of what you should know about different types of small business insurance:
- You’ll need to determine which types of small business insurance you need by reviewing your business’s industry, potential risks and legal requirements.
- General liability, commercial property and business income insurance can be purchased through a business owners policy, which bundles all three coverages together.
- Some forms of insurance, such as commercial auto and workers compensation, may be required by law if you use a vehicle for business or have employees.
- Depending on the risks associated with your business, you may also benefit from buying cyber, D&O, product liability and home-based business insurance, among other coverages.
How To Get the Right Type of Insurance for Your Small Business
Getting the right type of insurance for your small business will first necessitate determining which policies are legally required or most beneficial. Once you’ve narrowed down your options and determined your ideal coverage limits, get quotes from three to five insurance companies to understand the most affordable premium costs.
Gathering quotes can be tedious, as you’ll typically need to obtain them from each insurer individually. Speed things up by using an insurance marketplace like SmartFinancial. After answering a brief questionnaire, we’ll connect you with a licensed insurance agent to help you get the small business insurance that meets your needs. Click here for free commercial insurance quotes today!
- Insurance quotes /
- Commercial /
- Types Of Insurance Small Businesses
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Commercial Insurance Quote.
More on Commercial Insurance

Looking for Commercial Insurance?
Compare rates from dozens of companies in less than 3 minutes.