

What Is Business Insurance, and How Does It Work?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Also known as commercial insurance, business insurance is a policy that insures businesses against damage to company property, liability claims and other financial losses. Certain types of business insurance may be required by law — depending on your industry and how your business operates — and you should generally maintain several types of coverage, regardless of whether they are mandatory.
Read on to learn more about what business insurance is, what coverages it typically includes and how much you may have to pay for your policy.
|
Key Takeaways
|


What Is Business Insurance?
Business insurance refers to any policy that can protect a commercial enterprise against the various risks it may face during its day-to-day operations, including sudden property damage, liability lawsuits and more. Many insurers offer prepackaged business insurance bundles, though you may also be able to customize your policy with the precise coverage types that most closely match your company’s needs.
Do I Need Business Insurance for My Business?
Some types of commercial insurance are required by law for many businesses. For example, workers’ compensation insurance and commercial auto liability insurance are mandatory for most businesses that have employees and use vehicles for commercial purposes, respectively.[1][2] Other coverage types may also be required, depending on your industry.
Additionally, certain commercial insurance coverages may be required if you need to obtain a license or secure a client contract. Even if you aren’t required to purchase certain business insurance products, it’s still important to evaluate your coverage needs and obtain a policy that adequately covers the risks your business regularly faces.
What Does Business Insurance Cover?
The level of coverage provided by your business insurance will ultimately depend on the coverage types you choose to include in your policy. Examples of losses that are often covered by commercial policies include the following:
- Medical bills, property repairs or legal fees related to liability claims
- Repairs or replacements of business-owned buildings, equipment and inventory damaged by sudden perils
- Financial losses caused by sudden perils that disrupt normal business operations
- Lawsuits triggered by negligence, errors or omissions in the performance of professional services
- Employee injuries or illnesses sustained on the job
- Commercial car accidents
- Losses stemming from data breaches or other cyberattacks
How Much Does Business Insurance Cost?
The coverage types you select will also determine how much your business insurance costs. To get an idea of what your premiums could look like, see the following table, which goes over average monthly rates for various types of business insurance from The Hartford.[4]
|
Coverage Type |
Average Monthly Premium |
|---|---|
|
Business owners policy |
$141 |
|
Standalone general liability insurance |
$68 |
|
Standalone commercial property insurance |
$134 |
|
Professional liability insurance |
$62 |
|
Workers’ compensation insurance |
$81 |
|
Commercial auto insurance |
$574 |
In addition, the following factors will impact the amount you have to pay for commercial coverage:[4]
- Industry: Certain industries have a higher risk of filing claims than others, so business owners in these high-risk industries generally have to pay more for insurance coverage. For example, fishing businesses can expect higher workers’ compensation insurance premiums than marketing firms because the risk of employee injuries is much higher in the fishing industry.
- Size: Your coverage costs are influenced by your company’s size and scope, including how many people you employ and how much you spend on payroll. For example, a trucking company with a large fleet of commercial vehicles can naturally expect to pay more for auto coverage than a small pizzeria with a single delivery car.
- Coverage needs: The coverage details of your policy will play a role in determining your commercial insurance rates. In general, the more coverage types your policy includes and the higher your coverage limits are, the more you’ll have to pay for insurance.
- Location: Where you operate your business also impacts your commercial insurance prices. If you operate in a heavily populated area with a high rate of crime or in a state with more stringent insurance requirements, your premiums will likely be higher.
- Visibility: Famous businesses may be subject to greater scrutiny and may face a higher likelihood of being sued, necessitating higher liability insurance premiums.
- Claims history: Businesses that have filed multiple commercial insurance claims in the past are generally considered more likely to file claims again in the future and are often charged more for coverage as a result.
What Types of Business Insurance Are There?
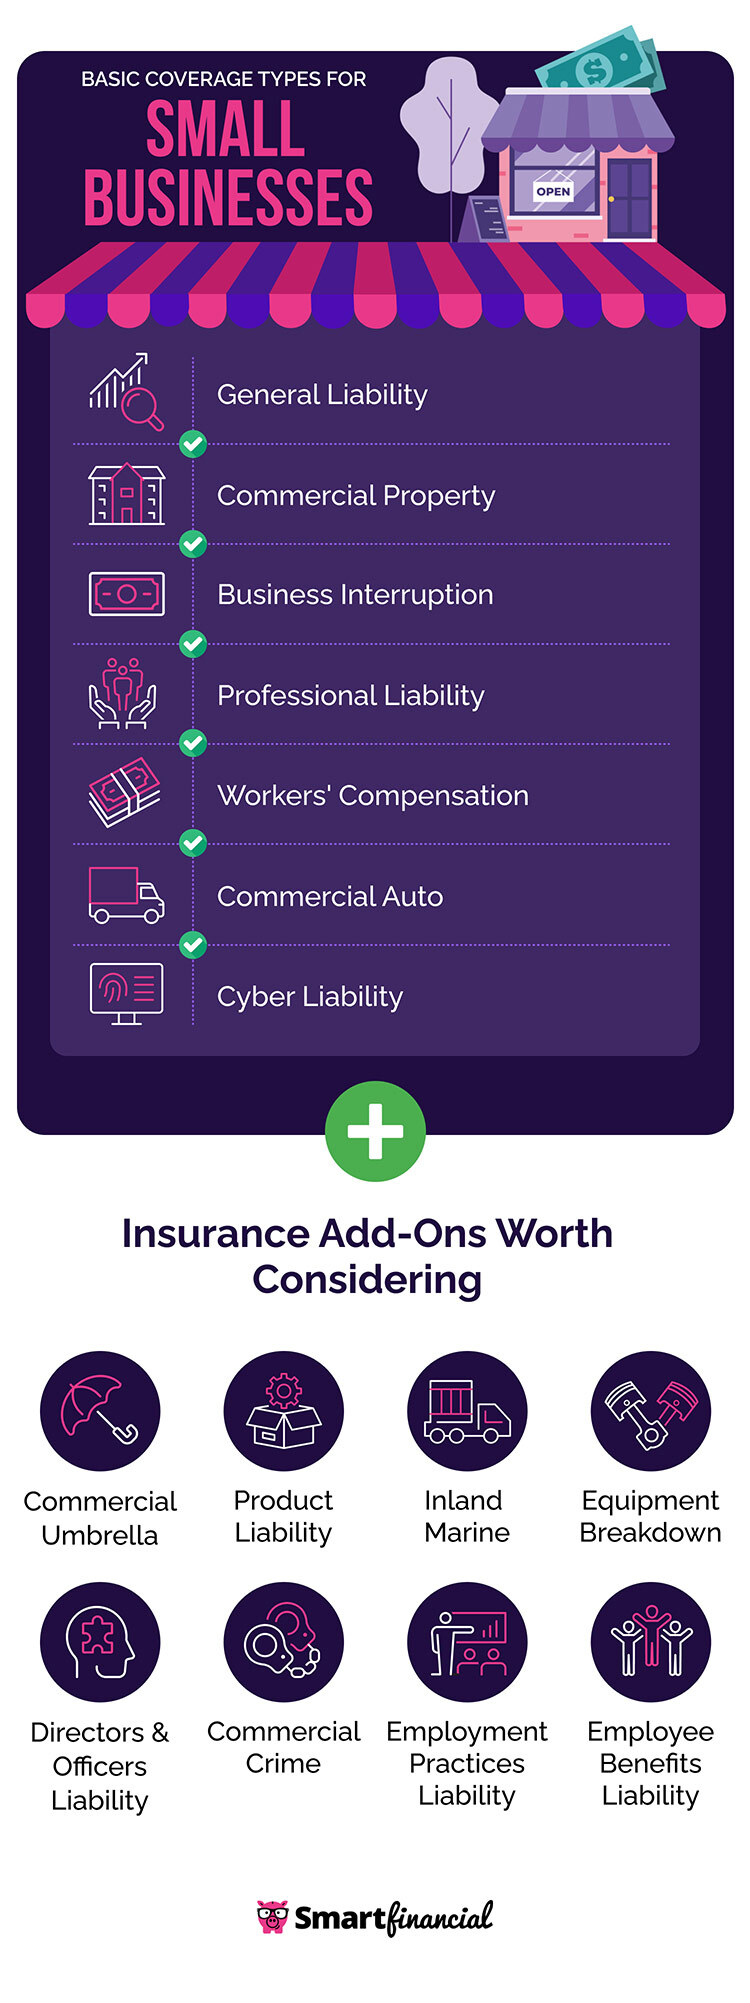
In the upcoming sections, you’ll learn about some of the most important types of commercial insurance to consider purchasing for your enterprise.
General Liability
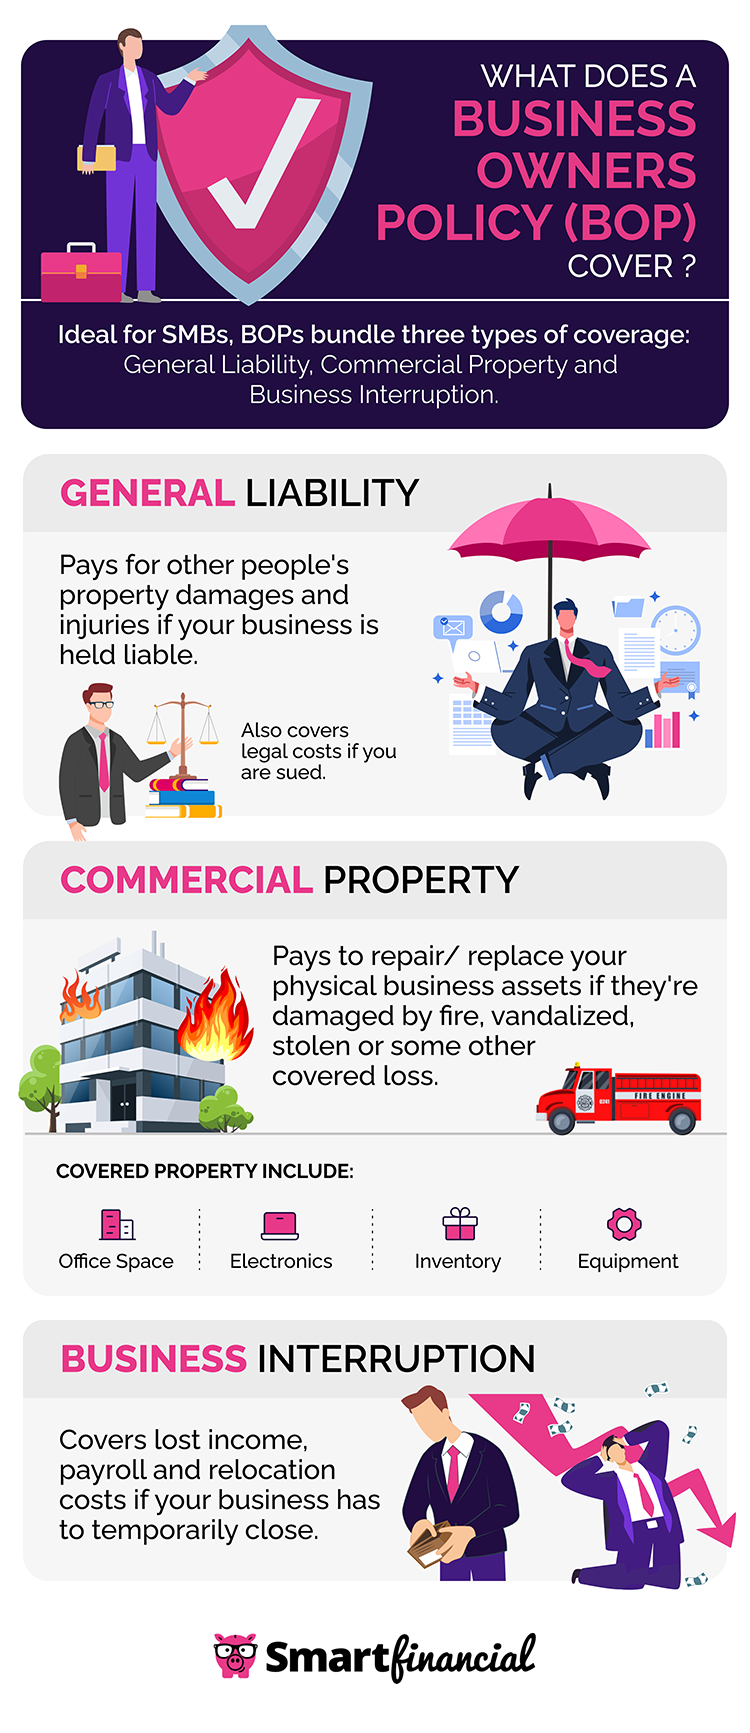
General liability insurance is the starting point for many commercial insurance policies, as it provides foundational coverage for medical treatments, repair bills and legal fees if someone is injured or their belongings are damaged on the property of your business. For example, it may step in if a customer at your restaurant breaks their wrist and shatters their cell phone after slipping on a wet spot.
Commercial Property
Commercial property insurance provides coverage for the buildings you own and any items stored on your property — such as equipment, furniture, documents, inventory and landscaping. Covered perils commonly include fire, explosions, water damage from burst pipes, storms, theft and vandalism. However, earthquakes and floods usually aren’t covered unless you purchase additional commercial earthquake and commercial flood insurance.[5]
Business Interruption
Business interruption insurance can make up for lost income and cover temporary relocation costs or other operational expenses if a covered peril prevents you from conducting business as usual. For example, if a fire breaks out at your consulting firm, commercial property insurance could pay to replace your computers and fix your office building, while business interruption insurance could pay to rent a new office space while you wait for repairs to be completed.
Small and midsize business owners can often bundle general liability, commercial property and business interruption coverage together by purchasing a business owners policy. BOPs may allow you to more easily manage your coverage, and it is often cheaper to buy a BOP bundle than to purchase each of these coverage types separately.
Professional Liability
Professional liability insurance — also known as errors and omissions insurance — can cover attorney fees, settlements, court-ordered damages and other legal expenses if you are sued due to an alleged failure in the performance of your professional duties. Examples of claims your E&O insurance may cover include misrepresentation, negligence, breach of contract and inaccurate advice.
Workers' Compensation
Workers’ compensation insurance can cover lost wages, hospital bills, rehabilitation costs and disability payments if one of your employees experiences an injury or gets sick because of their work. It can also pay out a death benefit to your employee’s beneficiaries if the employee dies due to an on-the-job accident. Workers’ compensation insurance generally provides coverage regardless of fault, and it can protect you from being sued by an employee or their family.[6]
Commercial Auto
Companies that use vehicles for business purposes need commercial auto insurance to cover any losses that may stem from a car accident. The most fundamental portions of a commercial auto insurance policy are liability coverage — which steps in if one of your drivers injures someone else or damages their car in an accident — and physical damage coverage — which covers damage to your business-owned vehicles from accidents or external perils.
Depending on the extent of your business operations, you may need to consider additional commercial auto coverages. For example, you may need hired auto insurance if your business uses rented or leased vehicles rather than cars it outright owns, while you may need cargo insurance to cover sudden damage to any freight your drivers are transporting.
Cyber Liability
A cyber insurance policy can insure your business against financial losses caused by hacking and other cybercrimes. In particular, third-party cyber liability insurance steps in if your clients or other partners experience a loss due to a cyberattack against your business. Your policy may also include first-party coverage for your company’s own expenses, such as legal counsel, public relations, regulatory fines and recovery of lost data.
Other Policies To Consider
While the coverage types discussed above are recommended for most businesses, you may also need other policies, depending on the specific risks associated with your line of work. Examples of other coverages worth considering include the following:
- Commercial umbrella insurance: Commercial umbrella insurance offers extra liability coverage in case an especially costly claim exhausts the coverage limits of your general, auto, professional or other liability insurance policy.
- Product liability insurance: If a customer becomes sick or injured or experiences some other loss due to an error in the design, manufacturing or marketing of one of your products, product liability insurance can step in to cover relevant legal expenses. Keep in mind that some insurers include this coverage within general liability insurance, so you may not need a separate product liability insurance policy.[7]
- Inland marine insurance: Inland marine insurance can pay to repair or replace business-owned items that are damaged or lost while in transit, making it an essential coverage for businesses that regularly transport tools, equipment and other items to and from various jobsites or other locations.
- Equipment breakdown insurance: Equipment breakdown insurance covers damage to commercial equipment caused by certain perils that aren’t covered by commercial property insurance, such as short circuits and internal mechanical breakdowns.
- Directors and officers liability insurance: You may need D&O liability insurance to shield your company’s executives from liability claims related to accusations of mismanagement, misuse of company funds and similar breaches of corporate responsibility.
- Commercial crime insurance: A commercial crime insurance policy can provide reimbursement if your employees commit crimes targeting your business, such as fraud or forgery.
- Employment practices liability insurance: EPLI can cover necessary legal costs if a manager at your business is accused of wrongful termination, discrimination, sexual harassment or a similar violation of employee rights.
- Employee benefits liability insurance: In the event that an employee sues you for making a mistake in the administration of their benefits package, EBL insurance can cover your legal fees or reimburse the employee for their losses. Coverage may apply if you give an employee incorrect information about their benefits or fail to enroll them in the correct plan, among other situations.
How Do I Get Business Insurance?
Every insurance carrier has its own methods for calculating premiums, so the only way to know for sure that you’re getting the best possible deal is to compare quotes from multiple insurance companies. To receive a quote, you’ll need to share information such as your business location, industry, annual revenue and number of employees.
Sharing all this information can take a long time — unless you shop through SmartFinancial. Once you fill out a brief questionnaire, we’ll connect you with an agent who can handle the comparison shopping for you, allowing you to find a high-quality commercial insurance policy in as little as a few minutes. Speak with an agent, and compare business insurance quotes for free today!
- Insurance quotes /
- Commercial /
- What Is Business Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Commercial Insurance Quote.
More on Commercial Insurance

Looking for Commercial Insurance?
Compare rates from dozens of companies in less than 3 minutes.