

Business Income Insurance: Coverage and Costs Explained
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Business income insurance — also known as business interruption insurance — can soften the blow of covered perils that damage your commercial property and temporarily disrupt your business operations by helping pay for expenses like payroll, rent and relocation costs. This type of commercial insurance is usually bundled within a commercial property or business owners policy and may cost as little as a few hundred dollars per year.
Keep reading for more information about small business income protection insurance, including what factors influence how much it costs and when coverage does and doesn’t apply.
|
Key Takeaways
|
On This Page

What Is Business Income Coverage?
What Does Business Income Insurance Cover?
Types of Business Income Insurance
Who Needs Business Income Insurance?
How Much Does Business Income Insurance Cost?
Business Income Insurance vs. Business Interruption Insurance
Business Income Insurance at a Glance
How To Get Business Income Insurance
FAQs

What Is Business Income Coverage?
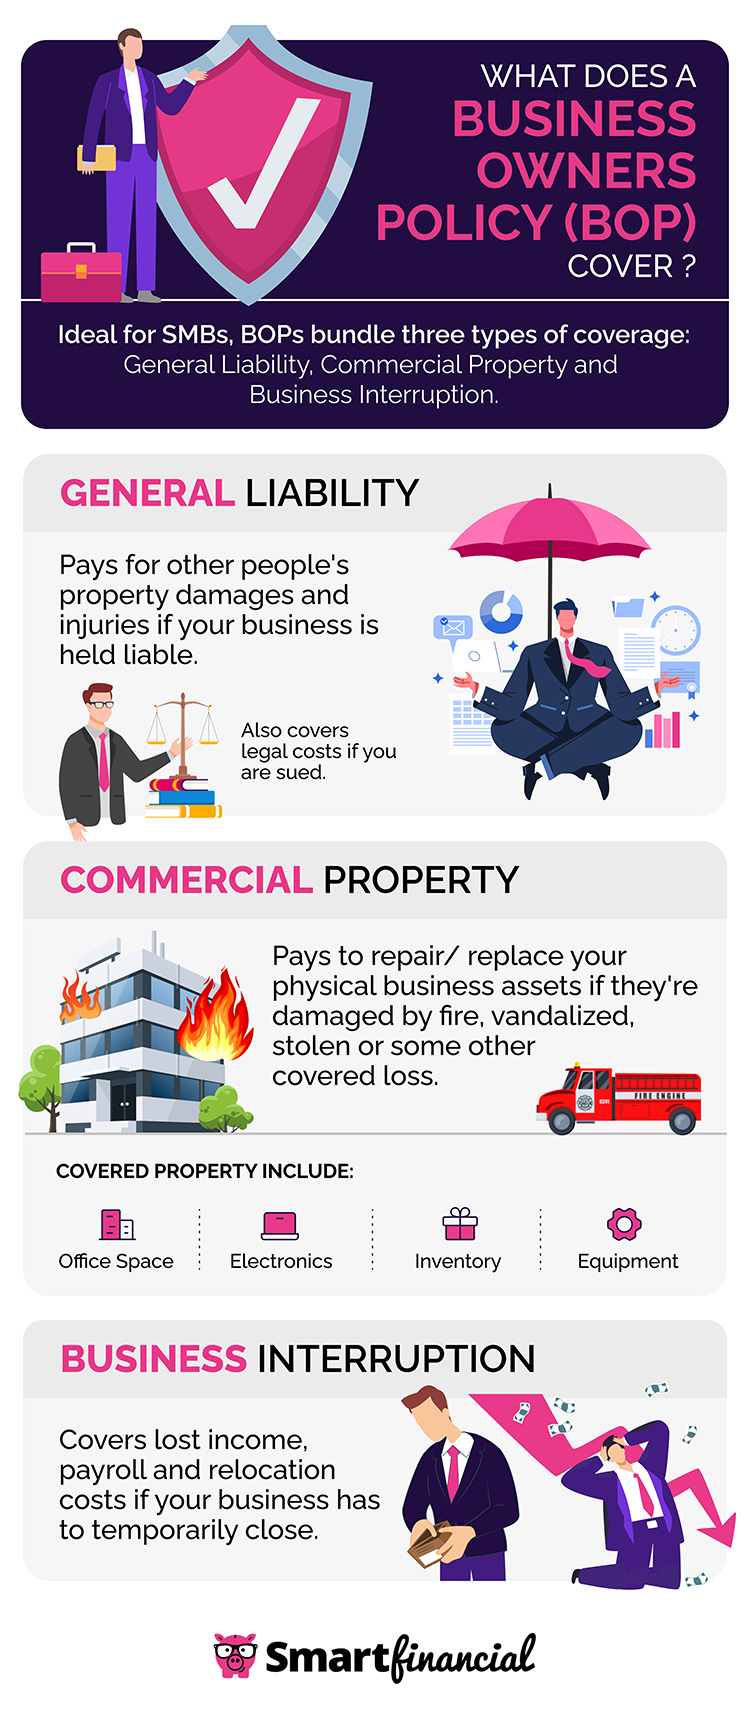
Business income insurance is a commercial insurance product that can help mitigate your financial losses if your business must temporarily close or adjust its operations due to a covered peril. Generally, business income coverage is not available as a standalone policy. Instead, it may be included in a commercial property insurance policy or bundled alongside commercial property and general liability insurance in a business owners policy.[1]
While business income claims typically don’t require a deductible, there may be a waiting period of up to 72 hours.[2] This means you may have to cover your own expenses out of pocket for the first three days after a covered loss, and short-term business interruptions may not be covered. Meanwhile, basic policies only provide coverage for up to 30 days — though you may be able to buy an endorsement that covers a period of restoration lasting up to 360 days.[3]
What Does Business Income Insurance Cover?
Since the two coverage types are linked together, you can generally expect your business income insurance to step in if you experience property damage because of a peril covered by your commercial property insurance coverage. Examples of covered perils include the following:[4][5][6][7]
- Fire
- Lightning
- Windstorms
- Vandalism
- Theft
- Damage from vehicles
- Damage from aircraft
- Civil commotion
- Falling objects
- Damage from ice
- Hail
- Explosions
- Water damage from burst pipes
In the event of a covered loss, your business income insurance company may help pay for the following expenses:[8]
- Lost income
- Rent and lease payments
- Mortgage and other loan payments
- Taxes
- Payroll
- Temporary relocation costs
- Costs associated with training employees on how to use new or rented equipment
| Situation | How Business Income Coverage May Help |
| A kitchen fire burns down your restaurant | Enables you to keep paying your employees while you wait for your restaurant to be rebuilt or look for a new permanent location |
| Someone breaks into and vandalizes your office building and steals your employees’ computers | Pays for you to rent office space and computers while your building is being repaired and the police search for your stolen equipment |
| Your retail store must shut down for several weeks after a windstorm breaks your windows and causes water damage to much of your inventory | Ensures you don’t miss out on all the profits you would have brought in if you were able to operate during the downtime |
| A distracted driver crashes into your coffee shop, injuring multiple customers | Keeps you from falling behind on your rent or mortgage payments if business is slow to pick up after the accident due to some customers fearing for their safety |
What Isn’t Covered by Business Income Insurance?
Standard business income insurance policies may not provide coverage for the following situations or expenses:[1][3]
- Damage from perils that aren’t covered by your commercial property insurance, such as floods or earthquakes
- Voluntary shutdowns
- Supply chain disruptions
- Pandemics and other outbreaks of communicable diseases
- Replacement of income from revenue streams that aren’t documented in your financial records
- Repairs to broken items
- Utility bills
Types of Business Income Insurance
Various coverage types may be automatically included in your business income insurance or available to add as policy endorsements, such as the following:[2][3]
- Extended business income: Even if your damaged property has been repaired or replaced, extended business income coverage can provide financial protection in case business does not pick up as quickly as expected after you open up shop again.
- Off-premises utility services: Off-premises utility services coverage allows your business income insurance to take effect not only after sudden property damage, but also after interruptions triggered by disruptions to power, communication, water or other utility services that originate away from your commercial property.
- Contingent business interruption: While business income insurance generally applies after damage to your property, contingent business interruption coverage steps in after damage to property owned by a different entity that your company is dependent on, such as a supplier or wholesale buyer you regularly do business with.
- Extra expense: Extra expense coverage takes care of expenses triggered by business interruptions that extend beyond your typical operational costs, such as hiring more employees or leasing equipment due to a covered loss.
- Civil authority: Civil authority coverage insures your enterprise against business interruptions that occur when the local, state or federal government prohibits access to your property on account of damage in the area, such as flood or wildfire damage. Keep in mind that this coverage may only apply for up to two weeks in a row.
Who Needs Business Income Insurance?
Most businesses would benefit from maintaining business income insurance, but coverage may be especially important for businesses that offer products or services at physical locations or rely on functioning equipment to operate.[2] Examples of businesses that typically need business income insurance coverage include the following:[1]
- Restaurants
- Food trucks
- Retailers
- E-commerce stores
- Construction contractors and other tradespeople
- Salons and barbershops
How Much Does Business Income Insurance Cost?
The cost of business income insurance for your business may depend on how you choose to obtain coverage. Business owners policies that come with business income coverage cost an average of $500 to $3,000 per year. If you aren’t eligible for BOP coverage, you may be able to purchase separate commercial property insurance for an annual premium of $800 to $5,000 on average.[9]
Some of the main factors that may be used to calculate your commercial insurance costs include the following:[9]
- Policy details
- Claims history
- Industry
- Size
- Location
- Eligibility for discounts
Business Income Insurance vs. Business Interruption Insurance
Business interruption insurance generally refers to the same type of coverage as business income insurance, and the two terms are often used interchangeably as a result. In many cases, business interruption coverage is one of three components making up a commercial property insurance policy, along with building coverage for the physical structures you operate out of and business personal property coverage for your company-owned items.[1]
Business Income Insurance at a Glance
- Definition: Business income insurance is a type of commercial insurance that shields businesses from major financial losses whenever a covered peril forces them to temporarily cease their regular operations.
- Availability: You may not be able to obtain business income insurance as a standalone policy. Instead, it is usually bundled within commercial property insurance or a business owners policy.
- Limitations: There may be a waiting period lasting up to three days before your business income coverage kicks in, and your insurer may not cover restoration periods lasting more than 30 to 360 days, depending on your policy details.
- Coverage: Your business income policy may cover lost income, payroll, rent, taxes and temporary relocation expenses if your commercial property is damaged or lost due to a sudden peril, such as fire, vandalism, theft, wind or hail.
- Exclusions: Business interruption insurance policies often exclude coverage for voluntary shutdowns, supply chain disruptions, pandemics, floods and earthquakes.
- Options: Some business income policies provide broader coverage options, such as contingent coverage for losses experienced by partners that impact you and extended coverage for financial slowdowns after your normal business operations resume.
- Who needs it: Business income insurance coverage is generally most important for companies with physical locations that could be shut down by sudden damage to their buildings, inventory or equipment — including restaurants, retail stores and barbershops.
- Costs: On average, it costs between $500 and $3,000 annually to purchase a BOP that includes business income coverage. Your exact premiums will ultimately depend on factors like your location, industry and claims history.
How To Get Business Income Insurance
Before settling on a commercial property or business owners policy with business income coverage, it’s best to compare quotes from around three to five different insurance carriers. Examples of the kinds of information you’ll need to have on hand in order to request a quote include your company’s industry, location, annual revenue and employee headcount.
This can be a lengthy process if you reach out to insurers one at a time, but SmartFinancial enables a much simpler comparison shopping process. Simply answer a few questions online, and then we’ll put you in contact with an insurance agent who can help you compare quotes from highly-rated commercial insurance companies. Start comparing business insurance quotes for free today!
- Insurance quotes /
- Commercial /
- Business Income Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Commercial Insurance Quote.
More on Commercial Insurance

Looking for Commercial Insurance?
Compare rates from dozens of companies in less than 3 minutes.