

Errors and Omissions Insurance: Does Your Business Need It?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
You may need errors and omissions insurance to obtain a business license, secure client contracts or obtain a commercial loan, depending on your circumstances. This type of business insurance can cover your legal expenses if you are sued for failing to adequately perform your professional duties. E&O insurance is most important for businesses that offer professional services, such as consulting, accounting, legal representation and medical care providers.
Read on for more information about E&O insurance, including when you should consider an errors and omissions policy and what factors influence the cost of this commercial insurance product.
|
Key Takeaways
|
On This Page

What Is Errors and Omissions Insurance?
What Does an E&O Insurance Policy Cover?
What E&O Insurance Does Not Cover
Who Needs Errors and Omissions Insurance?
Types of Businesses That Need E&O Coverage
Is Errors and Omissions Insurance Required?
Why E&O Insurance Is Beneficial
How Much Does E&O Insurance Cost?
Factors That Affect E&O Insurance Premiums
How Much E&O Coverage Do You Need?
E&O Insurance vs. General Liability Insurance
What Is the Difference Between E&O and Professional Liability Insurance?
Common Types of E&O Insurance Claims
Errors and Omissions Insurance at a Glance
How To Compare E&O Insurance Quotes for Your Business
Frequently Asked Questions About Errors and Omissions Insurance

What Is Errors and Omissions Insurance?
Errors and omissions coverage is a type of commercial insurance that can cover your legal expenses if you are sued over an alleged failure or mistake in the provision of professional services. It can often be bundled together with other business coverage types as part of a commercial package policy. Your E&O insurance may be written as either a claims-made or occurrence policy.[1]
Most E&O policies fall into the claims-made category, meaning they only cover lawsuits filed while your policy is active. However, you may have the option to buy an occurrence policy that covers lawsuits related to any events that occur while the policy is active — even if the lawsuit itself is filed after the policy expires. Occurrence coverage can be beneficial to ensure you are sufficiently covered if you expect to retire or switch careers soon.[1]

What Does an E&O Insurance Policy Cover?
E&O insurance primarily covers legal costs in the event that your business is sued over a professional liability claim. Covered expenses may include attorney fees, court-ordered judgments, settlements and expenses related to subpoenaing witnesses or undergoing regulatory disciplinary proceedings. In addition, your policy may reimburse you for the amount of revenue you lost while attending depositions or trials.[2]
Your legal expense coverage may kick in for a variety of claims related to alleged harm caused by your business. Here’s an overview of the types of claims that are generally covered by errors and omissions insurance policies:[2]
- Errors and omissions: As its name suggests, E&O insurance covers accusations that you caused a financial loss for your client by committing errors or omissions — that is, improper actions you took or proper actions you failed to take, respectively.
- Negligence: Your E&O policy can also provide coverage for lawsuits triggered by oversights or other failures to take proper care in the performance of your professional duties.
- Misrepresentation: If you misrepresent your experience or the nature of the services you provide, it could be grounds for legal action, which should be covered by your errors and omissions insurance.
- Violation of good faith and fair dealing: E&O liability insurance often covers contractual breaches, including violations of good faith and fair dealing. This is a legal term that refers to attempts to undermine the terms of a contract or the benefits that the other party is supposed to receive under that contract.
- Inaccurate advice: Business professionals who give poor or misleading advice to their clients may be able to lean on errors and omissions coverage to protect them from costly lawsuits in case their clients lose money after taking their advice.
- Personal injury: In some cases, your errors and omissions insurance policy will cover your legal fees if you are accused of defaming another person or business — whether in spoken word or in writing.
What E&O Insurance Does Not Cover
Exclusions may vary from policy to policy, but E&O insurance typically doesn’t cover the following losses:[2]
- Employment practices liability claims, such as allegations of harassment or wrongful termination
- Intentional acts of wrongdoing and criminal activity, such as fraud
- Improper use or theft of patents and trade secrets
- Bodily injury and property damage claims
- Employee injuries or illnesses
- Claims related to data breaches, such as the loss or theft of personally identifiable information
Who Needs Errors and Omissions Insurance?
In general, errors and omissions insurance coverage is necessary for any business that offers professional services or expertise rather than producing or selling goods. Examples of industries that need to strongly consider E&O coverage include the following:[1][3][4]
| Health care | Law |
| Accounting | Architecture |
| Engineering | Graphic design |
| Consulting | Insurance and finance |
| Real estate | Software development |
| Marketing and advertising | Education |
| Hairdressing | Publishing and printing |
| Veterinary services | Pet grooming |
| Mental health counseling | Occupational therapy |
| Personal training | Photography |
Types of Businesses That Need E&O Coverage
Read the upcoming sections to explore which types of businesses often benefit the most from errors and omissions insurance and what specific risk factors make E&O coverage essential for each industry.
Insurance Agents and Brokers
As experts on the insurance companies they represent or the types of policies they sell, insurance agents and brokers are expected to make accurate recommendations and correctly provide the services they advertise to clients — which could open them up to liability lawsuits in the event of a mistake, such as recommending inadequate coverage to a home insurance shopper or signing a client up for a more expensive health insurance plan than they requested.
Real Estate Professionals
Real estate agents have an obligation to disclose relevant issues with the properties they sell, accurately present property details — such as the square footage of a home or its proximity to certain amenities — and adhere to important contract deadlines to prevent deals from falling through. Even if a real estate agent acts with the best intentions, E&O insurance may be necessary to ensure uncharacteristic lapses in judgment don’t lead to pricey legal action.
Accountants and Tax Preparers
Various professional errors or omissions could result in client losses and costly legal action for certified public accountants and other tax professionals, necessitating comprehensive professional liability coverage. Examples of E&O losses accountants need to watch out for include calculation errors on financial statements, missed tax filing deadlines and faulty financial advice.
IT Consultants and Technology Firms
Information technology consultants, software developers and other technology professionals face various professional liability risks, such as software failures, cybersecurity breaches caused by their work, project delays and design flaws that cause systems not to function as intended. Fortunately, some insurers offer specialized technology E&O insurance policies that cover claims related to negligence, breach of contract and other cyber risks.[5]
Marketing and Advertising Agencies
Errors and omissions coverage may help marketing and advertising firms that are sued due to the underperformance of a marketing campaign or a failure to issue key deliverables outlined in a client contract. Keep in mind that you may need separate media liability insurance to cover defamation or copyright claims related to advertisements or other materials you create for another business.[6]
Architects and Engineers
Architects and engineers may face immense pressure because of the responsibility they have to develop sound designs, present accurate specifications for upcoming projects and oversee projects to ensure no structural problems arise once a building or other structure is constructed. If something slips through the cracks and a structural flaw emerges, E&O coverage may protect architectural and engineering professionals from catastrophic financial losses.
Financial Advisers and Planners
Since financial planners and similar advisers have a great deal of influence on their clients’ investment choices and other financial decisions, they naturally have a high exposure to lawsuits when investments go awry and clients lose money, making professional errors and omissions insurance essential to maintain financial stability in the face of potentially unpredictable market shifts.
Is Errors and Omissions Insurance Required?
Errors and omissions insurance is not universally required by law, but there are some situations in which it may be mandatory for your business, such as the following:[7][8][9]
- Professional licensing: Depending on your state and industry, you may need to show proof of E&O coverage to obtain a professional license. For example, several states require business owners to maintain errors and omissions insurance to obtain a real estate license.
- Contractual obligations: A certificate of professional liability insurance is often a prerequisite for securing contracts with certain clients — especially consulting clients and government entities.
- Membership stipulations: In some cases, you may need to maintain a minimum level of E&O coverage to join and accept work through a staffing agency or a similar professional network or association.
- Loan requirements: Commercial lenders may require certain businesses to carry errors and omissions coverage. In particular, you will likely need to show proof of E&O and other types of liability coverage to secure a loan through the Small Business Administration.
Why E&O Insurance Is Beneficial
E&O insurance is beneficial because it can potentially prevent an especially costly lawsuit from bankrupting your business — providing critical protection necessary for even the most competent of business professionals. Crucially, E&O coverage can step in even if you have not actually made a meaningful mistake in carrying out your professional duties, covering your legal defense in the event of a frivolous lawsuit.[10]
How Much Does E&O Insurance Cost?
The average cost of errors and omissions insurance may range from less than $500 per year for certain individual professionals to more than $20,000 per year for certain large-scale firms.[11] Ultimately, your premiums may vary based on the details of your policy and the level of risk associated with your business, and you need to collect quotes from multiple insurers to find the best possible price on the coverage you need.
Factors That Affect E&O Insurance Premiums
Keep reading for a breakdown of the main cost factors that can impact how much you have to pay for errors and omissions policies.
Industry and Profession Type
Insurers consider various details about your business when setting rates, including its industry. E&O coverage is often more expensive for businesses that offer highly technical services or advise clients on high-stakes matters — like the medical, legal and consulting industries — since there is a greater risk of client disputes or harm due to professional mistakes. Conversely, coverage may be cheaper for lower-risk businesses that merely offer creative services.[11]
Additionally, your commercial insurance company will likely take your location into account when determining the premiums for your errors and omissions insurance policy. Specifically, location-based factors like local regulations, regional claim patterns and population density may influence the amount of coverage you need and how much your policy should cost.[11]
Annual Revenue and Business Size
In general, larger businesses with more clients, employees and revenue have a greater liability exposure, raising the risk of lawsuits that may necessitate filing an errors and omissions insurance claim. As a result, a small business or solo professional can likely expect to pay less for coverage than a sizable corporation that operates throughout the country.[11]
Coverage Limits and Deductibles
Your policy details — including the coverage limits and deductibles you select — also impact your E&O insurance premiums. If you have a high liability exposure and select high coverage limits to account for the risk of experiencing a relatively large number of professional liability lawsuits, you can expect to pay more for your errors and omissions insurance policy.[11]
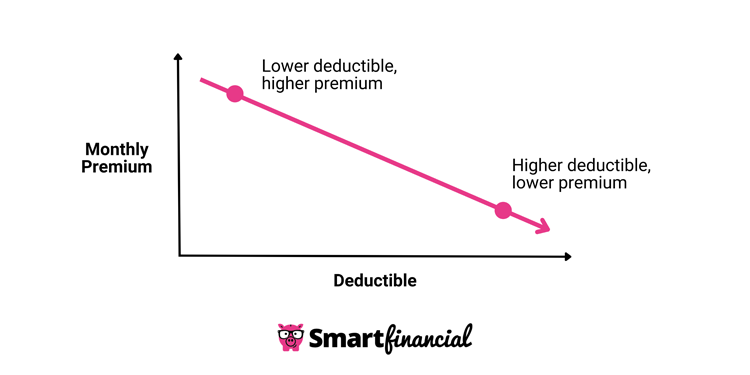
Meanwhile, you can secure lower premiums by raising your deductible, which is the amount of money you agree to personally contribute out of pocket toward every covered claim. Of course, you should make sure you have enough money to cover your higher deductible in case of a lawsuit.[11] E&O insurance deductibles may range from as low as $1,000 to as high as $25,000.[1]
Claims History
The cost of your E&O policy may depend on your claims history, since businesses that have filed multiple claims before may be considered more likely to file additional claims in the future. Your insurer may also consider other details about your business to fully evaluate your risk profile, like how long you have been in business, how detailed your records are and whether you have a track record of consistently following procedures and resolving disputes quickly.[11]
How Much E&O Coverage Do You Need?
Many small businesses opt for $1 million worth of E&O insurance per claim and $3 million worth of coverage in aggregate across all claims during the coverage period.[12] However, you may want to consult with a licensed insurance agent to determine the appropriate coverage levels for your situation. Factors to consider when selecting your E&O coverage limits include the following:
- Industry standards and the typical cost of claims in your profession
- Client contract requirements that may mandate a minimum level of coverage
- Your company’s revenue and the total value of the assets you need to protect
- Your personal and business risk tolerance
E&O Insurance vs. General Liability Insurance
E&O insurance differs from general liability insurance in terms of the types of losses it covers and the types of businesses that need it. See the table below for a rundown of the main differences to keep in mind when comparing these two commercial coverage types:[13]
|
|
E&O Insurance |
General Liability Insurance |
|
Covered Claims |
Errors, omissions, negligence, misrepresentation, poor advice, breach of contract and personal injury leading to third-party losses |
Third-party bodily injury, property damage and personal or advertising injury |
|
Covered Expenses |
First-party legal expenses, including defense costs, judgments, settlements and other court fees |
First-party legal expenses and third-party medical treatments or property repairs |
|
Who Needs It |
Businesses that provide professional services, such as consulting, real estate, insurance, finance and IT businesses |
Most types of businesses, including retail, construction, contracting, fitness and professional services businesses |
|
When Claims Occur |
Potentially while professional services are being performed or after they have been performed |
Usually during regular business operations |
What Is the Difference Between E&O and Professional Liability Insurance?
Professional liability insurance and errors and omissions insurance refer to the same type of coverage, so the two terms can be used interchangeably. That said, the preferred terminology may vary based on the industry you operate in. For example, E&O insurance is the more common wording for startups and businesses in the technology and real estate sectors.[14]
Conversely, professional liability insurance is the more commonly used term for architects, accountants, consultants and other businesses that offer various kinds of professional services. Meanwhile, malpractice insurance is another term that typically refers to specialized professional liability coverage for businesses in the medical and legal fields.[14]
Common Types of E&O Insurance Claims
E&O insurance can cover a wide range of claims related to the professional services you provide. Check out the following table for real-world examples of claims your professional liability policy may cover:
| Type of Claim | Example |
| Poor advice | A transportation and logistics company sues its compliance consultant when it is fined for creating an environmental hazard after receiving incorrect information about the laws for transporting hazardous materials in a certain state |
| Negligence | A surgeon is accused of recklessly failing to employ proper sanitation procedures, resulting in the death of a patient who developed a post-surgery infection |
| Missed deadlines | A tax preparer violates the terms of a contract by failing to file their client’s documents on time, leading to fines and other legal penalties for the client |
| Breach of contract | A publishing company signs an exclusive deal with a social media influencer to prevent a rival publisher from doing so, but it fails to provide the editing, publication and marketing services outlined in the contract |
| Misrepresentation | A construction contractor presents misleading information about their prior experience while bidding for a new contract and is then unable to perform the job correctly after being hired |
| Failure to perform agreed-upon services adequately | An electrician makes an error while installing electrical wiring in a home, resulting in a fire that causes significant damage to the client’s property |
| Copyright infringement | A marketing agency mistakenly uses a copyrighted image in a client’s advertising campaign, which leads to the client being sued |
Errors and Omissions Insurance at a Glance
- Definition: Errors and omissions insurance — also known as professional liability or malpractice insurance — is a type of commercial insurance that covers liability claims related to alleged failures or mistakes in the performance of professional services.
- Coverage: An E&O insurance policy can cover your legal expenses if you are sued for errors, omissions, negligence, misrepresentation, inaccurate advice, personal injury or breach of contract.
- Who needs it: Any business that offers professional services needs errors and omissions coverage. Examples of industries that commonly need professional liability coverage include insurance, real estate, finance, consulting, marketing, accounting and engineering.
- Requirements: E&O insurance isn’t required by law, but it may be required to obtain a professional license, secure a contract with a governmental agency or other client, join a professional network or meet the conditions of a commercial loan.
- Cost: Annual E&O insurance premiums may range from $500 to $20,000 per year, depending on factors like your industry, size, policy details and claims history.
- Recommendations: Many businesses opt for a $1 million per-occurrence coverage limit and a $3 million aggregate limit for E&O coverage. Ultimately, your coverage needs may vary based on your industry, contractual requirements, asset value and risk tolerance.
How To Compare E&O Insurance Quotes for Your Business
When you are ready to shop for errors and omissions insurance coverage, comparing quotes from around three to five carriers is the best way to ensure you get the right policy at a competitive price. As you comparison shop, you’ll generally need to take the following steps:
- Gather your business information, including your industry, annual revenue, employee headcount and desired coverage limits
- Request quotes from multiple commercial insurance companies
- Compare the coverage limits, exclusions and deductibles of each policy — rather than focusing solely on the price
- Review the financial strength rating and claims handling reputation of each insurance carrier you consider
- Work with a licensed agent to clarify any policy terms you don’t understand before purchasing
Individually contacting multiple insurers to request quotes can be a tiresome process, but SmartFinancial helps make comparison shopping easy. Simply fill out our online questionnaire, and then we’ll connect you with an agent who can handle the comparison shopping process for you — sometimes in as little as a few minutes. Begin the process of comparing business insurance quotes at no cost today!
- Insurance quotes /
- Commercial /
- Errors And Omissions Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Commercial Insurance Quote.
More on Commercial Insurance

Looking for Commercial Insurance?
Compare rates from dozens of companies in less than 3 minutes.