
How To File a Car Insurance Claim in 6 Easy Steps
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
To file a claim on your auto insurance policy after an accident, you will generally need to exchange information with the other people involved in the crash, document the scene of the car accident, request a police report and submit all relevant evidence to your insurance company. After you file your car insurance claim, you may get an idea of what to expect from your settlement by paying attention to your policy details and obtaining a quote for the cost of repairs.
Read on to learn more about filing car insurance claims, including the types of information you’ll need to collect and what you should know about your auto insurance policy in advance.
|
Key Takeaways
|


What Is a Car Insurance Claim?
A car insurance claim is a formal request for payment from your insurance company for a loss covered by your car insurance policy. Whether you can file a claim for any given accident depends on the coverage types included in your policy. See the table below for an overview of some of the most common types of car insurance and what they cover.
|
Coverage Type |
Description |
Example |
|---|---|---|
|
Covers another person’s medical bills, lost wages and funeral expenses if you are the at-fault driver, plus legal fees if they sue you |
You hit a pedestrian with your car and break their leg |
|
|
Pays for repairs to another person’s car, home or belongings if you crash into them, plus repairs to any public property you crash into |
You run over your neighbor’s mailbox while backing out of your driveway |
|
|
Uninsured motorist (UM) |
Pays for your medical expenses and car repairs if you are hit by someone who doesn’t have car insurance or if you can’t identify the driver after a hit-and-run |
Someone without auto insurance runs a red light and crashes into the side of your car |
|
Underinsured motorist (UIM) |
Covers the difference if you are struck by a driver who doesn’t have enough insurance to fully pay for your medical expenses or car repairs |
A driver with $5,000 worth of property damage liability coverage deals $7,000 worth of damage to your car |
|
Personal injury protection (PIP) |
Covers your medical bills, lost wages and funeral expenses if you are at fault for the accident |
You get whiplash after crashing into another vehicle and need to take two weeks off work |
|
Medical payments (Medpay) |
Covers your medical bills and funeral expenses if you are at fault for the accident but doesn’t cover lost wages |
You are rushed to the emergency room after a car crash |
|
Collision |
Pays for repairs to your car after colliding with another vehicle or object, regardless of who is at fault |
You doze off at the wheel and crash into a nearby tree |
|
Pays for repairs to your car after unexpected external perils, like fire, hail, vandalism and theft |
A chunk of hail cracks your windshield |
How Do Car Insurance Claims Work?
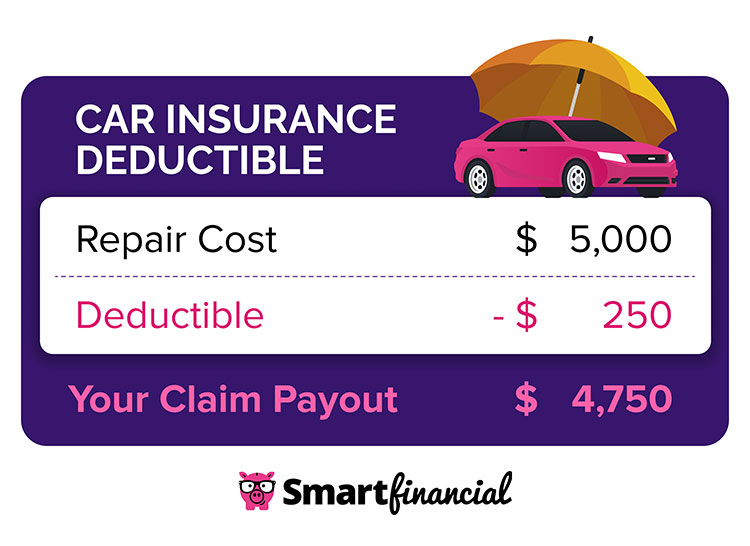
Depending on the type of loss you experience, your car insurance claim may require a deductible — this is the portion of the expenses you’re responsible for paying out of pocket. In general, your insurance company will automatically subtract the deductible amount from your insurance payout. For example, if you file a claim for $5,000 in damage and have a $250 deductible, your insurer would contribute $4,750 toward the claim.
You should note that not every type of car insurance claim requires a deductible. However, you can generally expect a deductible to be subtracted from your settlement if you file a claim on your personal injury protection, collision, comprehensive or uninsured motorist property damage coverage.[1]
How To File a Car Insurance Claim
The following sections outline the main steps you’ll need to take to file a claim with your auto insurance company.
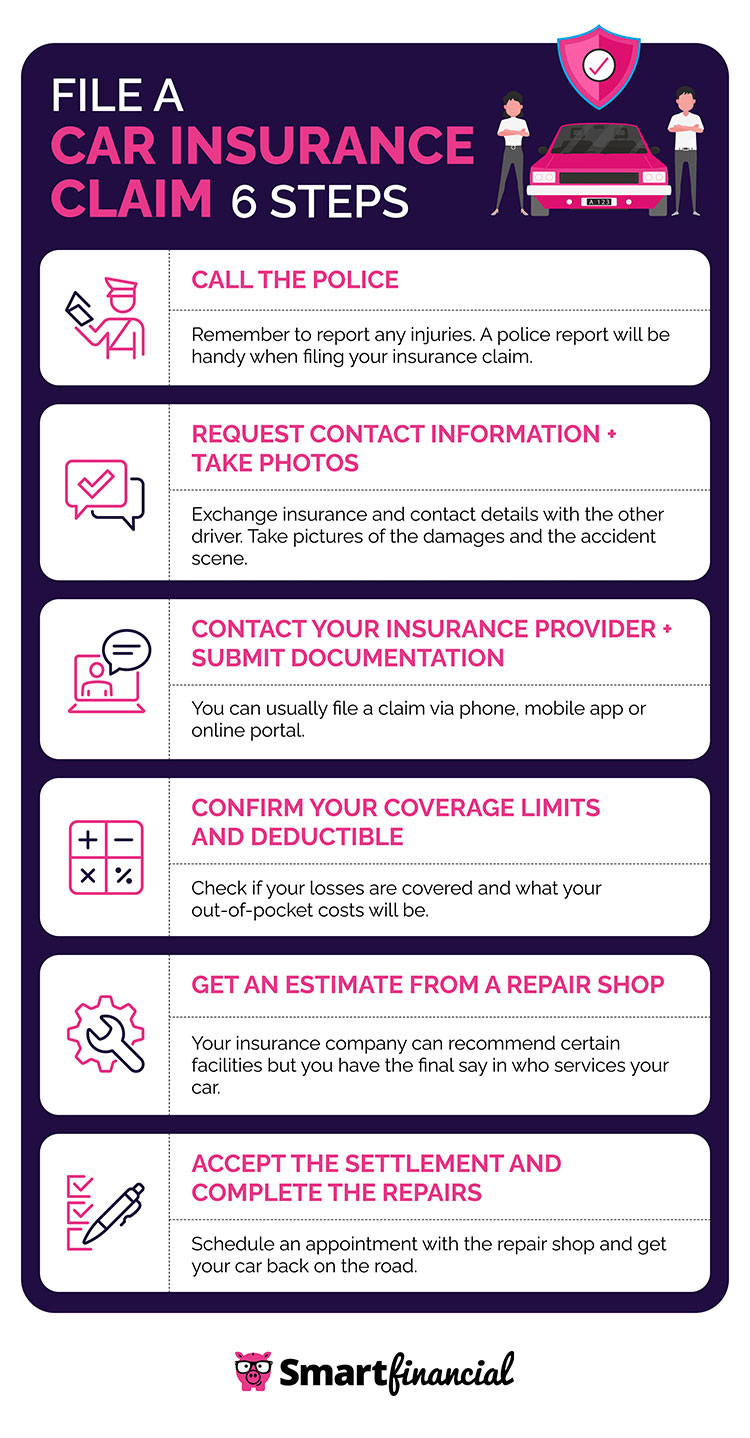
1. Call the Police
After a car accident, your first step should be to pull over to a safe area, check whether anyone involved is injured and call 911. Even if no one is injured in the collision, you should still contact emergency services so the responding officers can complete a police report, which may help when you file a claim.
2. Request Contact Information and Take Photos
Regardless of who is at fault for the collision, you should exchange the following information with the other driver:[2]
- Name
- Address
- Phone number
- License plate number
- Driver’s license number
- Insurance policy number and name of insurance company
You should also request the names and contact information of any other people who witnessed the crash, as they could support your insurance claim.[2] Do not admit fault when speaking with others at the scene, as doing so could jeopardize your ability to be compensated by the other driver’s insurer.
In addition, take pictures or videos of the damage to your vehicle as evidence for your claim. Be sure to document any scratches or dents on your car, along with other useful details, like skid marks on the road.
3. Contact Your Insurance Provider and Submit Documentation
Once you’ve collected the documents and information needed for your claim, you can initiate the process with your insurance provider — usually by phone, mobile app or online portal. You will generally be able to submit police reports, pictures or videos and important claims forms, and you may need to schedule an appointment with your insurance company’s adjuster.
If the other driver is at fault for the accident, you may be able to file a claim directly with their insurance company online or over the phone — as long as you collected their insurance information after the crash. If you’re unsure how to contact the other driver’s insurer, you may still be able to go through your own insurance company, which might pay your claim and then seek reimbursement from the other insurer through the process of subrogation.[3]
4. Confirm Your Coverage Limits and Deductible
While your claim is being processed, it’s helpful to review your policy details to understand what to expect from your insurance payout. For example, if you have a $15,000 uninsured motorist property damage coverage limit and a $500 deductible, your maximum payout after being struck by an uninsured driver would be $14,500. As a result, if your actual repair bill is $16,000, you should be prepared to pay $1,500 out of pocket.
Also, check which coverage types are included in your policy so you know what benefits are — or aren’t — available. For example, if you’re at fault for a collision and your policy doesn’t include rental car reimbursement coverage, you’ll have to pay out of pocket to rent a vehicle while your car is being repaired.
5. Get an Estimate From a Repair Shop
It can be helpful to contact a local auto shop for a repair estimate so you know how much you may need from your insurance carrier. While your insurer may recommend a specific repair shop, you’re generally free to choose the mechanic you prefer. However, if the shop you select charges more than the one your insurance company recommends, you may need to cover the difference out of pocket.[4]
6. Accept the Settlement and Complete the Repairs
You can use the payout from your insurance company to cover the cost of remedying your loss. If the insurer determines that the cost to fix your car exceeds its value, the vehicle will be considered totaled. In that case, your insurance carrier will pay you the actual cash value (ACV) of the lost vehicle, which you can put toward buying a new car.
If the car can be repaired, your insurance provider will pay the settlement to either you or the repair shop handling the work.[5] In the latter case, you may still need to pay your deductible to the mechanic to ensure they’re fully compensated.
When Should I File a Car Insurance Claim?
As a general rule, you should file a car insurance claim as soon as possible after an accident to ensure timely reimbursement and avoid missing any deadlines. That said, if the damage to your vehicle seems minor, you may want to visit a repair shop for a quote before contacting your insurance company — depending on the type of claim you'd file.
For example, suppose you rear-end another vehicle, resulting in significant damage to your front bumper but leaving the rest of your car unscathed. If a mechanic tells you that it will cost $800 to replace the bumper but you have a $1,000 collision insurance deductible, filing a collision claim wouldn’t make financial sense — you’d simply need to pay out of pocket.
How Long Do I Have To File a Car Insurance Claim?
You can usually file a property damage claim up to six months after a covered accident, and you may have even more time depending on your state and insurance policy.[6] However, it’s best to file your claim as soon as possible, since tracking down witnesses and collecting evidence may become more difficult over time.
- Insurance quotes /
- Auto /
- Filing A Car Insurance Claim
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Auto Insurance Quote Online Now.
More on Auto Insurance
Looking for Auto Insurance?
Compare rates from dozens of companies in less than 3 minutes.