

What Is Uninsured Motorist Coverage?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Uninsured motorist coverage — or UM — is a type of car insurance that can cover medical expenses and property repairs if you are struck by a driver who doesn’t have auto insurance. This coverage type is mandatory for drivers in several states, and it is often sold alongside underinsured motorist coverage — or UIM — which steps in after an accident involving a driver who doesn’t have enough insurance to cover your medical or repair costs.
Read below to find out more about uninsured motorist insurance coverage, including what situations it covers and why it may be worth adding to your car insurance policy.
|
Key Takeaways
|
On This Page

How Does Uninsured Motorist Coverage Work?
What Types of Uninsured Motorist Coverage Are There?
How Much Does Uninsured Motorist Coverage Cost?
Is Uninsured Motorist Coverage Required?
What Happens if You Don’t Have Uninsured Motorist Coverage?
Is Underinsured Motorist Coverage the Same as Uninsured Coverage?
How To File an Uninsured Motorist Claim
FAQs

How Does Uninsured Motorist Coverage Work?
If you are injured or your vehicle is damaged in a car crash, the at-fault driver’s liability insurance will normally take care of your medical treatments or repair bills. However, if the at-fault driver was driving without car insurance, then your uninsured motorist coverage can step in to cover these expenses instead. Uninsured motorist insurance may also cover you if you are the victim of a hit-and-run.[1]
In some states, you can stack your UM coverage, enabling you to multiply your coverage limits by the number of vehicles covered by your auto insurance policy.[1] For example, if your UM insurance provides up to $15,000 for property repairs and you have three cars listed on the same policy, then you may be able to claim up to $45,000 for damage inflicted on one vehicle in a single accident by stacking your coverage.
What Types of Uninsured Motorist Coverage Are There?
There are two main subsets of uninsured motorist coverage: uninsured motorist bodily injury coverage — or UMBI — and uninsured motorist property damage coverage — or UMPD.
Uninsured Motorist Bodily Injury
UMBI insurance can cover medical treatments, lost wages, pain and suffering damages and death benefits if you or your passengers are injured or killed in a car accident caused by an uninsured driver. Coverage may also apply when you are a pedestrian, like if someone without car insurance drives up on a sidewalk and hits you.[2] Whenever you file a claim on your UMBI coverage, you generally won’t have to pay a deductible.[3]
Uninsured Motorist Property Damage
If your vehicle is struck by a driver who doesn’t have property damage liability coverage, UMPD insurance can take effect to pay for your car repairs. Your UMPD coverage may also extend to other types of property damage caused by an uninsured driver, including damage to your home.[4] Unlike UMBI claims, UMPD claims usually require you to pay a deductible.[3]
Some insurers offer an alternative uninsured motorist property damage product known as a collision deductible waiver. If you opt for a CDW, then you will have to file a claim on your collision insurance policy if you get into an accident with an uninsured driver. However, the CDW will take care of your collision insurance deductible, so you won’t have any direct out-of-pocket costs associated with the claim.[5]
How Much Does Uninsured Motorist Coverage Cost?
The average cost of uninsured motorist coverage is $67 per year.[6] Keep in mind that you may have to pay more for coverage if you live in an area with a high number of uninsured drivers, since there is a greater chance that you will need to file an uninsured motorist claim. For example, the uninsured driver rate was nearly five times higher in Mississippi than in Maine in 2023, meaning Mississippi drivers can likely expect much higher premiums.[7]
Is Uninsured Motorist Coverage Required?
UMBI coverage is required by law in several states, and some states also require UMPD coverage. See the table below for a breakdown of how much uninsured motorist coverage drivers must carry, depending on the state.[8]
|
State/District |
Minimum UMBI Coverage Limits |
Minimum UMPD Coverage Limit |
|---|---|---|
|
Connecticut |
$25,000 per person $50,000 per accident |
N/A |
|
District of Columbia |
$25,000 per person $50,000 per accident |
$5,000 |
|
Illinois |
$25,000 per person $50,000 per accident |
N/A |
|
Kansas |
$25,000 per person $50,000 per accident |
N/A |
|
Maine |
$50,000 per person $100,000 per accident |
N/A |
|
Maryland |
$30,000 per person $60,000 per accident |
$15,000 |
|
Massachusetts |
$25,000 per person $50,000 per accident |
N/A |
|
Minnesota |
$25,000 per person $50,000 per accident |
N/A |
|
Missouri |
$25,000 per person $50,000 per accident |
N/A |
|
Nebraska |
$25,000 per person $50,000 per accident |
N/A |
|
New Jersey |
$35,000 per person $70,000 per accident |
$25,000 |
|
New York |
$25,000 per person $50,000 per accident |
N/A |
|
North Carolina |
$50,000 per person $100,000 per accident |
$25,000 |
|
North Dakota |
$25,000 per person $50,000 per accident |
N/A |
|
Oregon |
$25,000 per person $50,000 per accident |
N/A |
|
South Carolina |
$25,000 per person $50,000 per accident |
$25,000 |
|
South Dakota |
$25,000 per person $50,000 per accident |
N/A |
|
Vermont |
$50,000 per person $100,000 per accident |
$10,000 |
|
West Virginia |
$25,000 per person $50,000 per accident |
$25,000 |
|
Wisconsin |
$25,000 per person $50,000 per accident |
N/A |
Although car insurance is optional in New Hampshire, anyone who does opt to purchase coverage must buy a policy with UM insurance.[9] Meanwhile, you can only go without UM coverage in Rhode Island if your policy comes with the minimum bodily injury liability coverage limit.[10] In Indiana and Virginia, UM coverage is automatically included in standard policies, but you can choose to decline it.[11][12]

What Happens if You Don’t Have Uninsured Motorist Coverage?
Forgoing uninsured motorist coverage is against the law in several states, meaning you could face license suspension, fines or potentially even imprisonment if you are caught driving without adequate coverage. In states where UM coverage is optional, your property repairs or medical expenses may instead be covered by your collision insurance, personal injury protection or medical payments coverage, depending on the situation.
However, if you don’t have any of these coverage types, you could be totally on the hook for your own expenses after an accident — even if you weren’t responsible for it. Alternatively, you could have to take the at-fault driver to court and wait for a lengthy legal process to be resolved before being reimbursed. Given the high rate of uninsured drivers in the United States, it may be prudent to maintain UM coverage with sufficient coverage limits.
Is Underinsured Motorist Coverage the Same as Uninsured Coverage?
Underinsured motorist coverage is not necessarily the same as uninsured motorist coverage, though the two coverage types have similar functions and are often sold together. In some states, uninsured coverage may automatically include underinsured coverage. The following states require drivers to carry both UM and UIM insurance:[8]
- Connecticut
- Kansas
- Maine
- Maryland
- Minnesota
- Nebraska
- New Jersey
- North Carolina
- North Dakota
- Oregon
- South Dakota
- Vermont
Just like UM coverage, UIM coverage is required for anyone who decides to purchase car insurance in New Hampshire, and it can be rejected by drivers with minimum coverage in Rhode Island or by any driver in Indiana and Virginia.[9][10][11][12] In addition, auto insurance policies in Illinois must include underinsured motorist coverage if the policy’s UMBI limit exceeds the state-mandated minimum.[13]
What Is Underinsured Motorist Coverage?
Underinsured motorist coverage protects you in case you are struck by a driver who has auto liability insurance but doesn’t have high enough coverage limits to fully cover your expenses. Like uninsured motorist coverage, your UIM policy may provide coverage for both bodily injury and property damage claims, depending on your state.
UIM coverage is important because state-mandated liability coverage limits are fairly low. Experts often recommend buying $100,000 worth of bodily injury liability coverage per person involved in an accident, $300,000 worth of bodily injury coverage to split across all people injured in an accident and $100,000 worth of property damage liability coverage — which is four to six times more than the most common mandatory minimum limits.[14]
How Does Underinsured Motorist Coverage Work?
Some UIM policies won’t pay out up to your coverage limit after a covered claim, instead paying out the difference between your UIM coverage limit and the at-fault driver’s liability coverage limit.[13] For example, if you have $50,000 worth of UIM bodily injury coverage per person and are struck by someone with $30,000 worth of bodily injury liability coverage per person, your insurer may contribute up to $20,000 toward your medical expenses.
How To File an Uninsured Motorist Claim
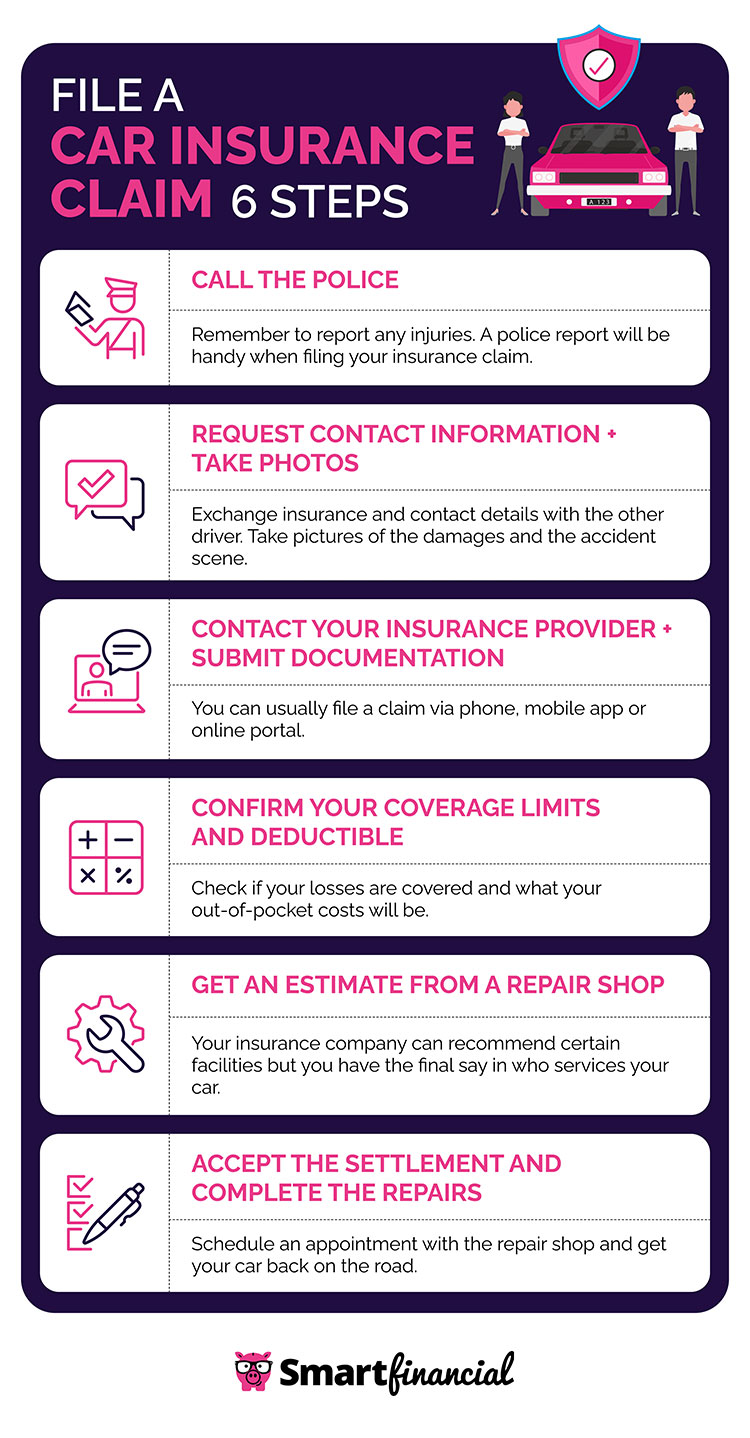
If you get into a car accident with a driver who has little or no auto insurance, take the following steps to file a car insurance claim on your underinsured or uninsured motorist policy:
- Pull over to a safe area, and call 911 so first responders can tend to anyone who is injured and police officers can fill out a police report.
- Take pictures of the damaged parts of your vehicle, and talk to the at-fault driver to exchange contact information and determine whether they have any liability insurance.
- Submit photos, police reports and other relevant documentation to your car insurance company.
- Make sure you know what your coverage limits are and whether the claim will require a deductible so you can get an idea of how much money to expect from your insurance settlement.
- If you are filing a property damage claim, contact a mechanic to get an estimate for the cost of repairs.
- Use your insurance payout to cover your medical expenses and repair costs, or contest the settlement if you believe it is too low.
- Insurance quotes /
- Auto /
- Uninsured Motorist Coverage
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Auto Insurance Quote Online Now.
More on Auto Insurance

Looking for Auto Insurance?
Compare rates from dozens of companies in less than 3 minutes.