

Collision Insurance: Do You Need It?
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
While collision insurance isn’t required by state laws like some other forms of car insurance, you may still need it if you’re financing or leasing your vehicle. Even if you’ve paid off your car, collision insurance can still benefit you by covering the costs of repairing or replacing your vehicle after it’s damaged in a car accident.
Keep reading to learn how collision insurance works, what it covers, expected costs and how to get this coverage.
|
Key Takeaways
|


What Is Collision Insurance?
Collision insurance is a type of car insurance that covers your vehicle if it is damaged or suffers a total loss after physically striking another car or object. Collision insurance is available for multiple types of vehicles, including cars, motorcycles, boats and RVs.
Is Collision Insurance Required?
Collision insurance is not a legal requirement in any state. However, if you finance your car purchase or lease the vehicle you drive, your lender or lessor will likely require you to maintain collision and comprehensive coverage until you fully repay the car loan or terminate the lease, respectively. You can typically drop collision coverage without legal ramifications after repaying your loan or ending your lease.
How Does Collision Insurance Work?
You’ll want to file a claim with your collision insurance company after your car is damaged, whether by a hit-and-run or in an accident. Submit photos of the damage to your car with your claim to ensure a quicker verification from your insurer. The insurance carrier may ask for an estimate of repair costs from a mechanic, either one it recommends or one of your choosing.
Deductibles
Collision coverage claims are subject to a deductible that you must pay out of pocket before your insurance company covers the remaining balance up to your policy limit, which should be set at the actual cash value (ACV) of your car.[1] For example, suppose your car repair bill totals $5,000 after a covered collision, and you have a $250 deductible. After you pay the $250 deductible, your auto insurance company will cover the remaining $4,750.

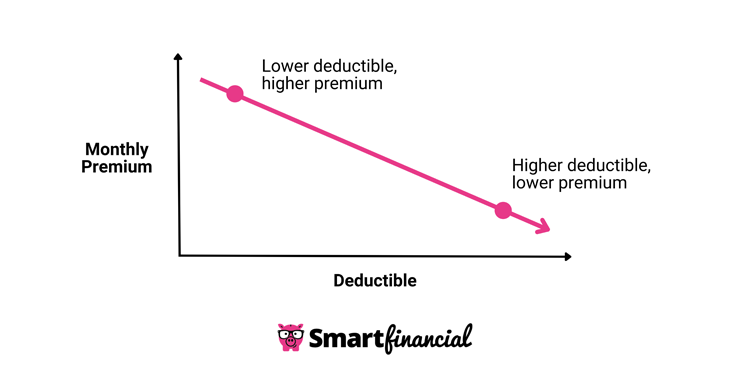
Your collision deductible amount can affect your monthly premium because you will be shouldering more of the costs after a covered car accident with a higher deductible. Therefore, a higher deductible can result in a lower monthly premium. Conversely, a lower deductible can increase your monthly premium because you transfer that financial responsibility to the insurance company.
If your insurance company pays out your claim directly to the repair shop, you may be required to pay the deductible to the mechanic before the repairs are completed. Additionally, deductibles are typically separate for different policies, so you could select a higher deductible for your comprehensive coverage than for your collision coverage or vice versa if you think you are more likely to file a claim on one policy than the other.
When You’re Not At Fault
When you’re not at fault for a collision, such as a fender bender caused by another person driving into the back of your car, your options may differ depending on whether the other driver has liability insurance and high enough limits on that coverage. If they do, you can typically file a liability claim with the at-fault driver’s insurance company instead of filing a claim on your own collision coverage.
If the at-fault driver has little to no liability coverage and you lack uninsured and underinsured motorist coverage, then you can file a claim on your collision insurance to cover your property repairs. However, collision coverage will not pay for your medical expenses if you or your passengers sustained injuries, and these are instead covered by medical payments coverage (Medpay) or personal injury protection (PIP).
Meanwhile, if another driver flees the scene after hitting your car, collision insurance should cover your car repairs. Since collision coverage pays for your losses regardless of who is at fault, you will not need to track down the driver who hit you. That said, in the event that you do find the at-fault driver, you may be able to recover your deductible.[2]
What Does Collision Insurance Cover?
Collision insurance helps cover the costs to repair or replace your vehicle when it is damaged by:[1]
- Accidents with other vehicles (e.g., cars, trucks, motorcycles or RVs)
- Collisions with stationary objects (e.g., guardrails, telephone poles, garages, mailboxes or houses)
- Single-vehicle rollovers
What Isn’t Covered?
Collision insurance does not cover other people’s expenses after an accident you are liable for, nor does it cover medical expenses in any situation. Additionally, it excludes coverage for physical losses unrelated to a collision, including the following:[3]
- Vandalism
- Theft
- Floods
- Fire
- Striking an animal on the road
Who Needs Collision Insurance?
Below, we’ll cover a few examples of situations where you may want to consider purchasing a collision insurance policy:
- You have an outstanding car loan: If you’re financing or leasing your car, your lender will likely require you to maintain collision coverage until you fully repay the loan. Collision coverage is optional if you fully paid for the car out of pocket or repaid your loan.
- Your car has a high fair market value: If your car is brand new or still worth a lot after several years, maintaining collision coverage may be worth the cost. Collision coverage will cover costly repairs or pay you up to your policy’s maximum limits if your car is totaled in a car accident.
- You’re unable to pay repair costs out of pocket: Car repairs can be costly, and if you’re unable to pay for repairs out-of-pocket, collision car insurance can offer some financial relief. Unless you have an adequate savings account for emergencies, you should consider purchasing collision insurance to restore your car to drivable condition after an accident.
How Much Does Collision Insurance Cost?
The average cost to add collision coverage to your auto insurance policy is $400.15 per year as of 2022, but actual costs can vary depending on factors like your insurer, region, vehicle type and more. For example, the state with the lowest average premium for collision coverage is South Dakota ($272.05), while California ($534.22) has the highest average premium among states.[4]
Below, we’ll cover the average cost of collision insurance for each state and the District of Columbia.[4]
| State/District | Average Annual Premium |
|---|---|
| $397.21 | |
| $415.28 | |
| $355.65 | |
| $390.78 | |
| $534.22 | |
| $361.09 | |
| $424.27 | |
| $365.21 | |
| $586.01 | |
| $371.15 | |
| $417.22 | |
| $390.93 | |
| $283.24 | |
| $383.95 | |
| $306.47 | |
| $277.94 | |
| $301.79 | |
| $304.28 | |
| $471.27 | |
| $301.41 | |
| $450.22 | |
| $445.31 | |
| $479.62 | |
| $305.78 | |
| $384.30 | |
| $344.41 | |
| $310.12 | |
| $308.99 | |
| $372.25 | |
| $336.31 | |
| $441.78 | |
| $350.40 | |
| $486.05 | |
| $385.88 | |
| $283.23 | |
| $315.44 | |
| $367.49 | |
| $291.87 | |
| $394.08 | |
| $488.28 | |
| $334.21 | |
| $272.05 | |
| $379.45 | |
| $456.10 | |
| $328.40 | |
| $339.61 | |
| $350.71 | |
| $327.26 | |
| $354.05 | |
| $272.15 | |
| $303.06 |
How To Get Collision Insurance
Since each company may use a different underwriting technique to determine your premium or offer varying discounts, you’ll want to get quotes from at least three to five insurers. You’ll typically need to inform each insurance company about the value of your car, your driving history and other factors used to calculate your rates. Keep in mind that this process may become time consuming and tedious, as you’ll typically need to gather quotes from each insurer one by one, often providing the same information each time.
Speed up this process by using an insurance marketplace like SmartFinancial. After answering a brief questionnaire, we can connect you with a licensed insurance agent to help you find the coverage you need. Click here for a free auto insurance quote today!
- Insurance quotes /
- Auto /
- What Is Collision Insurance
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Auto Insurance Quote Online Now.
More on Auto Insurance

Looking for Auto Insurance?
Compare rates from dozens of companies in less than 3 minutes.