

Do I Need Full Coverage Car Insurance?
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Full coverage car insurance combines comprehensive and collision insurance with other coverage types required in your state. It isn’t typically required unless you’re leasing your vehicle or paying off an auto loan. Even if you’ve fully paid off your car, full coverage may protect you from out-of-pocket expenses caused by collision-based accidents or damage from unexpected perils.
Keep reading to learn what a full coverage car insurance policy protects you against and when it’s required.
|
Key Takeaways
|


What Is Full Coverage Car Insurance?
Full coverage typically combines required auto insurance policies — including liability coverage and potentially other coverage types, depending on your state — with comprehensive and collision insurance. Rather than being a specific policy, full coverage merely describes having all of these different policies together. Essentially, you are “fully covered” by a policy that meets your state’s legal requirements and covers the most common situations where your car could be damaged.
Is Full Coverage Car Insurance Required?
While full coverage will include insurance policies that are required by law, comprehensive and collision insurance aren’t typically required. These two coverage options can help protect you if you damage your car by striking another vehicle or stationary object or if it is damaged by an external peril, like a falling tree. Still, these coverages may not be necessary for every driver.
Is It Required for Leased Vehicles?
Lessors typically require you to have both comprehensive and collision coverage on a leased vehicle, as it helps protect their investment in your car in case it is damaged in an accident, vandalized or stolen. Similarly, lenders will usually require you to purchase these coverage types if you need to finance your vehicle purchase.
Keep in mind that, if you don’t purchase the required insurance coverage, your lender may purchase a policy on your behalf and bill you for it.[1] The policy your lender decides upon may be more expensive than one you’d pick for yourself, so it’s important to discuss necessary coverages with your lender to avoid overpaying.
How Does Full Coverage Car Insurance Work?
If you have full coverage car insurance and your vehicle is totaled or stolen, your insurance company will pay you the car’s actual cash value (ACV) minus your deductible. The ACV is the value of your car when considering depreciation factors, like age or wear and tear.
You may be able to upgrade your policy to receive the replacement cost value (RCV) instead, but you will have to pay a higher premium to do so. The RCV doesn’t consider depreciation factors, meaning your payout would simply be the cost of buying a vehicle similar to the one you lost.
Your deductible is the amount you must pay out of pocket before your insurance company will give any money toward covered losses. For example, if you have a $500 deductible for collision coverage and cause $5,000 worth of damage to your car in an accident, your insurance company would contribute $4,500.

What Does Full Coverage Car Insurance Cover?
There is no universal definition for full coverage, but full coverage policies typically include comprehensive and collision coverage plus the minimum requirements for your state. As a result, these policies can usually pay for medical bills and car repairs for yourself and others after several types of incidents. Depending on where you live, a full coverage policy might include the following state-mandated types of car insurance:[2]
|
Coverage Type |
Description |
Example |
Where It’s Required |
|---|---|---|---|
|
Pays for another person’s medical bills, lost wages and funeral expenses if you are the at-fault driver, plus legal fees if they sue you |
You hit a pedestrian with your car and break their leg |
All states but FL and NH |
|
|
Pays for repairs to another person’s car, home or belongings if you crash into them, plus repairs to any public property you crash into |
You run over your neighbor’s mailbox while backing out of your driveway |
All states but NH |
|
|
Uninsured motorist (UM) |
Pays for your medical expenses and car repairs if you are hit by someone who doesn’t have car insurance or if you can’t identify the driver after a hit-and-run |
Someone without auto insurance runs a red light and crashes into the side of your car |
CT, DC, IL, KS, ME, MD, MA, MN, MO, NE, NJ, NY, NC, ND, OR, SC, SD, VT, WV and WI |
|
Underinsured motorist (UIM) |
Covers the difference if you are struck by a driver who doesn’t have enough insurance to fully pay for your medical expenses or car repairs |
A driver with $5,000 worth of property damage liability coverage deals $7,000 worth of damage to your car |
CT, KS, ME, MD, MN, NE, NJ, ND, OR, SD and VT |
|
Personal injury protection (PIP) |
Pays for your medical bills, lost wages and funeral expenses if you are at fault for the accident |
You get whiplash after crashing into another vehicle and need to take two weeks off work |
DE, FL, HI, KS, KY, MA, MI, MN, NJ, NY, ND, OR, PA and UT |
|
Medical payments (Medpay) |
Pays for your medical bills and funeral expenses if you are at fault for the accident but doesn’t cover lost wages |
You are rushed to the emergency room after a car crash |
ME |
|
Property protection insurance (PPI) |
Pays for repairs to another person’s property if you crash into it (does not include moving vehicles or those that have been parked improperly) |
You accidentally back into another vehicle in a grocery store parking lot and knock off its front bumper |
MI |
In addition, full coverage generally includes both types of physical damage coverage:
|
Coverage Type |
Description |
Example |
|---|---|---|
| Collision | Pays for repairs to your vehicle regardless of who is at fault for the accident | You miss a stop sign and drive into another car or crash into a highway guardrail |
| Comprehensive | Pays for repairs to your car after unexpected perils, like fire, hail, vandalism and theft | An intruder steals your car battery and damages other components of your vehicle in the process |

What Isn’t Covered?
Even if you have full coverage, your insurance company won’t cover everything that could go wrong with your vehicle. Common car insurance exclusions include:
- Intentional damages: Purposefully damaging your car to collect an insurance payout is considered fraud and could result in the cancellation of your policy.
- Losses exceeding policy limits: Car insurance policies limit the total amount of money you can receive for a covered loss. For example, if you have a $25,000 limit for your property damage liability coverage and cause $30,000 worth of damage in an accident, then you would have to pay your deductible plus the last $5,000 out of pocket.
- Outstanding loans: If your car gets totaled and is worth less than the outstanding balance on your loan, then you will have to cover the difference out of pocket unless you have purchased gap insurance.
- Rental cars: Unless you add a rental car reimbursement endorsement, your full coverage policy likely won’t pay for you to rent a car while your main vehicle is being repaired.
- Stolen personal property: Your car insurance won’t cover items stolen from your car, although your homeowners insurance most likely will.
- Routine maintenance: You will have to pay out of pocket for general maintenance costs, such as getting your oil changed or your tires rotated.
- Roadside assistance: If your car breaks down, your insurance typically will not cover tows, jumpstarts, locksmithing services or fuel delivery unless you have added a roadside assistance plan.
- Commercial use: Your personal car insurance policy may not cover damage from an accident if you were using your car for a business purpose. For example, you may need to purchase separate rideshare insurance if you work for a company like Uber or Lyft.
- Dangerous activities: Your policy might not cover damage that occurs during high-risk activities, like racing or off-roading.
How Much Does Full Coverage Car Insurance Cost?
The average cost of full coverage car insurance for all vehicles nationwide is $2,678 per year, as of March 2025. In contrast, the average cost of a policy that only includes the minimum amount of coverage required by law in your state is $799 per year.[3] Of course, your exact costs will vary based on different factors, including your vehicle model, driving record, vehicle use and more.
Where you live can also factor into your premium costs, as some insurance policies may be more expensive in some regions than in others, even for the exact same coverage. For example, the annual average cost of a full coverage policy in Idaho is $1,473, but Florida drivers pay a much higher annual average of $4,210.[3]
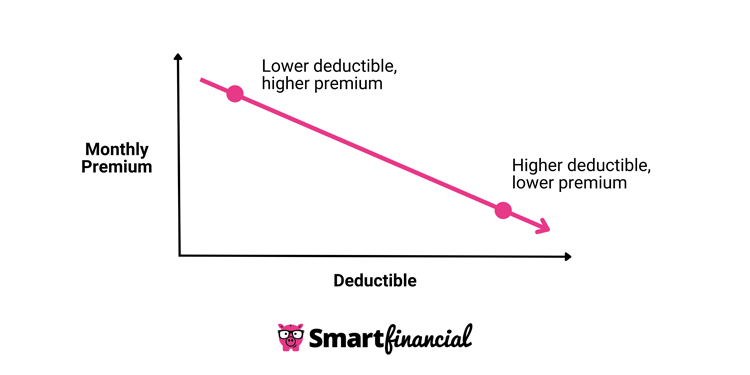
What you choose for your deductible may also affect your premiums. Generally, lower deductibles result in a higher premium because you’re offloading more of the financial responsibility to your insurer when you file a claim. Ensure you don’t select a deductible higher than you can afford, even if it helps lower your premium, as this could leave you financially burdened if you get into an accident.
How To Get Full Coverage Car Insurance
Getting full coverage auto insurance will likely require shopping around to get the best deal. Obtain quotes from three to five different insurance companies for the various policies your state requires, alongside collision and comprehensive coverages. You’ll typically need to provide information about your car, your personal details and your driving history for each insurer to give you a rate.
Giving the same information over and over can become tedious and time consuming if you contact each carrier one by one, but you can help speed up the process by using an insurance marketplace like SmartFinancial. After you answer a few questions, we can connect you with a licensed insurance agent to help you get the necessary coverages. Click here for a free auto insurance quote today!
- Insurance quotes /
- Auto /
- Full Coverage Car Insurance
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Auto Insurance Quote Online Now.
More on Auto Insurance

Looking for Auto Insurance?
Compare rates from dozens of companies in less than 3 minutes.