

How Do I Save Money On Car Insurance?
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
There are several ways you can save money on car insurance, from adjusting your driving habits to searching for discounts at different insurance companies. Since car insurance is required by law in almost every state, it is essential to find a policy that provides the best value for your specific circumstances and budget.
Read on to learn tips that can help you save money on car insurance.
|
Key Takeaways
|
On This Page

1. Make Sure Your Information Is Updated and Accurate
2. Ask Insurance Carriers About Discounts
3. Drop Coverage You Don't Need
4. Work on Your Credit Score
5. Increase Your Car Insurance Deductibles
6. Review Your Policy Annually
7. Bundle Policies
8. Consider Multi-Vehicle Discounts
9. Opt for Low-Mileage or Usage-Based Insurance
10. Select Car Models With Cheap Insurance Rates
11. Keep Your Car Stored in a Safe Area
12. Complete a Defensive Driving Course
13. Shop Around
FAQs

1. Make Sure Your Information Is Updated and Accurate
Giving your insurance provider up-to-date information about your driving habits can also help you save money on car insurance. For example, if you previously had to commute to work, you should let your insurance company know if you accept a remote job. Driving less means you’re less likely to get into an accident, and your insurer may lower your rate as a result.
It’s crucial to provide your insurer with accurate information about the negative things, too. For example, failing to inform your insurer of an accident may constitute fraud. If you are caught withholding information or lying to your insurance company, your policy could be canceled and you could experience a lapse in coverage.
2. Ask Insurance Carriers About Discounts
An insurance company may offer you a discounted rate for several reasons. For example, GEICO offers a clean driving record discount that can save you up to 22% on your car insurance premium if you go one year without getting into a car accident.[1] Meanwhile, many insurers offer discounted rates to good students with a GPA of 3.0 or higher.
In addition, your insurance company is required to offer you a discount, typically between 15% and 20%, for installing an anti-theft device if you live in one of the following states:[2]
- Florida
- Illinois
- Kentucky
- Louisiana
- Massachusetts
- Minnesota
- New Mexico
- New York
- Pennsylvania
- Rhode Island
- Texas
- Washington

3. Drop Coverage You Don't Need
You can save money on your car insurance by dropping optional coverage types. While your lender will likely require you to have comprehensive and collision coverage if you are paying off your car, you are free to remove them from your policy once you have finished paying off your car.
When deciding whether to keep these coverage types, you should consider whether the potential payout after a total loss is worth the cost of your regular payments. If the cost of maintaining comprehensive and collision coverage exceeds 10 times your car's value, it may be time to drop them.[3]
4. Work on Your Credit Score
In most states, improving your credit score could help you save on car insurance. Some companies will calculate your premium using a credit-based insurance score. As a result, fully paying off your credit card debt each month and consistently making mortgage payments on time could lead to lower car insurance premiums.
However, the use of credit-based insurance scores is restricted in a few states. If you live in California, Hawaii, Maryland or Massachusetts, you likely don’t have to worry about your credit history impacting the cost of your car insurance.[4]
5. Increase Your Car Insurance Deductibles
Your car insurance premium will go down if you raise your deductible because your insurance company will be responsible for paying less whenever you make a claim. Your deductible is the amount you agree to pay toward a covered loss before your insurance company starts contributing.
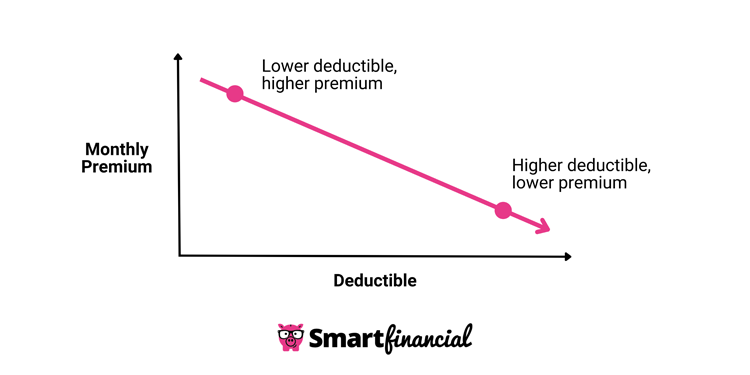
For example, if you have a $500 deductible for collision coverage and you cause $2,000 worth of damage to someone else’s car in an accident, your insurance company would pay $1,500. While liability insurance does not have a deductible, coverage types such as comprehensive and collision do. As a result, you could save money on your premiums if you can afford to pay more upfront anytime you need to file an insurance claim.
6. Review Your Policy Annually
You should review your policy annually to see if there are opportunities to save money on your car insurance. In general, cars become cheaper to insure over time as they age and become less valuable. You can use an online resource like Kelley Blue Book to estimate the value of your car and determine if you should be paying less for auto insurance.[5]
7. Bundle Policies
Many insurance companies offer discounted rates when you purchase multiple insurance products. For example, bundling your home, auto and life insurance policies may result in you paying less than if you purchased all three individually.
8. Consider Multi-Vehicle Discounts
Insurance companies usually offer discounts if you insure multiple vehicles under one policy. This applies if you add all your immediate family members’ cars to one policy, or if you simply add a second vehicle you personally drive. All the cars on a multi-vehicle policy generally have to be kept at the same address, although your insurer will likely still cover your child’s car even if they are away at college.
9. Opt for Low-Mileage or Usage-Based Insurance
If you drive your car infrequently, you may be eligible for usage-based car insurance, also known as black-box or telematics insurance. When you sign up for a usage-based insurance policy, you will have to attach a device to your car or download a mobile app that records your driving data, like how often you drive and how long your typical commutes are. Your insurer will then use that data to either adjust your premium directly or calculate your discount amount.
For example, Nationwide’s SmartMiles program charges drivers a base rate that stays consistent from month to month and a variable rate that changes based on the number of miles they drove over the past month.[6] To improve your odds of qualifying for low-mileage insurance, you could consider carpooling to work or using public transportation more frequently.
Be careful if you’re enrolled in a telematics or usage-based insurance program. While safe driving behaviors can lead to lower premiums, reckless driving can result in higher premiums
10. Select Car Models With Cheap Insurance Rates
The age and model of your car significantly impact the cost of your auto insurance. Newer cars may earn you a discounted rate if they have built-in safety features. At the same time, a car with high-end technology is more expensive to repair, so it is more likely that your insurance company will declare it a total loss after an accident.
Conversely, older cars are generally cheaper to insure since the cost of reimbursing you after a total loss is much lower for your insurance company. If you need a car and want the cheapest insurance possible, it may be better to buy a used car than a brand-new one. In addition, if you can afford to pay for the vehicle upfront, you can forego comprehensive and collision coverage, allowing you to save even more money on insurance.
11. Keep Your Car Stored in a Safe Area
Parking your car in a place where it is unlikely to be stolen or broken into can save you money on comprehensive coverage, since it decreases the odds that you will have to file a theft or vandalism claim. While you may not be able to easily change where you live, installing a locked garage to park your car may lower your auto insurance premiums.
12. Complete a Defensive Driving Course
Some insurance companies will offer you a discount on your car insurance premium if you complete a defensive driving course. Even without considering potential discounts, a defensive driving course could teach you techniques for preventing costly accidents and help you avoid filing an insurance claim that would raise your rates.
The availability of defensive driving discounts typically depends on the state you live in and, in many cases, your age. For example, Farmers only offers defensive driving discounts to people age 55 and older.[7]
13. Shop Around
Shopping around can help you find the best car insurance rate, as many insurers offer different rates for the same level of coverage. Every insurance company uses its own formula to calculate the risk of insuring any given driver and may weigh certain factors differently.
As a result, it’s essential to comparison shop to find the insurance company that can provide the most favorable rate for you. For example, one insurance company could offer the lowest rates to safe drivers, while another could offer the lowest rates to high-risk drivers.
You can use an insurance marketplace like SmartFinancial to discover the insurance policy that best suits your situation without going through the trouble of contacting multiple insurance companies individually.
- Insurance quotes /
- Auto /
- How To Save Money Auto Insurance Policy
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Auto Insurance Quote Online Now.
More on Auto Insurance

Looking for Auto Insurance?
Compare rates from dozens of companies in less than 3 minutes.