

Will My Insurance Policy Cover Me if My Car Is Broken Into? It Can, Learn How To Check
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Your car insurance covers theft as long as your policy includes comprehensive coverage. Otherwise, you’ll have to pay for a replacement vehicle out of pocket if the police cannot recover your stolen car. Also, car insurance doesn’t cover items that are stolen from your car, but a standard homeowners or renters insurance policy typically does.
Read below to learn how auto insurance helps with theft or related incidents and what you should do if your car is stolen.
|
Key Takeaways
|


How Does Car Insurance Cover Theft?
While insurance companies generally cover car theft, not all associated losses will be covered by your car insurance policy. For complete coverage, you may need to purchase endorsements for your auto insurance policy or other standalone coverage types. Check out the following sections for an overview of the different coverages that can step in when you are the victim of car theft.

Stolen Vehicles
Comprehensive insurance is a car insurance coverage type that covers losses caused by sudden, external perils, including theft. This coverage also applies if an intruder steals a specific part of your car or damages it in the process of breaking into it.[1] For example, comprehensive coverage could help you pay to repair or replace a broken window or a stolen catalytic converter.
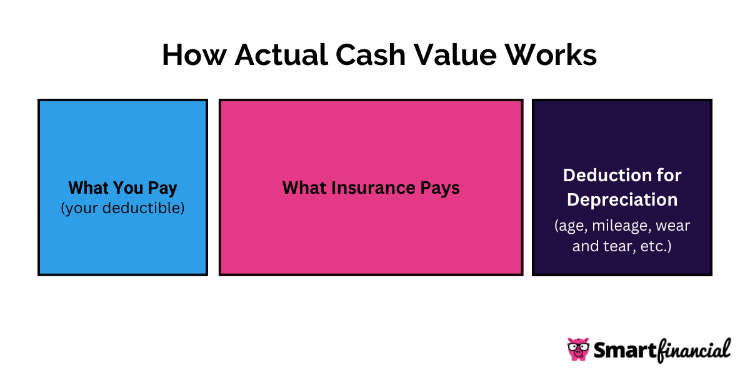
If your car is stolen and the police are unable to recover it, your insurance company will generally reimburse you at the car’s actual cash value — minus your deductible. ACV takes depreciation factors — like age or wear and tear — into account, meaning your insurance payout may not be enough to fully cover the cost of a new car. However, a full replacement may be covered if you purchase optional new car replacement insurance.
Car Modifications, Add-Ons or Upgrades
When calculating the ACV of your car after it is stolen, your insurance company generally won’t consider expensive vehicle modifications, such as a high-end sound system or a custom paint job. As a result, you may need to purchase a car insurance add-on called custom parts and equipment coverage to ensure you will be fully reimbursed if these upgrades are ever damaged or stolen.[1]
Loan and Lease Payoffs
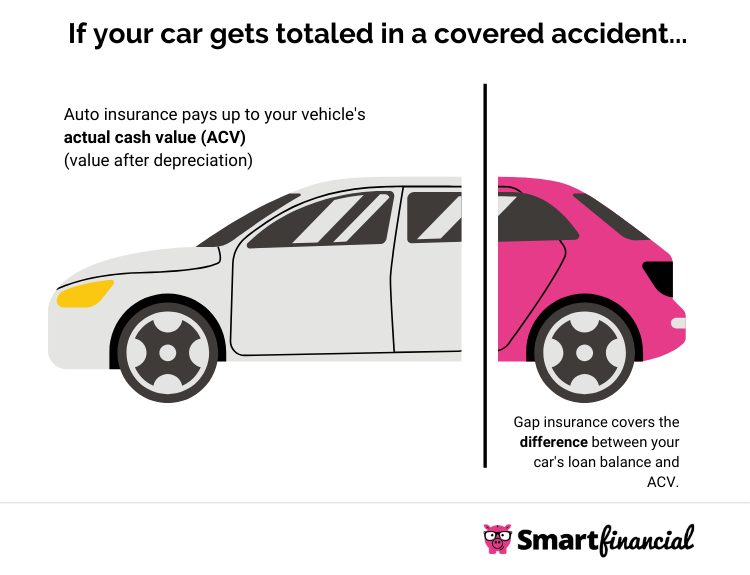
Comprehensive coverage won’t necessarily pay off your outstanding loan balance or lease payments if your car is stolen, so you may want to buy gap insurance. Since cars depreciate quickly — often losing 20% of their value within a year of purchase — it’s possible for your car’s ACV to drop below the amount you still owe your lender or lessor.[2] In this case, your comprehensive insurance payout after a total loss wouldn’t be enough to fully repay your debt.
However, gap insurance can help in this situation by covering the difference between your outstanding debt and the ACV of your stolen vehicle. For example, suppose your car is worth $10,000 when it is stolen, you have a $1,000 deductible and you still owe $12,000 on your auto loan. In this scenario, your comprehensive coverage would pay out $9,000, and your gap coverage would pay out $2,000, enabling you to finish paying off the loan.
Stolen Items
Auto insurance doesn’t cover personal belongings stolen from your car, but homeowners and renters insurance do. For example, if your car is stolen with your phone and laptop inside, you may file one claim with your car insurance company for the vehicle itself and another with your home insurance company for the lost electronics. Keep in mind that coverage for items stored outside of your home may be limited to 10% of your overall personal property coverage limit.[3]
What Types of Car Insurance Policies Cover Theft?
Car theft is covered by comprehensive insurance and other coverage types that are triggered by the same perils, such as custom parts and equipment, new car replacement and gap insurance. If you have full coverage car insurance, then your policy should already include comprehensive coverage. Full coverage isn’t required by law in any state, but you will generally need to have it to finance or lease a vehicle.
In 2022, 80% of insured drivers had a policy that included comprehensive insurance coverage, so it’s more likely than not that your car insurance covers vehicle theft.[4] Nevertheless, if you’re unsure about your policy’s coverage specifics, you can check whether you have comprehensive coverage by reviewing your auto insurance policy’s declarations page.
Another useful car insurance endorsement worth considering in case your car gets stolen is rental car reimbursement coverage. This coverage type can help you pay to temporarily rent a car while you wait for the police to find your lost vehicle. Rental car reimbursement typically comes with coverage limits ranging from $25 to $50 per day for 14 to 30 days.[5]
What Should I Do if My Car Is Stolen?
Once you have confirmed that your car has been stolen, take the following steps:
- Prepare information about your car, such as its vehicle identification number, license plate number and other identifying characteristics.
- Call 911 to report the theft so law enforcement officers can begin searching for the car.
- File a car insurance claim.
- File a homeowners insurance claim for items that were inside your car when it was stolen, if applicable.
- Contact your bank or other relevant institutions to lock your accounts, cancel your credit cards or request new documents if they were inside your car when it was stolen.
If police officers recover your vehicle before your insurance company has offered you a settlement, the insurer may still reimburse you for any damage your car incurred during the theft. Conversely, if your car is recovered after your insurance carrier has already paid you the vehicle’s ACV, then the insurer may take ownership of the vehicle.[6]
Which Car Insurance Companies Offer Anti-Theft Discounts?
Several insurance companies offer discounted premiums for cars with anti-theft devices, including Allstate, GEICO, Nationwide, State Farm, USAA and more. Usually, a car insurance company will offer you a 15% to 20% discount on your comprehensive coverage for installing a passive car alarm. Insurers may even be required to offer anti-theft device discounts in some states, such as the following:[7]
How Can I Prevent My Car From Being Stolen or Broken Into?
Taking precautions like these can lower the odds that your car will be stolen or broken into:
- Install an audible car alarm, a visible anti-theft device, an immobilizer system and a tracking system to help the police locate your stolen vehicle, if necessary.
- Be aware of your surroundings whenever you leave your car.
- Park your car in a garage or a well-lit area.
- Make sure there are no valuable items in your car that are visible from the outside.
- Lock your car doors, and ensure the windows are closed.
- Remove the keys from the ignition, and verify that there aren’t any spare keys nearby.
- Insurance quotes /
- Auto /
- Does Car Insurance Cover Theft
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Auto Insurance Quote Online Now.
More on Auto Insurance

Looking for Auto Insurance?
Compare rates from dozens of companies in less than 3 minutes.