

Do I Need Additional Coverage To Rent a Car?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Depending on your insurance company, your car insurance policy may already cover rental cars with the same coverages and limits that apply to the vehicles you own and that are listed on your policy. However, if your car insurance doesn’t cover rental cars or you want to file rental-related claims without the risk of raising your auto insurance premiums, you may want to purchase separate coverage from your rental car company or another provider.
Read on to learn more about insurance for rental cars, including the types of coverage that may be offered when you rent a car.
|
Key Takeaways
|
On This Page

Does Car Insurance Cover Rental Cars?
What Types of Insurance Policies Cover Rental Cars?
Which Car Insurance Companies Cover Rentals?
When Should I Consider Rental Car Insurance?
What Does Rental Car Insurance Cover?
Do Credit Card Companies Offer Car Rental Insurance?
How To Get Insurance With Car Rental Coverage Included
FAQs

Does Car Insurance Cover Rental Cars?
Many car insurance policies automatically extend coverage to rental cars, with your policy’s current coverage types, limits and deductibles following you whenever you drive a rental.[1] That said, rental car insurance coverage is not necessarily standardized across all insurance companies, so it’s best to contact your insurer and confirm whether you’ll be covered before renting a vehicle.
Do I Need Additional Coverage if I Rent a Car?
Usually, rental car insurance is not a separate coverage type you need to add to your auto insurance policy — rather, the various coverages in your policy should automatically apply to rental vehicles, unless your car insurance company excludes coverage for rentals. Keep in mind that rental car coverage is not the same as rental car reimbursement, which is an optional coverage you can add to your car insurance policy.
What Types of Insurance Policies Cover Rental Cars?
In general, a rental car may be eligible for coverage under all of the coverage types included in your standard auto insurance policy. Depending on your state, this could include mandatory coverages like uninsured and underinsured motorist (UM/UIM) coverage, personal injury protection (PIP) or medical payments coverage (Medpay).
However, some of the most important coverage types that are included in a typical full coverage car insurance policy — and that may apply to cars you rent — are those discussed in the following sections.
Liability
Every state except for New Hampshire requires drivers to carry liability car insurance, which takes care of another person’s expenses after an accident you are held liable for.[2] Liability insurance can be broken down into two distinct coverage types:
- Bodily injury (BI): BI liability insurance covers medical costs, lost wages and final expenses for someone you injure or kill in an accident. In addition, it can cover your legal fees if you face a liability lawsuit due to an at-fault car accident.
- Property damage (PD): PD liability insurance covers repairs if you are responsible for damaging someone else’s property. Types of covered property include individuals’ cars, homes and other belongings, along with public property.
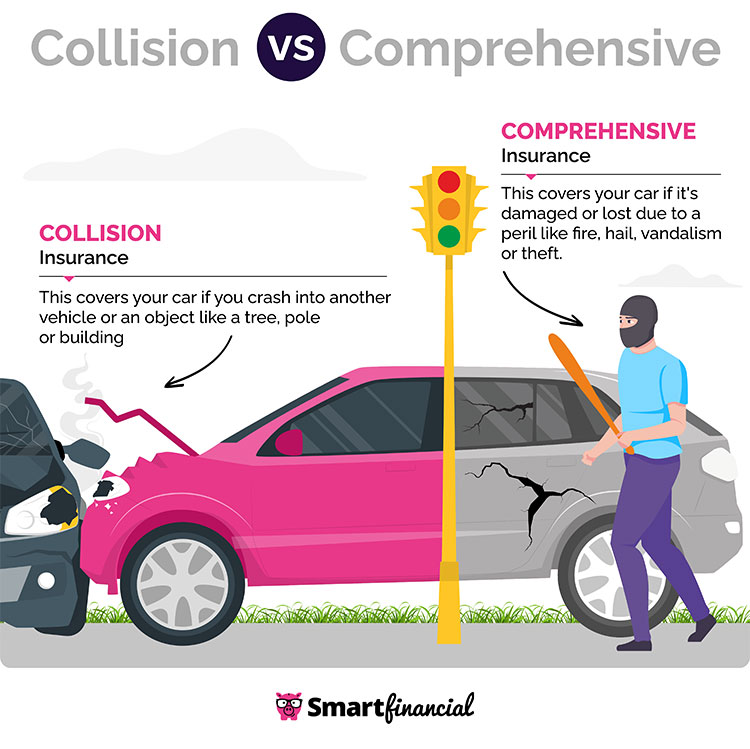
Comprehensive
Comprehensive coverage insures your vehicle against losses caused by external perils. Covered sources of loss or damage to your car may include the following:
- Fire
- Hail
- Windstorms
- Floods
- Earthquakes
- Theft
- Vandalism
- Civil disturbances
- Falling objects
- Animal collisions
Collision
Collision coverage can pay to repair or replace your car after an accident, even if you’re at fault. It also provides coverage if you crash into a stationary object or are involved in a single-car rollover. Collision and comprehensive coverage aren’t required by law in any state, but they are often required by lenders and lessors.
Which Car Insurance Companies Cover Rentals?
Examples of car insurance companies that generally cover rental cars include the following:
- Allstate
- American Family
- Farmers
- GEICO
- Nationwide
- State Farm
- Travelers
- USAA
When Should I Consider Rental Car Insurance?
Not everyone needs standalone rental car insurance, as it often overlaps with an existing car insurance policy and can be expensive — costing around $60 per day on average.[3] Nevertheless, there are some situations when you may want to consider purchasing coverage specifically for your rental from either the rental car company or a specialty insurance provider.
Naturally, you’ll need to buy rental car coverage if you don’t have an active car insurance policy or your policy doesn’t extend coverage to rentals. Additionally, there are some situations where separate rental coverage may make sense even if your auto insurance does cover rentals. For example, American car insurance policies generally won’t cover you while you’re in Mexico, so you may need a specialized rental insurance policy if you plan to travel there.[4]
You may also need separate coverage if you rent a car for business purposes because personal auto insurance policies usually don’t cover commercial use. Finally, you should consider buying insurance from the car rental service if you plan to rent a luxury car and your personal car insurance policy’s physical damage coverage limits aren’t high enough to cover the vehicle’s replacement cost.[5]
What Are the Benefits of Rental Car Insurance?
One of the biggest benefits of rental car insurance is that it may allow you to file a property damage or liability claim related to a rental without risking an increase in your personal car insurance premiums — although this may depend on whether it acts as primary coverage in the event of a collision.[6] Rental coverage may also be beneficial if your car rental agency offers more coverage types, higher coverage limits or lower deductibles than your current policy.
What Does Rental Car Insurance Cover?
When you get insurance through a rental car company, your contract will generally include the following four coverage types:[1]
- Loss/collision damage waiver (LDW/CDW): An LDW or CDW is an alternative to physical damage coverage; when you buy it, your rental company agrees to waive your financial responsibility in the event that the car is stolen or totaled in an accident. It can also cover towing and loss of use fees that the rental car company would otherwise charge you after an accident.
- Liability coverage: This supplemental liability insurance functions the same as the liability coverage portion of a standard car insurance policy. Your rental car company is required to offer you at least enough coverage to meet your state’s minimum coverage standards.
- Personal accident coverage: Personal accident insurance can pay for ambulance rides and medical treatments for you and your passengers if you are injured in a rental car accident.
- Personal effects coverage: Rental car policies include personal effects insurance to cover personal belongings that are stolen from your rental car. This distinguishes rental car coverage from standard car insurance, which does not cover items in your car since they are typically covered by homeowners insurance or renters insurance instead.
What Isn't Covered?
Your rental car insurance policy may exclude coverage for the following:[8]
- Drunk driving
- Offroading
- Reckless driving (e.g., speeding)
- Damage to tires and windshields
- Accidents involving unapproved drivers
- Illegal activities
- Driving in restricted areas
- Treatments for preexisting conditions after an accident
- Loss of valuables or other unattended items
Do Credit Card Companies Offer Car Rental Insurance?
If you use your credit card to pay for a rental, you may receive rental car insurance benefits from your credit card company. However, this coverage is often more limited than coverage from rental car companies or traditional insurance carriers. For example, your credit card company may only pay out enough to reimburse your deductible when you file an auto insurance claim.[1]
In addition, your credit card company may exclude coverage for liability claims altogether, instead providing coverage exclusively for physical damage claims. Lastly, your credit card rental insurance may act as secondary coverage, meaning you may only qualify for a payout if you first exhaust the coverage limit of another insurance policy, like your car insurance.[5]
Credit Card Companies That Offer Insurance for Rental Cars
Some of the companies that offer credit cards with rental car insurance benefits include the following:
- American Express
- Bank of America
- Capital One
- Chase Bank
- Navy Federal Credit Union
- Wells Fargo
How To Get Insurance With Car Rental Coverage Included
If your current car insurance doesn’t cover rental cars, you should shop around by comparing quotes from around three to five different insurers. Make sure to confirm up front whether each insurance carrier provides rental car coverage. Of course, it can be burdensome to individually reach out to each insurance company to give them your information and ask for quotes.
But with SmartFinancial, insurance shopping is much easier. We can connect you with insurance agents who are equipped to help you find a policy that’s the best possible fit for your coverage needs and budget. Fill out our online questionnaire and start comparing car insurance quotes for free today!
- Insurance quotes /
- Auto /
- Does Car Insurance Cover Rental Cars
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Auto Insurance Quote Online Now.
More on Auto Insurance

Looking for Auto Insurance?
Compare rates from dozens of companies in less than 3 minutes.