

Do I Need Comprehensive Car Insurance?
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Comprehensive car insurance is a type of car insurance that covers damage from unexpected perils, like fire, hail, theft and vandalism. While it is not required by law, you will likely need comprehensive coverage if you lease or finance your vehicle.
Keep reading to learn what comprehensive auto insurance covers and whether it should be added to your car insurance policy.
|
Key Takeaways
|
On This Page

What Is Comprehensive Car Insurance?
How Does Comprehensive Car Insurance Work?
What Does Comprehensive Car Insurance Cover?
How Much Does Comprehensive Car Insurance Cost?
Is a Comprehensive Car Insurance Policy Required?
Who Is Comprehensive Car Insurance Best For?
Can I Add Comprehensive Coverage to My Policy at Any Time?
How To Get Comprehensive Car Insurance
FAQs

What Is Comprehensive Car Insurance?
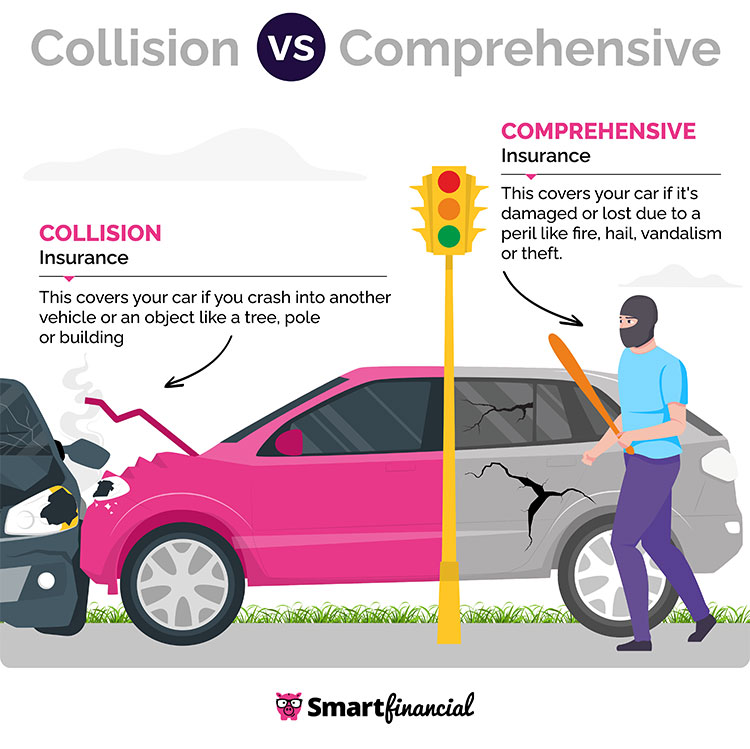
Comprehensive car insurance is one of the two types of physical damage coverage, along with collision coverage. In general, comprehensive coverage accounts for most noncollision incidents that could damage your car. Covered events could range from natural disasters to damage intentionally done to your car by an unknown person.
Comprehensive coverage is often sold alongside collision insurance, which provides coverage in case you crash into another car or a stationary object, like a tree, fence or guardrail. You can typically purchase a full coverage policy that includes both physical damage coverage types plus liability insurance and any other coverage types required in your state.
What’s the Difference Between Comprehensive and Full Coverage?
Comprehensive coverage is only one part of full coverage, which typically combines comprehensive and collision coverage with any other insurance types required in your state. For example, in California, full coverage would include liability, collision and comprehensive coverage, while in Connecticut, it would also include the legally required uninsured and underinsured motorist (UM/UIM) insurance coverages.[1][2]
How Does Comprehensive Car Insurance Work?
Suppose your car is stolen or totaled due to a peril covered by your comprehensive coverage. In that case, your insurance company will typically pay you your car’s actual cash value (ACV) minus your deductible. Your deductible is the minimum amount of money you agree to contribute toward covered losses before your insurance company will chip in.
For example, if you have a $500 deductible on your comprehensive coverage and a tree causes $10,000 worth of damage by falling onto your car, your insurance company would provide $9,500 for repairs.

What Does Comprehensive Car Insurance Cover?
Comprehensive insurance generally covers damage from forces outside of your control. This sets it apart from collision insurance, which usually kicks in after an accident you are responsible for. Examples of situations where your comprehensive coverage would provide financial support include:
- Fire: A propane grill under your carport explodes and sets fire to your car.
- Hail: You need a windshield replacement after a chunk of hail cracks your windshield.
- Windstorms: High winds from a tornado or hurricane flip your car over.
- Floods: Floodwaters ruin your car’s electrical system.
- Earthquakes: Your car is crushed after a parking garage collapses during an earthquake.
- Theft: An intruder damages your vehicle while attempting to steal gasoline or its battery.
- Vandalism: A disgruntled acquaintance keys the side of your car and slashes all of your tires.
- Civil disturbance: A riot breaks out in your neighborhood, and rioters throw rocks through your windows.
- Falling objects: The roof of your car caves in after a heavy tree branch falls on top of it.
- Collision with an animal: A deer runs into your car, shattering your headlights and tearing off your front bumper.
What Isn’t Covered?
Comprehensive insurance typically doesn’t cover medical bills or any damage you inflict on another person’s vehicle. However, you can usually make up for the blind spots of comprehensive coverage by purchasing other types of car insurance.
How Much Does Comprehensive Car Insurance Cost?
The average cost to add collision coverage to your auto insurance policy is $196.22 per year as of 2022, but actual costs can vary depending on factors like your insurer, region and more. For example, the state with the lowest average premium for collision coverage is California ($104.29), while South Dakota ($406.45) has the highest average premium.[3]
Below, we’ll cover the average cost of collision insurance for each state and the District of Columbia.[3]
|
State/District |
Average Annual Premium |
|---|---|
|
$201.70 |
|
|
$161.18 |
|
|
$239.54 |
|
|
$259.16 |
|
|
$104.29 |
|
|
$371.73 |
|
|
$153.34 |
|
|
$155.69 |
|
|
$236.87 |
|
|
$179.92 |
|
|
$198.69 |
|
|
$109.69 |
|
|
$157.34 |
|
|
$171.52 |
|
|
$155.35 |
|
|
$264.11 |
|
|
$312.69 |
|
|
$182.71 |
|
|
$281.08 |
|
|
$138.94 |
|
|
$184.26 |
|
|
$158.34 |
|
|
$190.59 |
|
|
$255.27 |
|
|
$273.81 |
|
|
$253.24 |
|
|
$333.70 |
|
|
$306.93 |
|
|
$121.70 |
|
|
$134.48 |
|
|
$148.46 |
|
|
$226.57 |
|
|
$200.95 |
|
|
$186.15 |
|
|
$279.38 |
|
|
$150.57 |
|
|
$297.84 |
|
|
$125.63 |
|
|
$198.74 |
|
|
$167.33 |
|
|
$225.47 |
|
|
$406.45 |
|
|
$193.01 |
|
|
$323.14 |
|
|
$138.96 |
|
|
$160.52 |
|
|
$172.16 |
|
|
$129.85 |
|
|
$251.77 |
|
|
$192.72 |
|
|
$395.54 |
Most insurers factor the risk of making a claim into your rates. For example, living in a city with a high vehicle theft rate may result in increased premiums to offset that risk. Similarly, if you live in an area with high rates of deer collisions, that may also increase your rates due to the higher risk of making a claim.
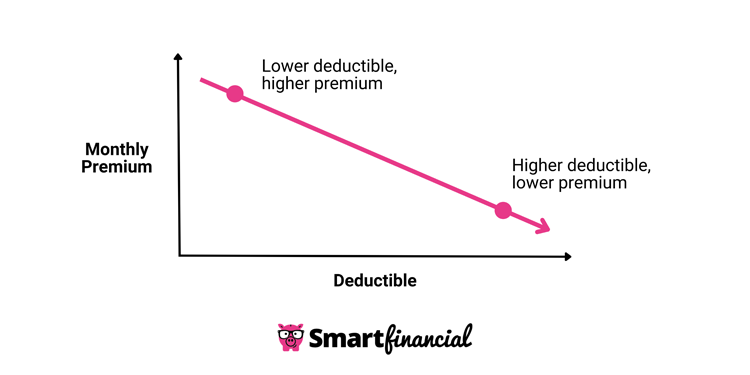
Your deductible choice can also affect your rates. Typically, lower deductibles lead to higher premiums, as you’re offloading most of the cost risk to the insurer if you make a claim. However, be wary of increasing your deductible above what you can afford; otherwise, you may face financially burdensome out-of-pocket expenses if you make a comprehensive coverage claim.
Is a Comprehensive Car Insurance Policy Required?
Comprehensive coverage is not required by law in any state. However, if you are financing or leasing your car, your lender or lessor will likely require you to have comprehensive coverage to better protect their financial interest in your car.[4]
Once you have finished paying off your car or ended your lease, you are not required to have comprehensive insurance. However, it may be worth keeping if you live in an area susceptible to crime, extreme weather or other perils covered by comprehensive insurance.
Who Is Comprehensive Car Insurance Best For?
Below, we’ll cover a few examples of situations where you may want to consider purchasing a comprehensive insurance policy:
- You have an outstanding car loan or active lease: If you’re financing or leasing your car, your lender or lessor will likely require you to maintain comprehensive coverage until you fully repay the loan or terminate your lease. However, comprehensive coverage is optional if you don’t have an outstanding loan and are not under a lease.
- Your car has a high fair market value: If your car is brand new or still worth a lot after several years, maintaining comprehensive coverage may be worth the cost. Damage from a falling tree may not make a significant difference if your car is older and already worn down, but it may lead to substantial replacement costs if you have a more valuable car.
- You’re unable to pay repair or replacement costs out of pocket: Comprehensive car insurance can offer some financial relief if you don’t have an adequate amount of money in your savings account to cover emergencies, such as car repairs after you hit a deer or a replacement after your car is stolen.
Can I Add Comprehensive Coverage to My Policy at Any Time?
You should be able to add comprehensive coverage to an existing car insurance policy anytime. Additionally, new customers to an insurer will be able to add comprehensive coverage when they first enroll.[4] Generally, you don’t have to wait until it’s time to renew your policy if you want to update your coverage.
How To Get Comprehensive Car Insurance
To understand your options for comprehensive coverage, you’ll want to get a range of quotes, typically three to five, from differing insurers. You’ll typically need to inform each insurer about your car’s value, your location, and other details so they can provide an estimated rate. Keep in mind that this process may become time consuming and tedious, as you’ll typically need to gather quotes from each insurer one by one.
Speed up this process by using an insurance marketplace like SmartFinancial. After answering a brief questionnaire, we can connect you with a licensed insurance agent to help you find the coverage you need. Click here for a free auto insurance quote today!
- Insurance quotes /
- Auto /
- Comprehensive Car Insurance
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Auto Insurance Quote Online Now.
More on Auto Insurance

Looking for Auto Insurance?
Compare rates from dozens of companies in less than 3 minutes.