
What Should I Do if My Home Has Roof Damage?
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
If you notice roof damage, consider making a homeowners insurance claim. Look for damaged or missing shingles, especially after a big storm, as these can be signs that your roof needs repair or replacement.
Keep reading to learn when your homeowners insurance may cover roof damage, what signs of damage to look for and how to make an effective claim.
|
Key Takeaways
|
On This Page

Does Home Insurance Cover Roof Damage?
Does Home Insurance Always Cover Roof Damage?
How Is Roof Damage Determined?
What Are the Most Common Types of Roof Damage?
How Do I Know if I Have a Damaged Roof?
What Should I Do if I Have a Damaged Roof?
How To File a Home Insurance Claim for Roof Damage
FAQs

Does Home Insurance Cover Roof Damage?
Your homeowners insurance may cover roof damage, although it depends on the cause of the damage. Standard homeowners policies are open peril policies, which means your roof damage will be covered so long as it was not caused by an excluded peril.[1] Commonly covered perils are typically ones that are sudden and unexpected and often include:
|
|
Will My Home Insurance Pay for a New Roof?
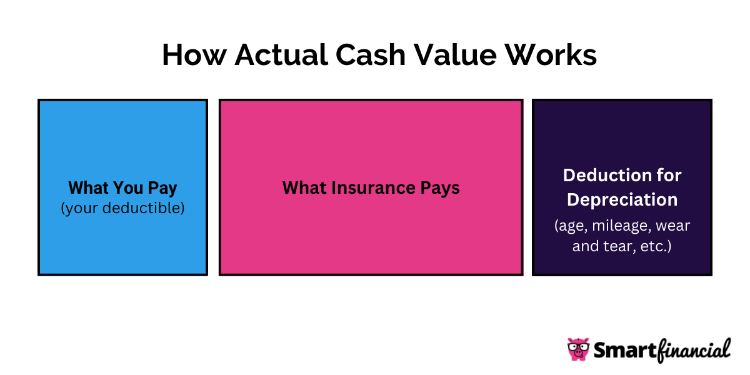
If your claim is approved, your homeowners insurance may cover some or all of the cost to replace your roof, depending on the type of policy you have. If you have an actual cash value (ACV) policy, you may only receive the depreciated value of your roof based on its current worth. This could mean opting for less expensive materials or paying the difference for a higher-quality roof out of pocket.
Alternatively, a replacement cost value (RCV) policy would cover the cost to replace your roof with a comparable modern equivalent. While this type of policy typically covers the full replacement cost, you may need to pay out of pocket if you choose to upgrade to higher-quality materials than what was originally used.
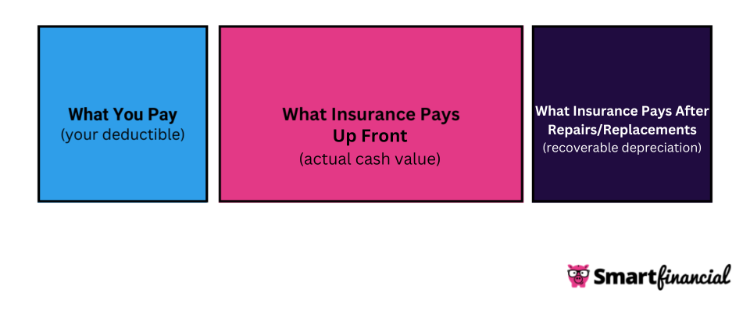
You’ll also need to cover your deductible, which typically ranges from $100 to $5,000 for most homeowners insurance policies.[2] Your insurer will only provide coverage up to your policy’s limit, and any additional expenses must be paid out of pocket.
Does Home Insurance Always Cover Roof Damage?
Even in an open peril policy, there are often exceptions to some causes of roof damage that homeowners insurance will cover. For example, your homeowners insurance dwelling coverage will often exclude damage caused by lack of maintenance, negligence, rot or mold, as these are considered avoidable and are the homeowner’s responsibility.[1]
Damage to your roof as a result of a flood or earthquake is typically also excluded, as these perils usually require a separate insurance endorsement for coverage. While typically covered, windstorms and hailstorms may also be excluded in your policy if you live near high-risk areas, like coastlines.[1] Wind and hail are common causes of home damage, and they may require you to get an endorsement or separate windstorm insurance for coverage.[4][5]
Cosmetic damage — such as minor warping, rust or discoloration — is also typically excluded, as long as it’s determined not to affect the roof’s ability to protect your dwelling from the elements.[6]
How Is Roof Damage Determined?
Roof damage is determined through physical inspection from the ground and on the roof itself. Inspectors may also check inside the home to see if water has leaked through the roof’s protective barrier. When filing an insurance claim, you’ll often need assessments from both a roofing professional and a claims adjuster to confirm the damage and its extent. We’ll discuss more about what types of roof damage signs to look for later on.
What Are the Most Common Types of Roof Damage?
Below, we’ll cover common types of roof damage:[7]
- Wind damage: Typically caused by strong storms and hurricanes, this commonly tears away and damages shingles.
- Hail damage: Heavy hail can cause cracks or holes in your roof, exposing the interior of your home to the elements.
- Ultraviolet (UV) radiation and heat damage: The natural heat and radiation from the sun can cause your roof to deteriorate over time, leading to warped and cracked shingles. Areas that get regular high temperatures or long exposure to sunlight may experience this type of damage more frequently.
- Leaks and water damage: Clogged gutters or missing shingles can often lead to water infiltrating the protective layer of your roof, which can cause further damage to the roof itself and to your home’s interior.
- Damaged flashing: The flashing is the seal used around the seams of your roof, such as around chimneys, vents or skylights. Damaged flashing, caused by regular wear and tear or improper installation, lessens your roof’s protective quality and can leave it exposed to water leaks.
How Do I Know if I Have a Damaged Roof?
Below are common signs that indicate roof damage:[7][8]
- Leaks inside the attic
- Blistering or peeling paint
- Interior ceiling and wall stains
- Sheathing decay
- Damaged or missing shingles
- Damaged vents
- Sagging sections of the roof or standing water
- Deteriorating chimney
- Dark streaks from moss or lichen
What Should I Do if I Have a Damaged Roof?
If you’ve discovered roof damage, you’ll likely want to get a confirmation from a roofing professional. Consider filing a homeowners insurance claim to help cover the cost of repairs, depending on the extent of the damage.
You’ll want to make a claim sooner rather than later, as insurance companies may only give you between 30 days and a year to file the claim after the date of the incident that caused damage.[9] This is why it’s critical to check your roof for damage after a storm or another potential damaging event as soon as it’s safe to do so.
How To File a Home Insurance Claim for Roof Damage
Below, we’ve outlined the steps you’ll typically follow when filing a roof insurance claim:
- Determine the extent of the damage: You’ll need to inspect the roof for any signs of visual damage. If you aren’t experienced in roof repair and can’t confirm any potential damage from the ground, strongly consider contacting a professional who can check your roof on your behalf to avoid a potential falling accident or causing additional damage to your roof by mistake.
- Take pictures: Take pictures of the roof’s condition and any interior damage, such as water spots in the ceiling or upper walls. You’ll likely need to submit pictures as evidence when making the claim.
- Get an estimate for repairs: Contact multiple contractors to get repair estimates. Insurers will not pay if the cost of damage does not exceed your deductible, such as if you only need to replace a few shingles.
- Determine what your policy will cover: Before filing an insurance claim, confirm if an excluded peril caused the damages. For example, your homeowners insurance will not replace an old and decaying roof, as policies typically exclude natural wear and tear from coverage.
- Call your insurer: Contact your insurance company as soon as possible, as there may be a limited timeframe for filing a claim. Your insurance company may send an adjuster to assess the damage in person before offering a settlement.
- Replace your roof: After agreeing to a settlement with your insurance company, it’s time to schedule a reputable roofing contractor to complete the repairs. A standard home insurance policy typically covers temporary housing if your home is unusable while it is being repaired, so you may be able to receive reimbursement for expenses like meals, laundry services and even pet boarding.
- Insurance quotes /
- Home /
- Roof Damage
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Home Insurance Quote Online Now.
More on Home Insurance
Looking for Home Insurance?
Compare rates from dozens of companies in less than 3 minutes.