
The State of Homeowners Insurance 2026: Are Rates Expected To Go Down?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
After seeing considerable increases in 2024, average homeowners insurance rates rose modestly over the course of 2025, suggesting the market has stabilized somewhat. Still, home insurance premiums are unlikely to go down significantly in 2026 due to factors like the increased prevalence of natural disasters, new tariffs on imported materials and rising home rebuilding costs.
Keep reading for more information about the state of homeowners insurance in 2026, including average rates by state and tips for lowering your insurance premiums.
|
Key Takeaways
|


2026 Homeowners Insurance Rates by State
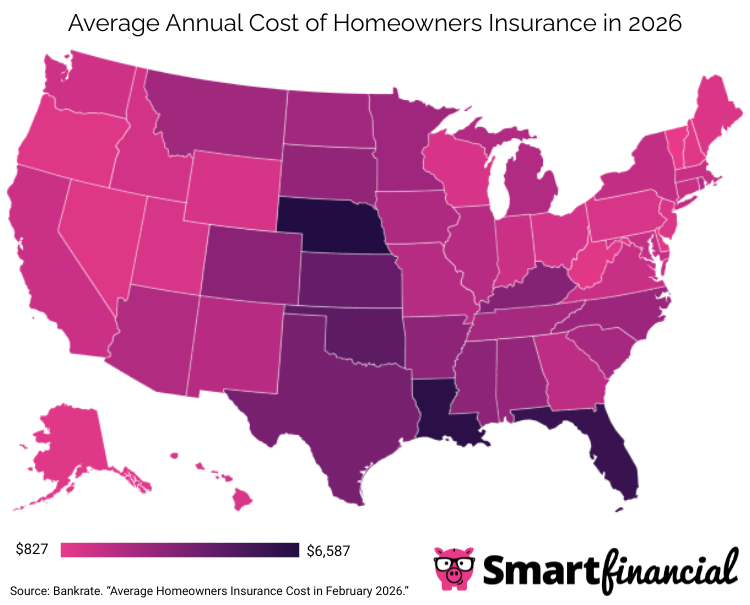
The average cost of a home insurance policy with $300,000 worth of dwelling coverage is $2,424 per year in the United States as of February 2026 — a year-over-year increase of about 7%. View the next table for an overview of how much homeowners insurance costs on average in each state and how much the average rate changed in each state from February 2025 to February 2026.[1][2]
|
State/District |
Average Annual Premium |
Percentage Change |
|---|---|---|
| Alabama | $3,114 | +4.2% |
| Alaska | $1,035 | +10.9% |
| Arizona | $2,331 | +3.8% |
| Arkansas | $3,287 | +4.3% |
| California | $1,641 | +14.8% |
| Colorado | $3,412 | +7.7% |
| Connecticut | $1,700 | +2.4% |
| Delaware | $966 | +0.2% |
| Florida | $5,838 | +6.4% |
| Georgia | $2,041 | +2.4% |
| Hawaii | $1,296 | +5.9% |
| Idaho | $1,409 | +9% |
| Illinois | $2,225 | -1.8% |
| Indiana | $1,666 | -2.7% |
| Iowa | $2,446 | +11.3% |
| Kansas | $4,444 | +3.7% |
| Kentucky | $3,540 | +5.5% |
| Louisiana | $6,274 | +51.7% |
| Maine | $1,219 | -1.9% |
| Maryland | $1,751 | +4.8% |
| Massachusetts | $1,733 | +1.8% |
| Michigan | $2,368 | +11.9% |
| Minnesota | $2,852 | +8.5% |
| Mississippi | $3,353 | +0.4% |
| Missouri | $2,191 | -4.8% |
| Montana | $2,801 | +11.5% |
| Nebraska | $6,587 | +16.8% |
| Nevada | $1,074 | +4.2% |
| New Hampshire | $1,039 | +1.3% |
| New Jersey | $1,214 | +1.7% |
| New Mexico | $2,179 | -1.2% |
| New York | $1,860 | +6.2% |
| North Carolina | $2,951 | +43.6% |
| Ohio | $1,364 | +4.7% |
| Oklahoma | $4,695 | +1.1% |
| Oregon | $1,091 | +7.9% |
| Pennsylvania | $1,278 | +2.7% |
| Rhode Island | $2,347 | +1% |
| South Carolina | $2,611 | +10% |
| South Dakota | $3,152 | +3.4% |
| Tennessee | $2,672 | +6.9% |
| Texas | $3,899 | -1.9% |
| Utah | $1,283 | +1.7% |
| Vermont | $827 | -0.4% |
| Virginia | $1,706 | +2.5% |
| Washington | $1,539 | +1.7% |
| Washington, D.C. | $1,525 | +2.9% |
| West Virginia | $1,047 | +3.8% |
| Wisconsin | $1,303 | +6.9% |
| Wyoming | $1,306 | +0% |
Will Home Insurance Rates Go Down in 2026?
Following a nearly 30% increase in average premiums from 2024 to 2025, the home insurance market experienced some stabilization last year, resulting in only a single-digit percentage increase in average costs from 2025 to 2026.[1][2][3] Nevertheless, premiums are unlikely to drop substantially in 2026, as factors like climate change and inflation continue to drive up the prevalence and cost of homeowners insurance claims.
Why Have Some Insurers Left California, Florida and Other States?
In recent years, several insurance companies have limited the number of policies they offer, stopped doing business altogether or become insolvent in certain high-risk states, such as Colorado, Louisiana, California and Florida. These states often have a high exposure to natural disasters — like wildfires and hurricanes — raising the level of risk associated with covering the properties in these states and making it harder for insurers to operate at a profit.
Other state-specific factors may also prompt a large number of carriers to leave certain states. For example, Florida’s insurance crisis has historically been driven by the state’s high rate of fraudulent lawsuits and overreliance on reinsurance.[4] Additionally, California’s efficient proximate clause rule may raise costs for insurance companies, since it requires insurers to cover otherwise excluded mudflows if they are triggered by covered wildfires.[5]
Factors That May Lead to Higher Homeowners Insurance Rates
Several different factors could result in higher home insurance prices over the course of 2026, as discussed in the sections below.
High Property Values
The high cost of houses can contribute to higher homeowners insurance premiums. Over the past decade, housing prices have nearly doubled in the United States, and the average ratio of housing prices to annual incomes has been near a record high for the past three years. President Donald Trump recently stated that his goal is to drive housing prices even higher, although some experts expect prices to remain stable throughout 2026.[6][7]
Home insurance is not directly related to property value, since your insurer will not take factors like the value of your land or your home’s proximity to various amenities into account when setting your rates. Even so, your insurance company will consider the cost to rebuild your home, and more expensive properties generally come with higher replacement costs, necessitating higher insurance premiums.[8]
Rising Material and Labor Costs
Your home insurance company must cover the cost of construction materials and labor if your house is damaged or destroyed by a covered peril and needs to be repaired or rebuilt, so premiums generally rise as these become more expensive. It’s estimated that the construction industry needs nearly 350,000 new employees to meet the demand for construction services in 2026 — otherwise, the ensuing worker shortage could lead to higher labor costs.[9]
Meanwhile, tariffs could lead to significant price hikes for certain imported building materials, such as lumber, steel and aluminum.[10] Though material prices stayed fairly stable despite the implementation of higher tariffs in 2025, these prices could increase as existing inventories are depleted and suppliers need to import new materials in 2026.[11]
Natural Disasters
If you live in a state with a high rate of natural disasters covered by homeowners insurance, you can generally expect to pay more for home insurance coverage. For example, the five states with the highest average premiums — Nebraska, Louisiana, Florida, Oklahoma and Kansas — all have a high exposure to windstorms, such as hurricanes or tornadoes.[1]
In addition, California wildfires caused $40 billion worth of covered property damage during the first half of 2025 — accounting for 50% of the world’s total insured natural catastrophe losses during that time frame.[12] In general, hurricanes and wildfires have a pronounced impact on homeowners insurance costs because of their capacity to destroy homes, which means insurers can expect to have to pay out particularly expensive claims in disaster-prone areas.
Reinsurance Prices
When prices rise for reinsurance — the policies insurance companies buy to protect themselves against a large amount of costly claims — carriers naturally pass on some of those costs to their policyholders, resulting in higher premiums. Fortunately, global reinsurance rates dropped significantly at the beginning of 2026 and are expected to continue trending downward, which may partially offset some of the other factors leading to higher home insurance rates.[13]
Insurance Fraud
Home insurance fraud drives up expenses for insurers and premiums for policyholders, all while benefiting bad actors rather than people who actually need financial relief due to sudden and unexpected losses. Across all types of insurance, fraudulent claims cost American consumers an estimated $308.6 billion or more each year. For property and casualty insurance — a category that includes homeowners insurance — about 10% of claims involve fraud.[14]
High Medical Costs
Since the personal liability or medical payments coverage portion of your homeowners policy may have to cover medical treatments for someone injured on your property, your home insurance rates may go up as health care services become more expensive. On the whole, the cost of medical services went up by 3.9% from January 2025 to January 2026 — including a 6.6% increase in the cost of hospital services.[15]
Inflation
In general, inflation has a pervasive impact on insurance prices — if the cost of anything your insurance company may have to pay for goes up, your premiums may go up accordingly. See the following table for examples of year-over-year inflation rates for various services that may be covered by your home insurance policy.[15][16]
|
Service |
Inflation Rate |
Example of When Home Insurance May Cover It |
|---|---|---|
|
Food away from home |
4% |
Your loss of use coverage pays for restaurant meals because your home is uninhabitable due to a covered peril and the hotel where you are temporarily staying doesn’t have a kitchen |
|
Major appliances |
2% |
Your dwelling coverage pays to replace your built-in water heater after it explodes due to a sudden buildup of pressure |
|
Musical instruments and accessories |
5.5% |
Your personal property coverage reimburses you after your collection of guitars is stolen |
|
Funeral expenses |
5.6% |
Your medical payments coverage pays out a death benefit after a guest drowns in your swimming pool |
|
Legal services |
8.3% |
Your personal liability insurance covers your legal defense after a neighbor claims that your negligence led to a tree falling on their home and sues you |
Flood, Earthquake and DIC Insurance
Standard homeowners insurance policies usually exclude coverage for certain natural disasters, such as floods, earthquakes and mudslides, so you may need to purchase extra coverage for these perils. Standalone earthquake and flood insurance policies may be available through private insurance companies or government-operated programs, like the California Earthquake Authority and the National Flood Insurance Program.
Meanwhile, difference in conditions insurance is a bespoke policy offered by surplus lines insurers that can be customized to provide coverage for various perils that are excluded from standard home insurance coverage. DIC insurance is the only product that broadly covers landslides, and it may also cover perils like mudflows, floods, earthquakes, service line damage from tree roots or sudden collapses, damage from water leaks and more.[17][18]
Tips on How To Lower Homeowners Insurance Costs
Some steps you may be able to take to save money on homeowners insurance include the following:
- Bundle policies: Most insurance companies offer a discount when you bundle — or purchase multiple policies, such as both home and auto insurance, from the same carrier.
- Install a home security system: Security cameras, smoke detectors, smart home devices and other alarms can protect your home, lowering the odds that you will need to file a claim. As a result, your insurer may reward you with discounts if you choose to install them.
- Ask about other discounts: Several other actions may also lead to home insurance discounts, including paying off your mortgage, going several years without filing any claims, paying your premium in full at the beginning of the coverage period and joining an approved organization, among others. Be sure to ask your insurer whether you are eligible for any discounts that haven’t yet been applied to your policy.
- Schedule an insurance review: By reviewing your current insurance policies and coverage needs, you may be able to find areas where you can cut back on coverage in order to save money. In general, it’s recommended that you review your policies at least once per year and anytime you experience a major life event.[19]
- Improve your credit: In some states, making wiser financial decisions and improving your credit score may translate into insurance savings. That said, the use of credit-based insurance scores to calculate premiums is limited or outright banned in California, Hawaii, Maryland, Massachusetts, Michigan, Oregon and Utah.[20]
- Shop around: Each insurance company has its own formula for calculating rates, so you need to collect quotes from at least three to five insurers to determine which can offer you the best deal. Click here to start comparing home insurance quotes for free through SmartFinancial!
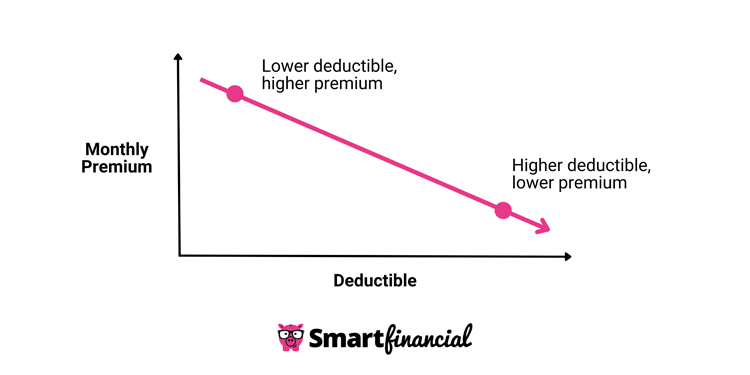
- Increase your deductible: It may be worth raising the deductible that you agree to pay out of pocket each time you file a claim in order to secure lower premiums — as long as you have enough money saved up to cover that deductible in case you need to file a claim.
- Insurance quotes /
- Home /
- Will Homeowners Insurance Go Down
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Home Insurance Quote Online Now.
More on Home Insurance
Looking for Home Insurance?
Compare rates from dozens of companies in less than 3 minutes.