

How To Get Home Insurance as a First-Time Buyer
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
As a first-time home buyer, insurance may not be at the front of your mind, but it’s a critical aspect of safeguarding your home. In addition to protecting you from the financial burden of repairing or rebuilding your home after a catastrophe, homeowners coverage is often required to secure a crucial mortgage loan to help purchase the house in the first place.
Keep reading to learn more about home insurance costs and requirements, when to purchase it, what to consider for limits and how to save on your homeowners premium.
|
Key Takeaways
|
On This Page

Is Home Insurance Required for First-Time Buyers?
What Is the Average Cost of First-Time Home Buyer Insurance?
What Types of Insurance Policies Should First-Time Home Buyers Consider?
How Much Home Insurance Do First-Time Buyers Need?
When Should I Buy Homeowners Insurance For My First Home?
How To Save Money On Insurance as a First-Time Home Buyer
Are There Programs Available To Assist First-Time Home Buyers?
FAQs

Is Home Insurance Required for First-Time Buyers?
Homeowners insurance isn’t required by law, but it may be necessary if you take out a mortgage on your home.[1] Lenders will want to protect their investment by ensuring you have the necessary coverage to rebuild or repair your home after it’s destroyed in a fire or by a potential natural disaster.
What Is the Average Cost of First-Time Home Buyer Insurance?
On average, homeowners can expect to spend $2,258 per year on homeowners insurance with $300,000 worth of dwelling coverage. Actual costs can vary significantly by state due to differences in housing prices, cost of living, construction and labor expenses and more. Below, we’ll cover the average annual cost of homeowners insurance for each state and Washington, D.C., ordered from most to least expensive:[2]
| State | Average Annual Cost |
|---|---|
| Nebraska | $5,640 |
| Florida | $5,488 |
| Oklahoma | $4,643 |
| Kansas | $4,287 |
| Louisiana | $4,135 |
| Texas | $3,973 |
| Kentucky | $3,354 |
| Mississippi | $3,339 |
| Colorado | $3,167 |
| Arkansas | $3,151 |
| South Dakota | $3,049 |
| Alabama | $2,989 |
| North Dakota | $2,709 |
| Minnesota | $2,628 |
| Montana | $2,511 |
| Tennessee | $2,499 |
| South Carolina | $2,374 |
| Rhode Island | $2,324 |
| Missouri | $2,302 |
| Illinois | $2,265 |
| Arizona | $2,245 |
| New Mexico | $2,205 |
| Iowa | $2,197 |
| Michigan | $2,117 |
| North Carolina | $2,055 |
| Georgia | $1,994 |
| New York | $1,752 |
| Indiana | $1,712 |
| Massachusetts | $1,703 |
| Maryland | $1,671 |
| Virginia | $1,664 |
| Connecticut | $1,660 |
| Washington | $1,513 |
| District of Columbia | $1,482 |
| California | $1,429 |
| Wyoming | $1,306 |
| Ohio | $1,303 |
| Idaho | $1,293 |
| Utah | $1,262 |
| Pennsylvania | $1,245 |
| Maine | $1,243 |
| Hawaii | $1,224 |
| Wisconsin | $1,219 |
| New Jersey | $1,194 |
| Nevada | $1,031 |
| New Hampshire | $1,026 |
| Oregon | $1,011 |
| West Virginia | $1,009 |
| Delaware | $964 |
| Alaska | $933 |
| Vermont | $830 |
Besides your location, other factors that can affect your rate include the following:
- Rebuilding cost: It costs less to insure a home that costs $300,000 to rebuild than one that costs $900,000.
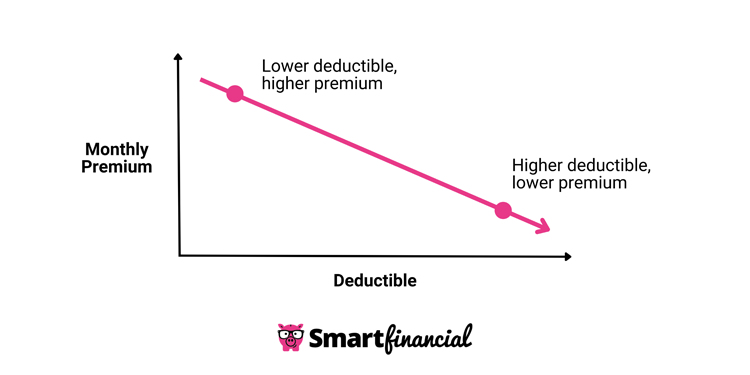
- Deductible: If you raise your deductible — the amount you pay out of pocket on approved claims — you will typically see a lower monthly premium. Conversely, a lower deductible typically pairs with a higher premium.
- Claims history: A history of multiple claims can raise your monthly premium.
- Coverages: More coverage options result in higher premiums, though you may find the extra cost is worth it to secure more thorough protection, depending on your circumstances.
- Personal information: Your credit score, age, marital status and more can affect your monthly premium.
Is Home Insurance More Expensive for First-Time Buyers?
When calculating your premium, insurers will likely weigh other rating factors, such as your property’s replacement cost, age, roof condition and location, more heavily than your status as a first-time homeowner.
Still, first-time home buyers may have some characteristics that can help keep their rates lower than the rates of established homeowners. First, you may not have a claims history, which could otherwise contribute to higher rates. Also, you may not need to buy higher personal property coverage limits, especially if you don’t have the funds to invest in high-quality, expensive furniture.
What Types of Insurance Policies Should First-Time Home Buyers Consider?
Below, we’ll cover a few insurance options for first-time home buyers to consider, including homeowners insurance endorsements:
- Scheduled property coverage: Scheduled personal property coverage may be necessary if you own expensive items and want higher coverage limits than your basic home insurance policy provides.
- Auto insurance: Your car insurance rates may change when you move into a new home, so it may be worth shopping for a new policy. Bundling home and auto insurance may offer a discount.
- Home-based business insurance: If you work from home, this can help cover your business-related personal property.
- Identity fraud coverage: This can help reimburse you for costs that come up when your identity is stolen, including legal fees and lost wages.
- Specific natural disaster insurance: Some natural disasters, like floods and earthquakes, aren’t covered by standard homeowners insurance policies, so it may benefit you to obtain separate coverage for these disasters if they are remotely common in your area.
How Much Home Insurance Do First-Time Buyers Need?
Generally, homeowners insurance should include enough dwelling coverage to cover the full cost of rebuilding your home. Size is a prominent factor, as the average construction cost of a single-family home is $162 per square foot.[3] Keep in mind that your home’s rebuild cost may differ from its purchase price or current market value.
Your insurance company will determine the minimum coverage required based on the factors mentioned earlier. Your mortgage lender may require you to add coverage for specific perils depending on your exposure to those perils, such as flood insurance for shoreline properties or earthquake insurance for properties along fault lines. Below, we explain how homeowners insurance works and the different ways a homeowner is protected by a standard policy.
|
Coverage |
Details |
|---|---|
|
Dwelling |
Covers damages to the structure you live in |
|
Other Structures |
Covers damages to structures that are not your dwelling, such as fences, driveways and tool sheds |
|
Personal Property |
Covers damages to and theft of your belongings |
|
Loss of Use |
Pays for living expenses, including hotel bills, if you are displaced from your home due to a covered peril, such as a house fire |
|
Personal Liability |
Covers claims involving bodily injury or property damage to other people (usually guests) inside your home or on your property |
|
Medical Payments |
Pays for medical bills if a guest is injured while on your property, regardless of fault |
When Should I Buy Homeowners Insurance For My First Home?
You’ll typically have at least one month between signing the contract for your new home and the closing date to shop for homeowners insurance.[4] Mortgage lenders may require proof of homeowners insurance as many as 15 days before closing, so the sooner you get it, the better.[5]
When you close on your loan, your lender may create an escrow account from which your home insurance premiums will be paid. Failure to secure homeowners insurance on time can delay your closing. Your house may be one of the biggest expenses during your lifetime, and you’ll want to make sure it’s covered by an insurance company that strikes the right balance among monthly premiums, coverage, deductibles and customer service.
How To Save Money On Insurance as a First-Time Home Buyer
Shopping around, snagging discounts, and increasing your deductible are common ways for first-time home buyers to save on home insurance.
Shop Around and Do Your Research
Try obtaining at least three to five quotes before choosing an insurance policy. Read reviews for each company to get a better sense of their quality of service. Keep in mind that insurance carriers may request the following information:
- Square footage
- Number of household members
- Personal information, like your credit score and marital status
- Age of the house
- Roof type and age
- Garage details
- Insurance claims history
- Property safety features, like fire alarms, home security systems and sprinklers
- Personal property you want to insure, including jewelry, family heirlooms and antiques
Bundle Home and Auto Insurance
You may be able to save on home and auto insurance by bundling them together, depending on your insurance company. Homeowners that bundle benefit from additional coverages, savings and the convenience of multiple insurance policies housed under a single company.
Insurance companies that offer bundling discounts include:
- Allstate (up to 25%)[6]
- American Family (up to 23% on auto insurance)[7]
- Nationwide (up to 15%)[8]
- Travelers (variable savings)[9]
Increase Your Deductible
Deductibles and monthly premiums typically have an inverse relationship, meaning increasing your deductible will decrease your monthly premium and vice versa. For example, a homeowners policy with a $1,500 deductible should have a lower monthly premium than the same policy with a $500 deductible. While your monthly premiums may be more affordable with a higher deductible, remember that the trade-off is a higher upfront cost when you encounter a covered incident.
Leverage Your Renters Insurance Claims History
If you’ve rented for several years, your renters insurance history may score you a better deal on homeowners insurance. A clear or minimal claims history shows insurance companies that you’re a low-risk homeowner. Individuals who have filed numerous claims, on the other hand, may face higher rates to offset their increased risk profile.
Don’t Let Your Policy Lapse
If you let your policy lapse, you’ll be viewed as a higher risk and face higher premiums when you buy a new homeowners insurance policy or reactivate your old one. Also, if a natural disaster destroys your home while your policy is inactive, you’ll have to take on the entire financial burden of rebuilding your house and replacing your damaged possessions.
Be sure to keep up with your insurance policy’s monthly payments. If you ever have trouble, reach out to your insurer, as you may be able to work out a payment schedule that works better for you.
Are There Programs Available To Assist First-Time Home Buyers?
Several programs are available to first-time home buyers that can help with financing the home purchase or even funding renovation projects. This can be particularly useful for first-time home buyers who may not have the cash on hand to make major home improvements or upgrades.
FHA Loans
Unlike traditional mortgages, FHA loans are backed by the Federal Housing Administration and require lower down payments, potentially as low as 3.5% of the purchase price.[10] This can make it easier for first-time home buyers to enter the housing market and start building equity.
Fannie Mae and Freddie Mac
Both Fannie Mae and Freddie Mac operate under a congressional charter that aims to provide liquidity and stability to the United States housing market. They do this by purchasing mortgages from lenders and packaging them into securities that are then sold to investors.[11] Because of their size and influence, Fannie Mae and Freddie Mac can offer favorable terms to borrowers, including lower interest rates and more flexible underwriting guidelines.
HCV Homeownership Program
Administered by the U.S. Department of Housing and Urban Development (HUD), the Housing Choice Voucher (HCV) program provides eligible low-income families with vouchers that can be used to offset homeownership costs, including home purchase and closing costs. Applicants must meet a family income requirement of less than 50% of the median income in their county or metro area to be eligible for the program.[12]
HUD Section 203(k)
HUD Section 203(k) is a mortgage insurance program beneficial for anyone purchasing a “fixer-upper.” This loan allows the borrower to finance the cost of repairs or renovations, including reconstructing the building, replacing utilities, replacing floors and renovating the outside of the home. There are certain requirements that applicants must meet to qualify for this program, including (but not limited to):[13][14]
- Property must be a least one year old
- Rehabilitation costs must total $5,000 or more
- Total property value must fall within the FHA’s mortgage limit for the area
Energy-Efficient Mortgage
An energy-efficient mortgage (EEM) allows a borrower to purchase an eco-friendly home or finance energy-efficient upgrades to their current home.[15] By making these improvements, homeowners can reduce their energy usage, save money on utility bills and increase their property value.
VA Loans
Veterans may be eligible for different mortgage programs, with the VA purchase loan program being among the most well known. Backed by the U.S. Department of Veterans Affairs, this loan offers several benefits to eligible veterans, including no down payment requirements and lower interest rates. Additionally, VA loans typically do not require private mortgage insurance, which can save veterans thousands of dollars over the life of the loan.[16]
USDA
A USDA loan is a type of mortgage that can be especially helpful for a first-time home buyer looking to purchase a home in an eligible rural area.[17] The loan program, which the U.S. Department of Agriculture backs, offers competitive interest rates and potentially no down payment requirements, making it more accessible for borrowers with limited savings.
- Insurance quotes /
- Home /
- First Time Homebuyers Insurance Guide
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Home Insurance Quote Online Now.
More on Home Insurance

Looking for Home Insurance?
Compare rates from dozens of companies in less than 3 minutes.