

Average Cost of Home Insurance: 2025 Costs by State and Company
 Written & Edited by Dan Marticio Dan MarticioDan Marticio is the content manager at SmartFinancial and has written 150+ articles across multiple insurance verticals.... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Americans pay $2,181 per year on average for homeowners insurance according to Bankrate’s most recent analysis. However, rates can vary widely based on your state, as well as the amount of coverage you buy, your deductible, claims history and other factors.
Keep reading to learn more about the average cost of home insurance by state in 2025 and insurance companies that can offer affordable rates.
|
Key Takeaways
|


What Is the Average Yearly Cost of Homeowners Insurance?
Americans across the nation pay $2,181 per year on average for a homeowners insurance policy with $300,000 in dwelling coverage and a $1,000 deductible. That amounts to an average monthly premium of about $192.[1] However, when you break it down by state, you will find that the average rate can be wide-ranging based on where you live.
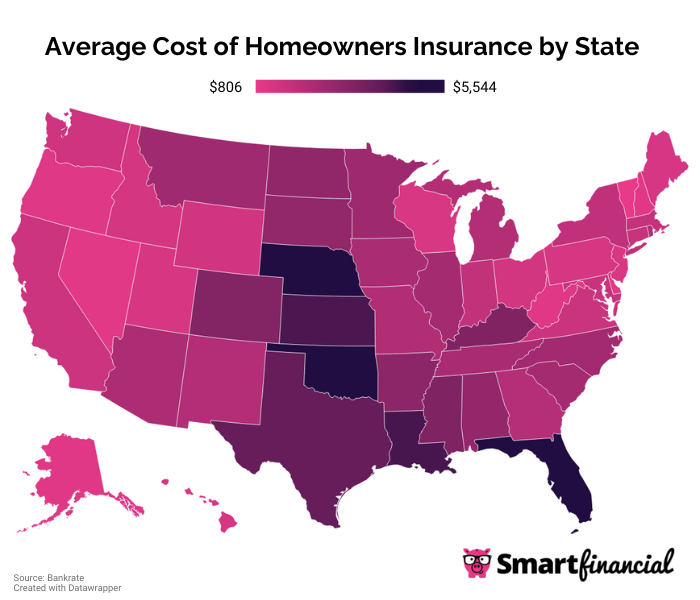
How Much Does Home Insurance Cost in Each State?
The average cost of homeowners insurance can range from $800 to over $4,000 depending on which state you live in.[1]
|
State |
Average Annual Cost |
|---|---|
|
$2,817 |
|
|
$986 |
|
|
$2,229 |
|
|
$2,972 |
|
|
$1,480 |
|
|
$3,222 |
|
|
$1,605 |
|
|
$966 |
|
|
$5,527 |
|
|
$2,014 |
|
|
$1,203 |
|
|
$1,282 |
|
|
$2,407 |
|
|
$1,717 |
|
|
$2,284 |
|
|
$4,241 |
|
|
$3,277 |
|
|
$4,296 |
|
|
$1,227 |
|
|
$1,561 |
|
|
$1,671 |
|
|
$2,040 |
|
|
$2,578 |
|
|
$3,285 |
|
|
$2,117 |
|
|
$2,531 |
|
|
$5,544 |
|
|
$958 |
|
|
$980 |
|
|
$1,162 |
|
|
$2,071 |
|
|
$1,745 |
|
|
$2,459 |
|
|
$2,880 |
|
|
$1,312 |
|
|
$5,049 |
|
|
$1,015 |
|
|
$1,233 |
|
|
$2,094 |
|
|
$2,420 |
|
|
$2,857 |
|
|
$2,321 |
|
|
$3,884 |
|
|
$1,200 |
|
|
$806 |
|
|
$1,520 |
|
|
$1,434 |
|
|
West Virginia |
$995 |
|
$1,198 |
|
|
$1,352 |
|
|
$1,405 |
Which States Have the Cheapest Home Insurance?
The state quoted with the cheapest home insurance rates on average was Vermont at $806 per year, which is less than half the national average of $2,181. Nevada was the next cheapest state ($958), followed by Delaware ($966), New Hampshire ($980) and Alaska ($986).[1]

Which Home Insurance Company Has the Cheapest Home Insurance Rates?
According to Bankrate’s analysis, USAA offers the cheapest home insurance rates on average at $1,451 per year — 33% below the national average rate. However, this insurance company only serves military families. Auto-Owners and American Family are the next cheapest home insurance companies, with their policies costing $1,696 and $1,698 per year on average, respectively.[1][2]
|
Company |
Average Annual Rate |
|---|---|
|
$1,451 |
|
|
Auto-Owners |
$1,696 |
|
American Family |
$1,698 |
|
$1,772 |
|
|
$1,871 |
|
|
National Average |
$2,181 |
What Factors Affect the Cost Of Homeowners Insurance?
In addition to your state, insurance carriers consider other factors when calculating homeowners insurance rates, including your property’s features, ZIP code, deductible and more. See below for a list of underwriting factors that can affect your home insurance premium:
- Home’s age: Older homes may be more expensive to insure than newer ones because they may have hand-crafted features and outdated utility systems that can make it cost more to repair them if damaged.
- Roof condition: Homes with older roofs may cost more to insure since an older roof may not be able to withstand a severe windstorm or hail. Your insurer also considers the roof’s materials, which may be expensive to replace.
- Amenities: Attractive nuisances like trampolines and swimming pools can raise your homeowners insurance rate, since having one can increase the chance of somebody getting injured on your property.
- Coverage limits: Buying more coverage will increase both your protection in the event of a covered claim and your premium.
- Deductible: You can lower your home insurance rate if you pay a higher deductible.
- Credit score: In some states, good-credit homeowners can qualify for lower home insurance premiums. Conversely, insurance companies typically charge higher rates for low-credit homeowners.[3]
- Claims history: Your premium may increase as high as 10% after filing a home insurance claim.[4]
- Pets: If you have a dangerous animal breed, you could pay higher insurance rates. Keep in mind that some insurance companies may exclude coverage for certain dog breeds.
- ZIP code: Homeowners typically pay higher insurance rates if they live in a high-crime area or an area with a high rate of storms, wildfires or other natural disasters. For example, homeowners in Hawaii and California affected by recent wildfires may face higher insurance rates in the future.[5][6] Carriers may also consider how far your home is located from a fire station or police department.
- Discounts: Your insurance company may offer a rate reduction if you install smart home systems, maintain a clear claims history, renew your policy with them or qualify for some other type of discount.
- Additional personal property coverage: Your belongings are typically insured at a percentage of your dwelling coverage, but you can pay extra for additional coverage and to insure valuables like jewelry and antiques that would otherwise be subject to a sublimit.
- Insurance quotes /
- Home /
- What Is The Average Cost Of Homeowners Insurance
Dan Marticio is the content manager at SmartFinancial and has written 150+ articles across multiple insurance verticals. His past experience writing in small business and personal finance verticals has earned him bylines on prominent fintech brands, including LendingTree, ValuePenguin, Fundera, The Balance and NerdWallet. His guides always aim to assist everyday consumers and entrepreneurs make informed decisions about their finances and business.


Get a Free Home Insurance Quote Online Now.
More on Home Insurance

Looking for Home Insurance?
Compare rates from dozens of companies in less than 3 minutes.