

Is Homeowners Insurance Tax Deductible?
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
You cannot deduct homeowners insurance premiums from your taxes unless you own a rental property or operate a business out of your home, in which case the premiums can be deducted as a business expense. Nevertheless, there are several other tax deduction opportunities that a larger number of homeowners can take advantage of.
Keep reading to learn when home insurance is tax deductible and what other expenses you can subtract from your taxable income.
|
Key Takeaways
|


When Is Homeowners Insurance Tax Deductible?
Homeowners insurance is among the expenses you can deduct from your taxes if you operate a home-based business. In general, you can only claim a home office deduction if you regularly and exclusively use a room in your house or a separate structure on your property as your primary workspace and if you are self-employed rather than a remote employee.[1]
If you are eligible for a home office deduction, you have two options for deducting homeowners insurance premiums and other indirect home business expenses on your tax returns:[1]
- The regular method is to calculate the percentage of your home that is devoted to commercial use by comparing the square footage of your home office to the square footage of your entire home. Then, you can subtract that percentage of your premiums from your taxes. For example, if your home office is 150 square feet and your home is 1,500 square feet, you can deduct 10% of your home insurance premiums from your taxes.
- For a simpler calculation, you can instead measure the square footage of your home office and deduct $5 from your taxes for every square foot up to 300 square feet. For example, if your home office is 200 square feet, you can deduct $1,000 from your taxes regardless of the size of your home, the cost of your homeowners insurance policy or the amount you spend on other indirect home business expenses, like repairs and utilities.
Is Home Insurance Tax Deductible on Rental Properties?
Landlord insurance premiums are considered necessary expenses, and you can typically deduct them from your taxes if you own a rental property.[2]
However, suppose you rent out a property you regularly use for personal purposes, such as a vacation home. In that case, you must add up the number of days you rented out the home to determine the portion of the year it was used for commercial purposes and only deduct that percentage of your home insurance premiums from your taxes.[3]
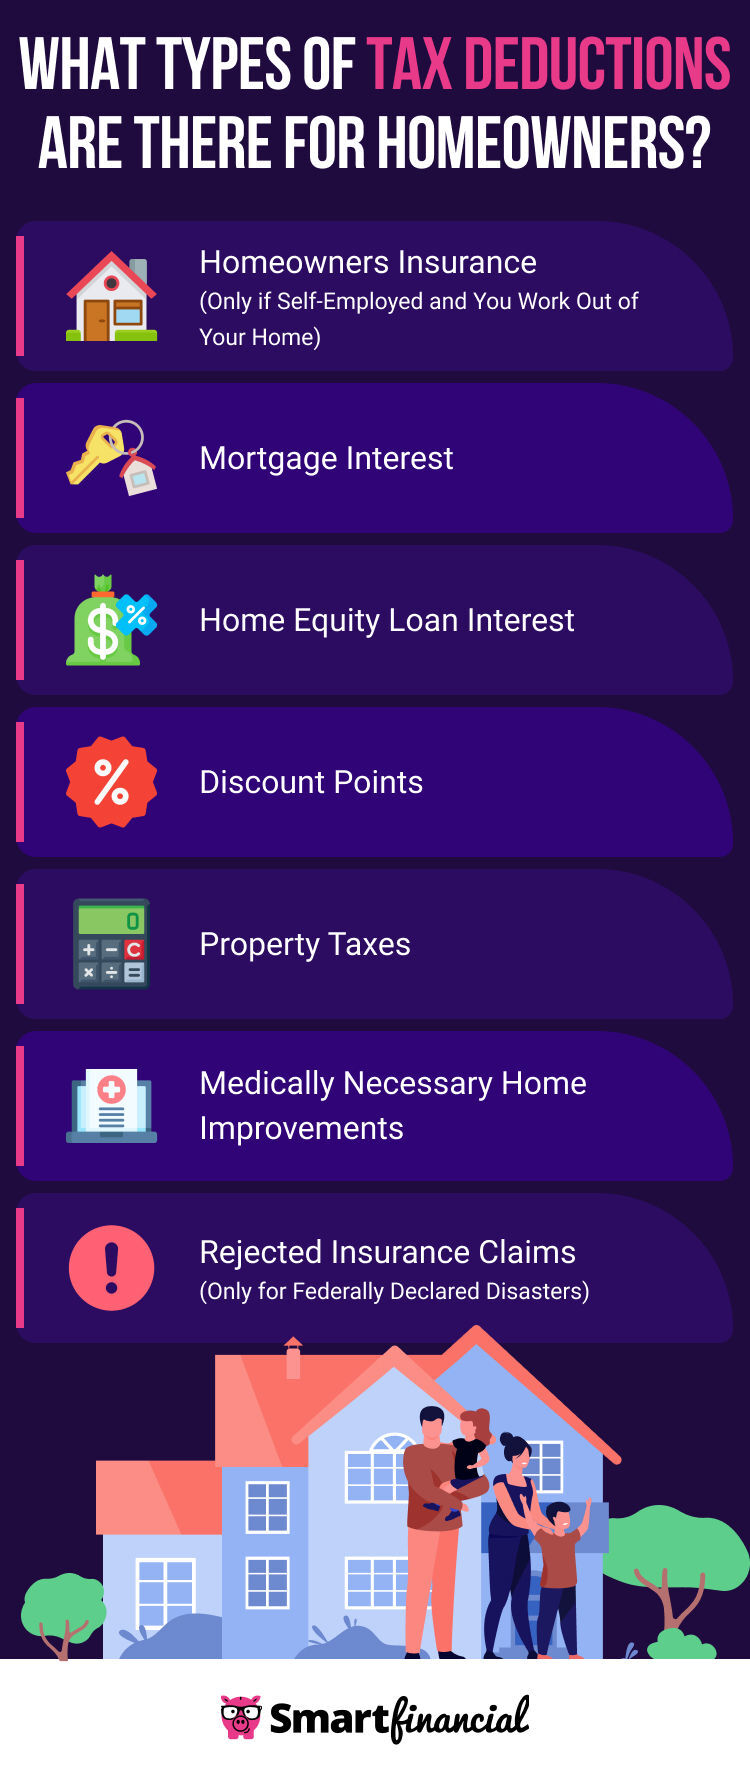
What Types of Tax Deductions Are Available for Homeowners?
Although most homeowners likely won’t be able to deduct home insurance premiums from their taxes, other common expenses for homeowners are tax deductible, which are discussed in the section below. That said, you should only deduct these expenses if they collectively exceed the standard deduction — which is a blanket amount that most taxpayers can deduct from their taxable income — since you can’t take both the standard deduction and itemized deductions.
See the below table for an overview of the standard deductions for tax returns filed in 2025 based on your tax filing status.[4]
|
Tax Filing Status |
Standard Deduction |
|---|---|
|
Single or married filing separately |
$14,600 |
|
Head of household |
$21,900 |
|
Married filing jointly |
$29,200 |
Mortgage Interest
You can deduct interest that your home mortgage has accrued up to certain limits based on your tax filing status and when you took out the mortgage. The table below covers the maximum amount of loan debt you can deduct interest from for tax purposes, depending on your circumstances.[5]
|
Tax Filing Status |
Date You Took Out the Mortgage |
Amount of Debt You Can Deduct Interest From |
|---|---|---|
|
Married filing separately |
December 16, 2017, or after |
$375,000 |
|
Other tax filing statuses |
December 16, 2017, or after |
$750,000 |
|
Married filing separately |
Before December 16, 2017 |
$500,000 |
|
Other tax filing statuses |
Before December 16, 2017 |
$1 million |
Previously, you were also allowed to deduct the amount that you paid for private mortgage insurance from your taxes. However, itemized deductions for private mortgage insurance premiums expired after December 31, 2021, and they can no longer be claimed.[6]
Home Equity Loan Interest
You can only deduct interest that a home equity loan has accrued if you used the loan to buy, build or substantially improve a house. However, after the 2025 tax year, you’ll be able to deduct home equity loan interest from your taxes up to a certain dollar amount, no matter how you spend the money from the loan.[7]
Discount Points
You may also be able to deduct discount points, which are basically a form of prepaid interest because they allow you to pay a certain amount of money up front to lower the interest rate on your monthly mortgage payments. Each point you purchase is generally worth 1% of the value of your mortgage.[8]
Discount points are not universally tax deductible, but you may be able to deduct them under certain circumstances. For example, your points are tax deductible when the amount of points you buy is not higher than normal for your area and when you pay for the points yourself rather than borrowing money to pay for them.[9]
Property Taxes
You can take itemized deductions for multiple kinds of state and local taxes, including property taxes, enabling you to subtract the amount you spend on these taxes from the income you pay federal taxes on. The combined income, sales and property taxes you deduct cannot be more than $5,000 if you are married filing separately or $10,000 if you have another tax filing status.[10]
Medically Necessary Home Improvements
Home accessibility upgrades are tax deductible as medical expenses as long as they primarily provide medical care for you, your spouse or a dependent. You can deduct the installation cost minus any increase to your property value caused by the upgrade.[11] For example, if you spend $3,000 to install a wheelchair ramp and raise your property value by $1,000, you can deduct $2,000 from your taxes.
Rejected Insurance Claims
In some cases, you can deduct the value of damaged and stolen property incurred during a disaster declared by the federal government if your insurance company declines to reimburse you after you file a homeowners insurance claim within a reasonable timeframe.[12]
Meanwhile, if your insurer doesn’t pay the full amount required to repair or replace the property, you may be able to deduct the difference between your insurance settlement and the actual cost of repairs or replacements. If your loss is eligible, you can deduct the value of the lost property minus any reimbursements from your insurance company minus $100 per casualty or theft event minus 10% of your adjusted gross income (AGI).[12]
For example, if your home incurs $10,000 worth of damage during a flood that isn’t covered by your homeowners insurance policy and you have an AGI of $50,000, you might be able to deduct $4,900 from your taxes.
Which Homeowners’ Costs Aren’t Tax Deductible?
Unless they qualify as business expenses due to your operation of a home-based business, the following expenses cannot be written off on your taxes:[13]
- Insurance premiums
- Wages you pay a domestic worker
- Depreciation
- Utility costs
- Most types of settlement or closing costs
- Money you’ve forfeited such as deposits, down payments or earnest money
- Home internet
- Homeowners association or condo fees
- Basic home repairs
- Insurance quotes /
- Home /
- Is Homeowners Insurance Tax Deductible
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Home Insurance Quote Online Now.
More on Home Insurance

Looking for Home Insurance?
Compare rates from dozens of companies in less than 3 minutes.