

Will My Homeowners Insurance Policy Cover Floods?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Dan Marticio Dan MarticioDan Marticio is the content manager at SmartFinancial and has written 150+ articles across multiple insurance verticals.... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Standard homeowners insurance policies don’t cover flooding in most cases but may cover water damage from other sources like windstorms or snowstorms. Since home insurance doesn’t cover floods, you need to purchase separate flood insurance from either the federal government or a private insurance company for more thorough protection against flood damage.
Keep reading to learn more about flood insurance, including what it covers and how much it costs, along with how you can evaluate your home’s exposure to flood damage.
|
Key Takeaways
|


Does Home Insurance Cover Floods?
A standard homeowners insurance policy will not cover damage from floodwaters. Flooding is not among the named perils that your belongings are insured against under the personal property coverage portion of your policy. While your dwelling coverage will typically insure the structure of your home on an open peril basis, floods are usually among the excluded perils that your insurance company will explicitly refuse to cover.
What Is Considered Flood Damage to Insurance Companies?
Sources of flood damage that your home insurance company likely won’t cover include heavy rain, high tides, overflowing rivers and mudflows. That said, your insurer may cover flood damage in cases where the flooding can be attributed to another peril that is covered by your policy. For example, insurers in California are required to cover damage from floods and mudflows that are predominantly caused by covered wildfires.[1]
What’s the Difference Between Flood Damage and Water Damage in Insurance?
While flood damage is usually listed as an insurance exclusion, your insurance carrier may cover other types of water damage caused by perils your policy covers. Below are some examples of perils that could result in water damage and that are commonly covered by homeowners insurance.
|
Peril |
Example |
|---|---|
|
Heavy winds blow a chunk of hail through your window and then rain enters through the shattered window |
|
|
Falling objects |
A large tree branch falls on your roof amid a thunderstorm, allowing a significant amount of rainwater to get into your home |
|
Weight of ice, sleet or snow |
Snow builds up on your roof and creates an ice dam, causing water to leak through your roof |
|
Theft and/or vandalism |
Someone breaks into your home by kicking the door down while you’re away on vacation, leaving your house vulnerable to rain damage |
|
Water/steam discharge from home systems and appliances |
Your pipes suddenly burst and cause your basement to flood |
|
Freezing of home systems |
Standing water freezes in your pipes and then leaks once the pipes thaw |
Conversely, some types of water damage unrelated to floods may still be excluded from coverage. For example, homeowners insurance generally doesn’t cover water damage from artificial sources outside of your home, like a broken sump pump or sewer backup. In addition, your insurer generally won’t cover damage that results from poor maintenance on your part, such as water damage that stems from a leaky roof that you neglected to fix for months.
What Type of Insurance Do I Need if I Live in a Flood Zone?
To insure your home and belongings against flood damage, you will typically need to purchase a standalone flood insurance policy. If you purchase flood insurance with both building and contents coverage from the National Flood Insurance Program (NFIP), your policy may provide flood damage coverage for the following:[2]
- Electrical and plumbing systems
- Furnaces and water heaters
- Kitchen appliances like refrigerators, stoves, microwaves and dishwashers
- Permanently installed cabinets, panels and bookcases
- Window blinds and curtains
- Foundational walls and anchorage systems
- Staircases
- Garages that are affixed or detached
- Fuel tanks, wells, pumps and solar panels
- Clothing, furniture and electronics
- Laundry machines
- Air conditioners
- Carpets
- Valuables like artwork and furs (with a $2,500 sublimit)
Of course, like a traditional homeowners policy, flood insurance policies often come with a list of exclusions. Below are some of the things that NFIP flood insurance typically won’t provide coverage for:[2]
- Sewer backups that aren’t directly caused by a flood
- Additional living expenses while your house is being repaired
- Swimming pools, fences, decks and most other structures outside of the insured building
- Currency, precious metals, stock certificates and other valuable papers
- Vehicles and their parts
- Personal property stored in basements
Homeowners in high-risk flood zones with government-backed mortgages are required to buy flood insurance, and homeowners in other areas may also have to do so if their mortgage lenders require it. Additionally, if you live in a high-risk area and receive federal assistance after a natural disaster, you will not be eligible for future disaster aid unless you maintain flood insurance.[3]
How Do I Know if My Home Is in a Flood Zone?
You can input your address into the Federal Emergency Management Agency (FEMA) Flood Map Service Center to determine if your home is located in a flood zone. Areas marked with the letter A or V are high-risk flood zones with a 25% chance of experiencing at least one flood during the course of a 30-year mortgage, while the letters B, C and X indicate moderate-to-low-risk flood zones.[4]
If you live in a valley, near a large body of water or in a city where it frequently rains, it may be worth checking to see if you are in a high-risk flood zone. Keep in mind that you will likely have to pay higher flood insurance premiums if you live in a high-risk flood zone, since there is a greater chance that you will have to file a claim on your flood insurance policy.
What Options Do I Have To Get My Home Covered for Floods?
There are both public and private options for obtaining flood insurance coverage. As of 2023, about 55% of homeowners with flood insurance have government-backed policies through the NFIP.[5] You should note that FEMA partners with private insurance companies and agents to sell NFIP policies rather than selling policies directly to consumers.
Meanwhile, about 45% of flood insurance policyholders are covered by private insurers that underwrite their own policies.[5] While they lack the guaranteed backing of the federal government, private flood insurance policies still have numerous benefits, such as higher coverage limits, the inclusion of loss of use coverage and unattached structures coverage and often lower monthly premiums.[6]
How Much Does Flood Zone Insurance Cost?
The median cost of NFIP flood insurance throughout the United States is $786 per year as of September 2023.[7] Your personal rates will depend on factors like the risk of flooding in your area, the coverage types included in your policy and the elevation of your home, along with other characteristics of your property.[8]
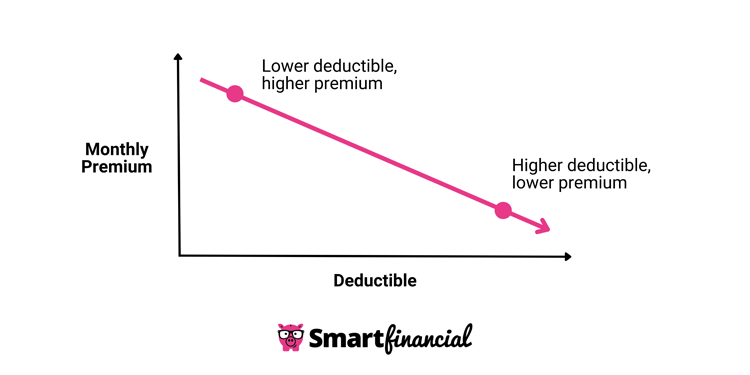
Some of the steps you could take to lower your flood insurance premium include moving to a new home in a lower-risk area, elevating your house and/or utilities, raising your deductible or working with others in your community to implement flood damage mitigation efforts, among other things.[9]
How To Assess Your Home’s Risk for Flooding
The best way to assess your home’s risk for flooding is to look at FEMA flood maps online and determine what kind of flood zone your house is situated in. Some of the factors that influence your home’s flood damage risk include the following:[4]
- Frequency of floods in your area
- Distance from your home to the nearest body of water
- Elevation of your home and foundation compared to the surrounding area
- Whether you have wood frame or masonry walls
- Whether you have flood openings in your crawl space
- Where your electrical and heating, ventilation and air conditioning (HVAC) systems are located
- Insurance quotes /
- Home /
- Homeowners Insurance Cover Floods
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Home Insurance Quote Online Now.
More on Home Insurance

Looking for Home Insurance?
Compare rates from dozens of companies in less than 3 minutes.