

Is My Home in a Flood Zone? Understanding FEMA Flood Maps
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
The Federal Emergency Management Agency (FEMA) has mapped the United States to help communities and residents understand the threat of flooding. These maps categorize areas into flood zones based on the likelihood of a flood occurring. Depending on your location’s risk level, you may be required to purchase — or may otherwise want to consider buying — flood insurance to protect your home and avoid severe out-of-pocket expenses after a flood.
Learn about the different flood zones and whether you may need flood insurance coverage.
|
Key Takeaways:
|


What Is a Flood Zone?
A flood zone is an area’s categorization of flooding risk, often determined by topography, weather patterns and proximity to water sources. FEMA designates areas as flood zones with high or low-to-moderate risk to help communities understand and prepare for potential dangers. Flood zones also often help determine insurance requirements for households within the area and may influence insurance costs.[1]
How Many Flood Zones Are There?
FEMA designates five categories of flood zones, each based on the level of flood risk over one year or the life of a 30-year mortgage.[1] Zones may also be based on location, such as areas with a high risk for coastal flooding. On a flood zone map, which shows the likelihood of flooding in an area, zones are labeled using the following letters:[1]
- Low risk: Zones C and X (unshaded)
- Moderate risk: Zones B and X (shaded)
- High risk: Zone A
- Coastal high risk: Zones V or VE
- Undetermined risk: Zone D
Which Flood Zone Is the Safest To Live In?
Floods can occur in any flood zone, but the lowest risk is typically found in low-risk zones, including Zones C and X. However, on a flood map, only Zone X areas marked as unshaded are considered to have a minimal chance of flooding.[1]
Even areas that are landlocked or far from bodies of water can still experience flooding, such as flooding caused by heavy rain, poor drainage or nearby construction projects.[2] Homeowners in moderate-to-low-risk flood zones remain vulnerable, with 25% of all flood insurance claims coming from these areas.[3]
Which Flood Zone Is the Most Dangerous?
The flood zones with the highest risk of flooding are labeled as Zone A, Zone V or one of their subcategories. These areas have a 1% or higher chance of flooding each year.[1]
Homeowners in high-risk zones are required to buy flood insurance if their mortgage is federally backed or comes from a federally regulated lender.[1]
What Flood Zone Am I In?
FEMA’s Flood Map Service Center tool helps you determine your flood zone.[4] This digital map allows you to view flood zones and risk levels for your home or any other location in the United States.
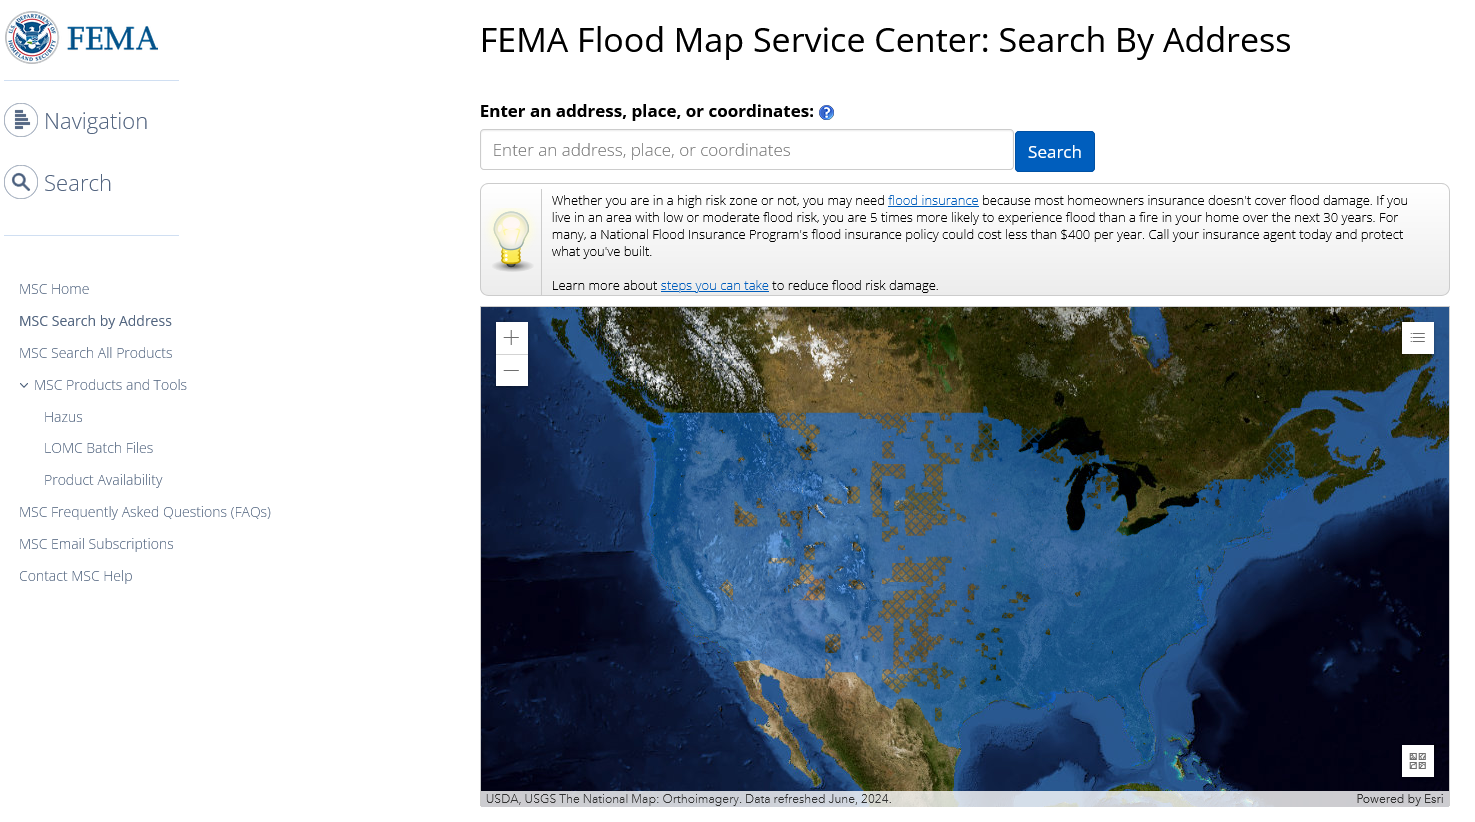
After navigating to FEMA’s website, enter your home address or another location into the search bar. The map will then navigate to the requested location and indicate the area's flood risk. The reference key for the map helps you determine this risk for the area.
Flood zones are not static and may change due to environmental factors, new developments, changes in levee classification and other conditions. Because these classifications can change, it’s important to monitor updates to your local flood zone. A change in classification may require you to purchase flood insurance if you have a federally backed mortgage.[5]
Flood Zones According to FEMA
Below is a breakdown of each flood zone category, including its risk level and whether insurance may be required. Private lenders may also require flood insurance, even if you live in a moderate-to-low-risk area for flooding.[7]
Flood Zone C and Zone X (Unshaded)
If you live in an area designated as Zone C or X (must be unshaded on a flood zone map), then your area has the lowest risk of flooding compared to all other zones. Homes in these areas have less than a 0.2% chance of flooding in a given year, so flood insurance is generally not required.[1]
Flood Zone B and Zone X (Shaded)
FEMA designates areas with a 0.2% to 1% chance of flooding in any given year as Zone B or Zone X (shaded). These areas are considered to have a moderate risk of flooding. While the risk is higher than in Zones C or unshaded Zone X, homes in Zones B and X (shaded) are still relatively safe, and flood insurance is usually not required.[1]
Flood Zone A
Zone A areas are designated as high-risk flood areas, also called special flood hazard areas (SFHAs). These areas have a 1% chance of flooding in any given year or a 26% chance over the life of a 30-year mortgage. Zone A includes several subcategories — AE (which may appear as Zone A1-30 on older maps), AR, A99, AH and AO — based on specific factors such as the type of flood, potential flood elevations or flood depths.[1]
Homeowners with federally backed mortgages whose homes are located in Flood Zone A areas are required to have flood insurance.[1]

Zone V
Zone V is similar to Zone A, but with the key difference that flooding in Zone V is based on coastal hazards, such as storm waves. Similar to Zone A, the annual risk of flooding in a Zone V area is 1% or higher. Zone V also includes subcategories based on environmental factors, including VE and V1-V30.[1]
Homeowners with federally backed mortgages whose homes are located in a Flood Zone V area are required to have flood insurance.[1]

Flood Zone D
Zone D is an outlier because some areas have not been studied, so the flood risk is unknown. Despite this uncertainty, flooding in Zone D is still possible, and residents should take precautions; however, flood insurance is not a legal requirement.
Do Flood Zones Affect Home Insurance Rates?
If your property is in a high-risk flood zone, you can expect to pay higher insurance premiums than if it’s in a low-risk zone.[8] Insurers may factor in your property’s risk level — including its location, elevation above the ground and history of flooding in the area — when determining your home insurance rates.
Can I Get Home Insurance in All Flood Zones?
Homeowners insurance is typically available regardless of your flood zone. However, standard homeowners insurance typically doesn’t cover flooding. You will need a separate policy for flood coverage.[9]
How To Get Flood Insurance
You can buy flood insurance from private insurance companies or through the National Flood Insurance Program (NFIP). NFIP policies are sold in partnership with private companies, but FEMA underwrites the policy. To purchase NFIP insurance, visit FEMA’s website to find a list of companies authorized to sell FEMA-backed flood insurance.[10]
If you choose to purchase flood insurance through a private insurer, you should compare quotes from at least three to five companies. This helps you get a range of rate options, as each insurer may use different factors when underwriting. You’ll typically need to provide each insurer with your location and property value.
Keep in mind that private insurers who sell and administer government-funded NFIP policies may not offer unique quotes. Be sure to confirm whether each private insurer you speak with underwrites its own policies when gathering quotes.
- Insurance quotes /
- Home /
- What Are Flood Zones
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Home Insurance Quote Online Now.
More on Home Insurance

Looking for Home Insurance?
Compare rates from dozens of companies in less than 3 minutes.