

What Types of Insurance Do I Need as a Landlord?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Landlords need to purchase commercial insurance policies that include coverage for sudden damage to their rental properties, lost rent payments due to covered perils and expenses related to liability claims. A landlord insurance policy is generally similar to standard homeowners insurance, but you may be able to add endorsements to match the specific needs of your rental property business.
Keep reading to learn about the various types of business insurance for landlords and what policy exclusions you should expect.
|
Key Takeaways
|


What Is Landlord Insurance?
Landlord insurance refers to a commercial insurance policy that provides property damage and liability coverage for business owners who rent out the homes they own. A typical landlord insurance policy includes many of the same — or similar — coverage types as a standard homeowners insurance policy, but it could also include business insurance add-ons specifically tailored to the needs of landlords.
Property coverage for landlords is available through specialized home insurance policies known as dwelling fire policies — abbreviated as “DP.” There are three types of dwelling fire policies you can choose from, with DP-1 insurance providing the most limited coverage and DP-3 insurance providing the most expansive coverage.[1]
What Types of Insurance Do Landlords Need?
These are some of the most important coverage types that you need to make sure are included in your landlord insurance policy:[2][3][4]
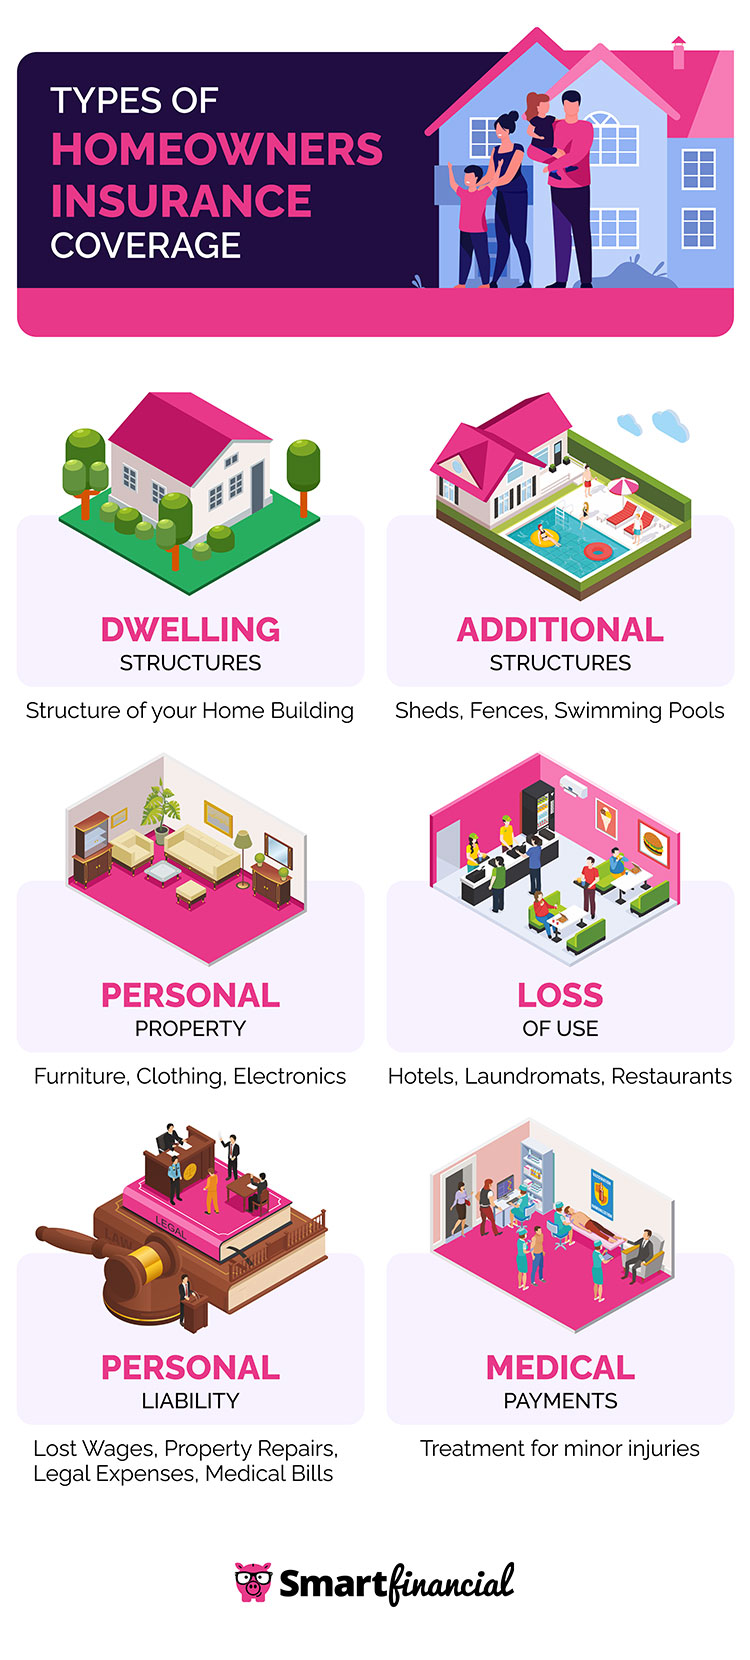
- Dwelling: Dwelling insurance covers sudden and unexpected damage to the structure of the homes you rent out or any structures directly attached to them, such as patios or carports. While your dwelling coverage limit should generally be set at the replacement cost of the home, you may be able to raise your coverage limit by up to 50% by purchasing extended replacement cost coverage. This offers valuable protection in case inflation drives up rebuilding prices after you set your coverage limit.
- Other structures: Other structures coverage can help you repair or replace damaged structures on your property that aren’t directly connected to the home, such as fences, sheds or swimming pools.
- Personal property: Personal property insurance covers the sudden loss of items that a landlord owns and stores on their rental property. Keep in mind that some landlord insurance carriers will only cover items that you use to maintain the property, such as lawn mowers.
- Fair rental value: Fair rental value insurance is similar to the loss of use coverage portion of a standard home insurance policy. If your rental property is rendered uninhabitable by a covered peril, fair rental value coverage can make up for lost rent payments while your tenants are away.
- General liability: A landlord insurance policy can provide coverage for numerous types of general liability claims, including bodily injury, property damage and personal or advertising injury that you are accused of causing to others. Some insurers may also offer medical payments coverage, which covers medical treatments for guests who are injured on your property but do not live there.
Other Types of Rental Property Insurance for Landlords
Several other coverages may be worth considering for your landlord insurance policy, such as the following:[2][3][4][5]
- Loss assessment: Loss assessment coverage can take care of your share of the costs if your homeowners association (HOA) issues a special assessment to cover damage to a common area caused by a covered peril.
- Service line: You may need extra service line insurance to cover the most common sources of damage to water, gas, electric and sewer lines.
- Builders risk: If you own a property that is currently under construction, you may need to buy builders risk insurance to cover sudden damage to the construction project.
- Building code upgrade: Also known as ordinance or law coverage, building code upgrade insurance can extend your dwelling coverage limit after a covered loss if you experience additional costs associated with bringing the new home up to local building codes.
- Equipment breakdown: Equipment breakdown coverage insures business-owned machinery and systems against certain perils that your commercial property insurance won’t cover, like mechanical breakdowns and other internal malfunctions.
- Valuable papers and records: When a covered peril results in the loss or destruction of important documentation for your business, valuable papers and records coverage can help pay to research, replace or otherwise restore the lost information.
- Commercial auto: Any vehicles you use to operate your rental property business will likely be excluded from coverage under your personal auto insurance, so you’ll also need to purchase a commercial auto insurance policy.
- Commercial umbrella: Commercial umbrella insurance can provide extra coverage for various types of liability claims against your business. For example, it can step in if either a general liability or commercial auto liability claim exceeds the limits of your base policy.
- Data compromise and identity restoration: Losses related to data breaches and identity theft aren’t covered by basic homeowners or landlord insurance policies, so you may want to consider buying a data compromise and identity restoration endorsement.
- Home-sharing: A home-sharing coverage endorsement may be necessary to extend your property and personal liability insurance to a home you temporarily rent out through a home-sharing service, like Airbnb.
- Water backup: Without water backup coverage, you could have to pay 100% of the cleanup costs if a sewer backup or sump pump overflow results in water damage to your plumbing system or other parts of your home.
- Flood and earthquake: Standard landlord insurance policies don’t cover property damage caused by floods or earthquakes. Depending on your exposure to these natural disasters, you may want to purchase commercial flood and/or earthquake insurance to make sure you’re fully covered.
How Does Landlord Insurance Work?
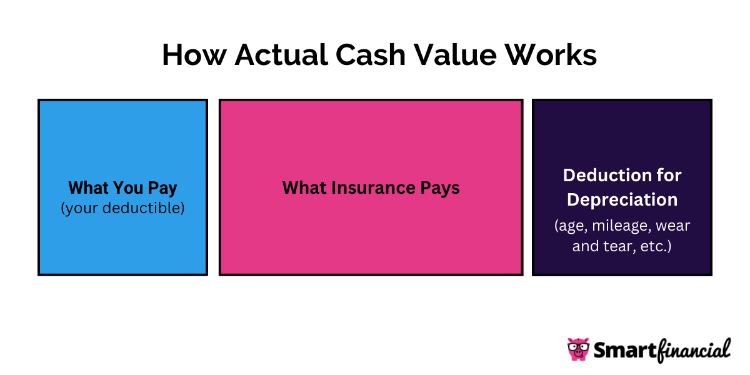
Depending on the type of policy you select, your property may be insured at its actual cash value (ACV) or replacement cost value (RCV). An RCV policy will cover whatever it costs to replace destroyed or stolen property, while an ACV policy will subtract money from your insurance settlement based on depreciation factors, such as the age of the lost property.
When you file a claim on your landlord insurance policy, you are responsible for a minimum out-of-pocket contribution known as a deductible, which is subtracted from your overall insurance payout. For example, if you have a $1,000 deductible and file a claim for $15,000 worth of covered property damage, your insurance settlement should be $14,000.
What Does Landlord Insurance Cover?
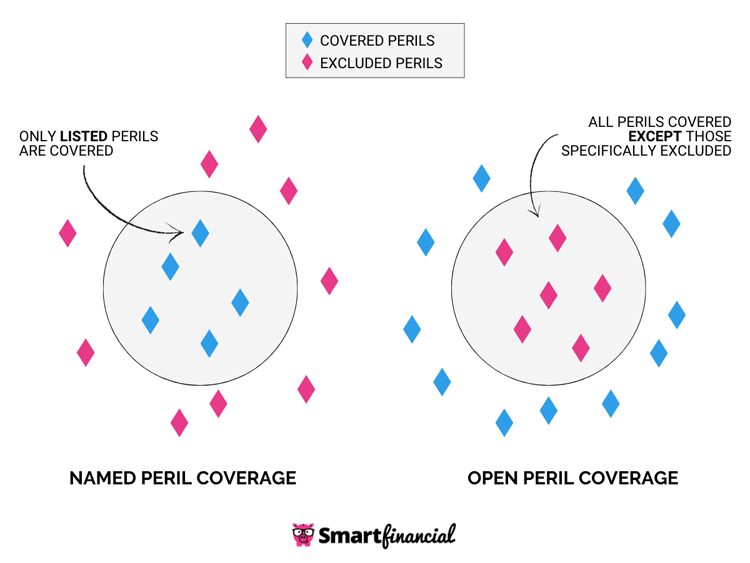
The perils covered by your landlord insurance policy may depend on the level of coverage you select. DP-1 policies typically only cover damage caused by the following named perils:[1]
| Fire or lightning | Damage by aircraft |
| Windstorm or hail | Damage by vehicle |
|
Explosion |
Smoke |
| Riot or civil commotion | Volcanic eruptions |
Because of the limited coverage they provide, DP-1 policies are primarily recommended if your rental property will be vacant for an extended period of time.[1] Meanwhile, DP-2 policies may include coverage for more than twice as many hazards, depending on your insurance company. Additional perils that may be covered by DP-2 insurance include the following:[6]
| Vandalism or malicious mischief | Freezing of home systems |
| Falling objects | Sudden/accidental power surges |
|
Weight of ice, sleet or snow |
Damage by burglars |
| Water/steam discharge from home systems and appliances | Glass breakage |
| Sudden/accidental tearing, cracking, burning or bulging of home systems | Structural collapse |
Finally, DP-3 policies offer the most comprehensive protection by insuring your property on an open peril basis. This means your insurance company will reimburse you for any source of damage to a house, apartment or condo unit you rent out unless the peril is explicitly named as an exclusion in your policy documents.[1]
What Isn't Covered?
Landlord insurance exclusions can vary from insurer to insurer. For example, some insurance companies won’t cover damage from vandalism or burglary of an unoccupied home unless you buy extra coverage. Meanwhile, landlord coverage may not apply to shared property, like if you rent out a room in your primary residence.[3]
Regardless of your insurance carrier, you shouldn’t expect your landlord policy to cover regular wear and tear or damage stemming from poor upkeep. In addition, your policy generally won’t provide any coverage for your tenants’ personal property — as a result, your tenants should consider purchasing their own renters insurance.[2]
How Much Does Landlord Insurance Cost?
In general, rental dwelling insurance policies cost roughly 25% more than standard homeowners insurance.[7] This places the average premium for a landlord insurance policy with $300,000 worth of dwelling coverage around $2,926 per year as of June 2025.[8] Keep in mind that your exact prices will depend on factors like your location, the details of your policy, the age of the covered home and your claims history.
How To Get Landlord Insurance
To make sure you’re getting the best deal on the coverage you need, it’s recommended that you compare quotes from around three to five different landlord insurance companies. However, this can be a daunting task, as you will potentially have to collect all of the information you need to obtain a quote and individually give it to several different insurers.
For a more streamlined insurance shopping process, go through SmartFinancial. You’ll only need to gather and share your information one time, after which we’ll connect you with an agent who can help you find the landlord insurance policy that makes the most sense for you. Compare business insurance quotes at no cost today!
- Insurance quotes /
- Commercial /
- Landlord Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Commercial Insurance Quote.
More on Commercial Insurance

Looking for Commercial Insurance?
Compare rates from dozens of companies in less than 3 minutes.