

Hurricane Insurance: Is Your Home Insurance Policy Enough To Withstand a Storm?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
While there is no singular coverage type known as hurricane insurance, there are multiple types of insurance you can purchase to secure broad protection against hurricanes. Home insurance covers numerous hurricane-related perils — including wind and falling objects — but you may need flood insurance and potentially windstorm insurance to plug holes in your homeowners coverage, depending on where you live.
Read on to learn more about hurricane insurance for homeowners, including how much you may have to pay for coverage and when special deductibles may apply to your claims during hurricane season.
|
Key Takeaways
|
On This Page

What Is Hurricane Insurance?
Types of Hurricane Coverage for Homeowners
What Isn’t Covered by Hurricane Insurance?
How Much Does Hurricane Insurance Cost?
Hurricane Insurance Deductibles
Who Needs Hurricane Coverage?
Hurricane Insurance at a Glance
How To Get Hurricane Coverage for Your Home
Frequently Asked Questions

What Is Hurricane Insurance?
Hurricane insurance refers to a collection of property insurance policies that can protect your home and belongings against various types of damage caused by hurricanes. There isn’t a singular insurance product or homeowners insurance endorsement known as hurricane insurance — instead, you’ll likely need multiple coverages to adequately insure your property against hurricane damage.
Types of Hurricane Coverage for Homeowners
For the most comprehensive protection from financial losses caused by hurricanes, you’ll need to purchase homeowners insurance, flood insurance and potentially windstorm insurance, depending on your location.
|
Type of Hurricane Coverage |
What It Covers |
|---|---|
| Homeowners insurance | Damage to your property caused by wind, falling objects and potentially other perils stemming from hurricanes, such as fire, theft, vandalism or damage from vehicles |
| Flood insurance | Damage to your property caused by floods, heavy rainfall and storm surges |
| Windstorm insurance | Wind and hail damage to properties in high-risk regions where wind coverage is excluded from standard homeowners insurance policies |

Homeowners Insurance
A standard homeowners insurance policy covers your property against several different perils that could be caused by a hurricane, such as the following:[1]
- Wind
- Fires and explosions caused by downed power lines
- Theft or vandalism that occurs after you evacuate
- Falling objects, such as trees or branches
- Damage caused by someone who crashes a vehicle into your house while trying to drive during severe weather
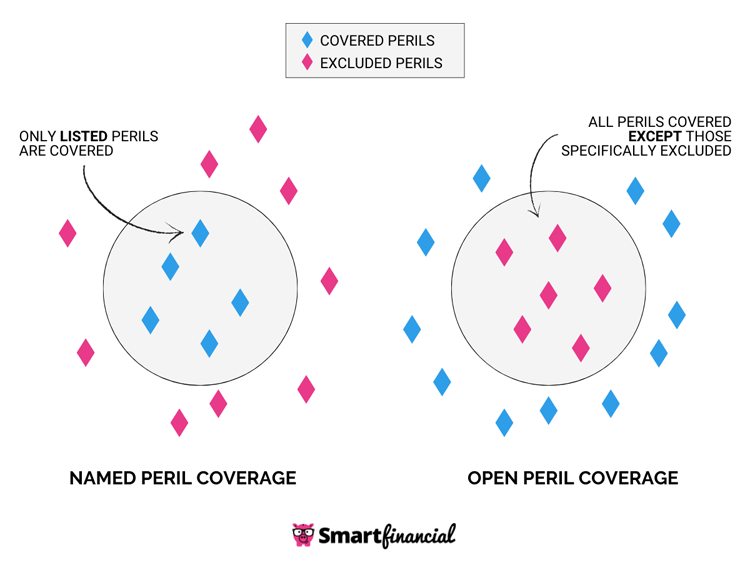
Home insurance doesn’t cover gradual rain damage, but it may cover water damage linked to a sudden peril, like a falling branch that breaks a window and allows wind-driven rain to enter your home.[2] Keep in mind that dwelling and other structures insurance typically provide open peril coverage, meaning your home and other structures on your property are insured against all sources of damage unless they are expressly excluded from coverage.
Conversely, personal property insurance usually provides named peril coverage, which means it only covers damage to your belongings from perils that are expressly named in the policy documents. Meanwhile, loss of use insurance can cover hotel stays, restaurant meals and other additional living expenses that come up if a hurricane renders your home uninhabitable.
Flood Insurance
Most homeowners insurance policies exclude coverage for flooding caused by heavy rains, storm surges and other external water sources, so you’ll need a separate flood insurance policy to cover your home and belongings against floodwaters created by a hurricane. You may be able to secure flood coverage through the private market or the federal government’s National Flood Insurance Program.[1]
NFIP coverage is split into two distinct coverage types: building coverage for the physical structure of your home and contents coverage for the items inside your home. See the following table for a rundown of what types of property are covered by each of these flood insurance coverage types:[3]
|
Covered by Building Coverage |
Covered by Contents Coverage |
|---|---|
| Electrical and plumbing systems | Clothes, furniture and electronics |
| Furnaces and water heaters | Curtains |
| Refrigerators, stoves, dishwashers and other built-in appliances | Washers and dryers |
| Permanently installed carpets, panels, cabinets and bookcases | Portable air conditioners and window units |
| Window blinds | Microwaves |
| Foundation walls, anchorage systems and stairs | Carpets installed over wood floors |
| Detached garages | Valuable items, such as art and furs (with a $2,500 sublimit) |
| Fuel tanks, solar panels, well water tanks and well water pumps | Merchandise and raw materials held in storage or for sale (only for home-based business owners) |
Windstorm Insurance
Although wind coverage is automatically included in a standard home insurance policy, insurance companies may exclude coverage for wind and hail in regions that are especially prone to damage from these perils, such as the Texas Gulf Coast.[5] As a result, you may need to buy a separate windstorm insurance policy to insure your home and belongings against wind damage, depending on where you live.
Since homes that need standalone windstorm insurance are inherently risky to insure, you may only be able to obtain coverage from your state’s government-sponsored insurer of last resort. Examples of programs that offer windstorm coverage include the following:[6]
- Alabama Insurance Underwriting Association
- Insurance Placement Facility of Delaware
- Citizens Property Insurance Corporation
- Mississippi Windstorm Underwriting Association
- Coastal Property Insurance Pool
- South Carolina Wind and Hail Underwriting Association
- Texas Windstorm Insurance Association
What Isn’t Covered by Hurricane Insurance?
Even if you have all three types of hurricane disaster insurance, certain hurricane-related property losses still may not be covered. Here are some examples of common hurricane insurance exclusions:[7]
- Gradual damage, such as mold or mildew buildup
- Wind or flood damage to your vehicles (covered by comprehensive car insurance instead)
- Flood damage to most types of outdoor property, such as landscaping, pools and fences
- Losses that can be attributed to poor maintenance
How Much Does Hurricane Insurance Cost?
The amount you have to pay for hurricane insurance coverage depends on your combined premiums for home insurance, flood insurance and — if applicable — windstorm insurance. As of June 2026, the national average cost of homeowners insurance with a $300,000 dwelling coverage limit is $2,424 per year.[8] Meanwhile, NFIP flood insurance costs an average of $926 per year as of July 2025.[9]
Standalone windstorm insurance premiums may vary based on factors like your location, your policy details and the materials used to build your home. As an example, residential windstorm policies from the Texas Windstorm Insurance Association cost an average of $2,877 per year as of March 2026.[10] In general, you can expect windstorm insurance to be expensive because it is primarily designed for high-risk homeowners.
Factors That Impact the Cost of Hurricane Insurance
These are some of the most significant factors that may affect how much you have to pay for hurricane coverage:[7]
- Location, including how close your home is to the coast and whether you live in a high-risk flood zone
- Home replacement cost
- Construction type and age of your home
- Condition of your roof
- Policy details, including the coverage limits and deductibles you select
- Whether your home insurance automatically includes wind coverage
- Home improvements or upgrades installed to make your home more resistant to hurricanes
Hurricane Insurance Deductibles
In high-risk regions, homeowners insurance policies may come with a separate deductible for hurricane-related claims, leading to more out-of-pocket costs for policyholders in the event of a hurricane.
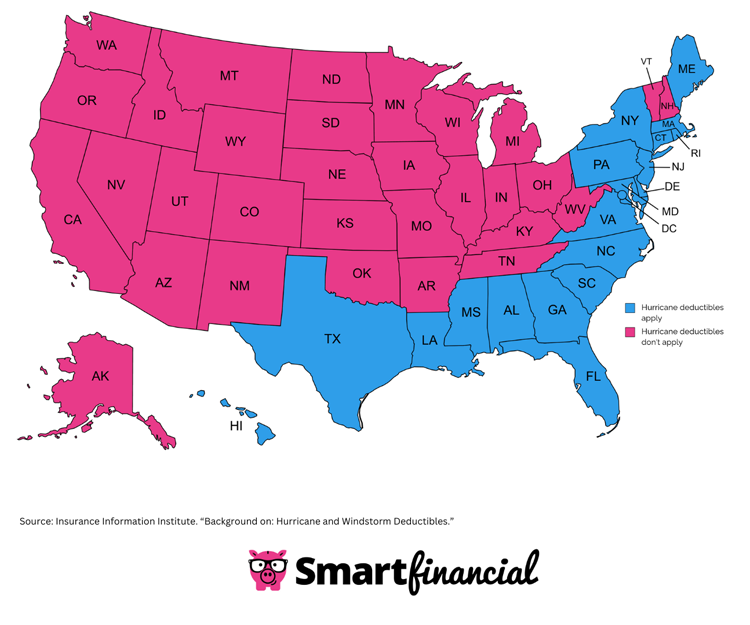
A hurricane deductible may apply to your policy if you live in any of the following regions:[6]
| Alabama | Mississippi |
| Connecticut | New Jersey |
| Delaware | New York |
| Florida | North Carolina |
| Georgia | Pennsylvania |
| Hawaii | Rhode Island |
| Louisiana | South Carolina |
| Maine | Texas |
| Maryland | Virginia |
| Massachusetts | Washington, D.C. |
Your hurricane deductible may be set at a flat dollar amount, like a standard home insurance deductible, or it may be set at a percentage of your dwelling coverage limit — usually between 1% and 5%.[6] For example, if you have $400,000 worth of coverage for the structure of your home, then you will likely have to pay between $4,000 and $20,000 out of pocket before your insurance takes effect after a covered hurricane.
Certain states may have their own unique rules for hurricane deductibles. For example, Florida homeowners only have to pay their hurricane deductible once per year — rather than once per claim. As a result, if you file two hurricane claims within a year, your second claim will require you to pay either your policy’s standard deductible or the amount of your hurricane deductible that is remaining from your first claim — whichever is higher.[11]
What Triggers Hurricane Deductibles?
Hurricane deductibles only apply to claims caused by storms with hurricane-force winds — weaker windstorms may instead trigger a smaller wind and hail deductible, depending on your location. Some states may require more specific triggers for hurricane deductibles, such as when the National Weather Service names a tropical storm, defines the intensity of a hurricane or issues an official hurricane watch or warning.[6]
Who Needs Hurricane Coverage?
In general, hurricane damage insurance is necessary for anyone who lives in a hurricane-prone region — especially in coastal areas that are particularly vulnerable to severe hurricane damage.[7] That said, hurricane coverage is not necessarily required by law. For example, home insurance is legally optional, though it may be required by your mortgage lender or homeowners association.[12]
On the other hand, flood insurance is required by law if you have a government-backed mortgage and live in a high-risk flood zone.[13] In addition, if you receive assistance from the Federal Emergency Management Agency (FEMA) after a natural disaster, you must purchase and maintain flood insurance to qualify for additional disaster aid in the future.[14]
Hurricane Insurance at a Glance
- Hurricane insurance is not a singular insurance policy, but instead a collection of coverages that work together to cover most types of hurricane damage.
- Homeowners insurance generally covers several different hurricane-related perils, including wind, falling objects, theft, fire, vandalism and damage from cars.
- Standard home insurance policies exclude coverage for flooding, so you will likely need separate flood insurance to cover hurricane-induced flood damage.
- In certain high-risk regions, home insurance companies may exclude coverage for wind and hail damage. For this reason, homeowners in these areas may need separate windstorm insurance.
- Even if you buy all three types of hurricane home insurance coverage, certain losses won’t be covered, such as gradual mold damage, flood damage to most structures other than your home and damage that can be linked back to a failure to maintain your property. Additionally, you will need comprehensive auto insurance to cover hurricane damage to your vehicles.
- On average, homeowners can expect to pay around $3,350 per year for both homeowners and flood insurance. Ultimately, how much you have to spend on hurricane coverage depends on factors like where you live, the condition and rebuilding cost of your home and whether you need additional windstorm insurance.
- Most states on the Atlantic and Gulf Coasts enforce hurricane deductibles, meaning you will likely have to spend more out of pocket whenever you need to file a hurricane-related claim. Hurricane deductibles are often set at a percentage of your dwelling coverage limit, ranging from 1% to 5%.
- Flood insurance is generally required by law for people in high-risk flood zones who have government-backed mortgages or have received federal disaster aid. Conversely, homeowners insurance is usually only required as a condition for receiving a mortgage loan or joining a homeowners association.
How To Get Hurricane Coverage for Your Home
Follow these steps to obtain sufficient homeowners hurricane insurance:
- Make sure your home insurance has high enough coverage limits to replace your home and your most important belongings in case of a destructive peril.
- Check whether your home insurance already includes coverage for windstorms or whether you need to look into standalone windstorm insurance options.
- Prepare in advance by shopping for flood coverage well before a hurricane occurs, since flood insurance policies may come with a 30-day waiting period before your coverage kicks in.[3]
- Compare quotes from multiple insurance companies to ensure you’re getting the best possible deal on insurance.
- Apply for coverage, and pay your first premium to activate your policy after you are approved.
While individually contacting multiple insurers to request quotes can be time-consuming, SmartFinancial helps make comparison shopping easy. Simply fill out a single online questionnaire, and then we’ll get to work on collecting quotes for policies that match your coverage needs and budget. Shop for homeowners insurance for free today — potentially in as little as a few minutes!
- Insurance quotes /
- Home /
- Hurricane Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Home Insurance Quote Online Now.
More on Home Insurance

Looking for Home Insurance?
Compare rates from dozens of companies in less than 3 minutes.