

Types of Renters Insurance
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Depending on your coverage needs, you may benefit from purchasing either a broad form or comprehensive form renters insurance policy — which differ in terms of how many perils they cover. A standard policy should include various types of renters insurance that can provide coverage for your belongings, support if you lose your home, protection from costly lawsuits and financial assistance if you’re liable for someone else’s medical or repair bills.
Keep reading to learn about different types of renters insurance policies and how much coverage you may need.
|
Key Takeaways
|


What Types of Renters Insurance Are Available?
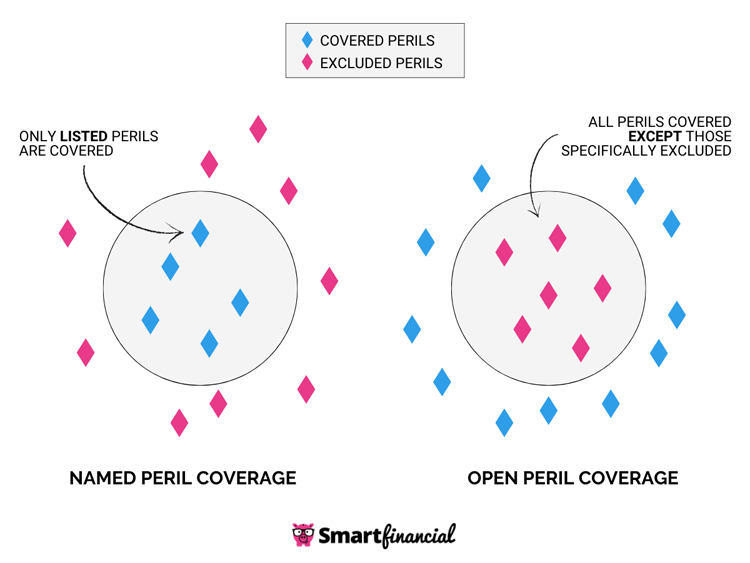
Renters insurance policies — also known as HO-4 policies — are generally split into two main categories: broad form and comprehensive form. Broad form policies provide named peril coverage, meaning they only insure your belongings against perils that are specifically mentioned in your policy documents. Conversely, comprehensive form policies offer open peril coverage that applies to all losses as long as they aren’t expressly excluded by the policy.[1]
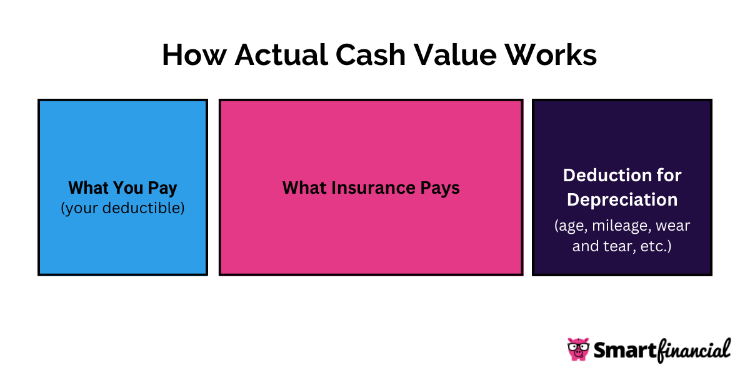
Policies may also differ on whether they provide replacement cost value or actual cash value coverage for your possessions. An RCV policy will reimburse you at the full cost of replacing any items that are destroyed by a covered peril, while an ACV policy will only pay out the current value of lost items based on depreciation factors, like age or wear and tear.[1]
What Does Renters Insurance Cover?
Renters insurance typically covers many of the same types of losses as homeowners insurance. In particular, your HO-4 renters insurance policy should include the following four types of insurance coverage: personal property, loss of use, personal liability and medical payments coverage.[2] Read the following sections for an overview of each of these coverage types.

Personal Property
Personal property insurance covers sudden and unexpected damage to your personal belongings, such as furniture, clothing and electronics. If you opt for broad form coverage, your policy will generally insure your possessions against the following 16 perils:[3]
|
Volcanic eruptions |
|
|
Explosion |
Falling objects |
|
Riot or civil commotion |
Weight of ice, sleet or snow |
|
Damage by aircraft |
Water or steam discharge from home systems and appliances |
|
Damage by vehicle |
Sudden and accidental tearing, cracking, burning or bulging of home systems |
|
Smoke |
Freezing of home systems |
|
Vandalism or malicious mischief |
Sudden and accidental power surges |
Most renters insurance policies come with off-premises coverage, meaning your possessions are covered even when they’re outside of your primary residence. For example, if someone steals your car while your phone and laptop are inside, you could file a claim on your renters insurance for the lost electronics. However, the limit for off-premises claims may be set at 10% of the overall personal property coverage limit.[2]
Loss of Use
Loss of use coverage — also known as additional living expense coverage — pays for temporary costs that arise if your house or apartment becomes uninhabitable due to a covered peril. For example, your insurance company may cover the costs of hotel stays, restaurant meals and laundromat services while you wait for your home to be repaired or rebuilt.
Your insurer may not pay for additional living expenses up front, so you may need to save receipts in order to be reimbursed after the fact. Keep in mind that loss of use insurance typically only covers the difference between your normal living expenses and the additional living expenses.[2] For example, suppose you usually spend $3,000 a month on rent and groceries but end up spending $4,000 at hotels and restaurants after your home is severely damaged.
Personal Liability
Personal liability coverage can shield you from major financial losses in case you are held responsible for someone else’s injury or damage to their property. For example, it can cover medical bills if a guest trips down your stairs and breaks their leg, or it can cover property repairs if your child accidentally throws a ball through your neighbor’s window.
In addition, your personal liability insurance can cover legal expenses if someone sues you over a bodily injury or property damage claim. Personal liability coverage may even apply to incidents that occur away from your home — like if you break another person’s fingers while on vacation by accidentally slamming a heavy hotel door on their hand.[4]
Medical Payments
Like personal liability insurance, medical payments coverage can take care of another person’s medical expenses. It is also known as no-fault medical coverage because it applies to any accident that occurs in your home, regardless of whether you are personally liable. Medical payments coverage differs from personal liability coverage in that it doesn’t cover legal fees, so it’s best used as a deterrent to prevent small claims from escalating into costly lawsuits.
What Isn’t Covered by Renters Insurance?
Renters insurance policies commonly come with certain exclusions — or losses that your insurance company won’t cover. Some of the things that are often excluded from HO-4 insurance coverage include the following:[5]
- Buildings and other structures: Unlike home insurance, renters insurance policies don’t include dwelling coverage for the structure of the home you rent or other structures coverage for sheds, fences and other freestanding structures on the property. These should instead be covered by your landlord’s insurance policy.
- Your roommate’s belongings: Depending on the circumstances, you may not be allowed to add your roommate to your renters insurance, so they may need to obtain their own policy to protect their possessions in the event of a peril that damages your shared home.
- Certain natural disasters: Although standard renters policies cover some natural disasters — such as wildfires and windstorms — they usually exclude coverage for floods, earthquakes and other types of ground movement, like sinkholes. For more complete protection for your belongings, you may need to buy extra flood insurance, earthquake insurance or difference in conditions insurance.
- Wear and tear: Insurance predominantly covers sudden and unexpected losses, so damage from predictable wear and tear over time isn’t covered. Other progressive losses may also be excluded, including gradual damage from water leaks or termite damage triggered by poor maintenance or neglect on your part.
- Intentional losses: Intentionally damaging your own property to try to collect a renters insurance payout is considered insurance fraud and could result in the cancellation of your policy, along with potential legal penalties.
- Vehicles: Any damage to your vehicle is covered by auto insurance rather than renters insurance. Nevertheless, your renters insurance will cover items that are stolen from your car or destroyed in a car accident.
- Certain valuables: While personal property insurance generally covers jewelry and other valuables, they are often subject to sublimits, meaning your payout after a covered loss may not be enough to fully replace the lost jewelry. To secure broader protection for your high-value collectibles, you may need to purchase a scheduled personal property coverage endorsement or a separate valuable articles insurance policy.
What Type of Renters Insurance Do I Need?
To choose which type of renters insurance would be best for your circumstances, you need to fully assess your coverage needs and weigh them against your budget. For example, if you have several expensive possessions that you would need to replace after a covered loss and you want to protect them against a wide array of losses, you may want to opt for a comprehensive form policy that offers replacement cost value coverage.
Fortunately, many insurers offer savings opportunities that may enable you to afford a policy that provides a greater level of coverage. For example, you could secure a bundling discount by purchasing both auto and renters insurance from the same carrier. Additionally, you could lower your premium by as much as 25% by selecting a higher deductible — assuming you have enough money saved up to cover that deductible in the event of a claim.[2]

How Much Renters Insurance Do I Need?
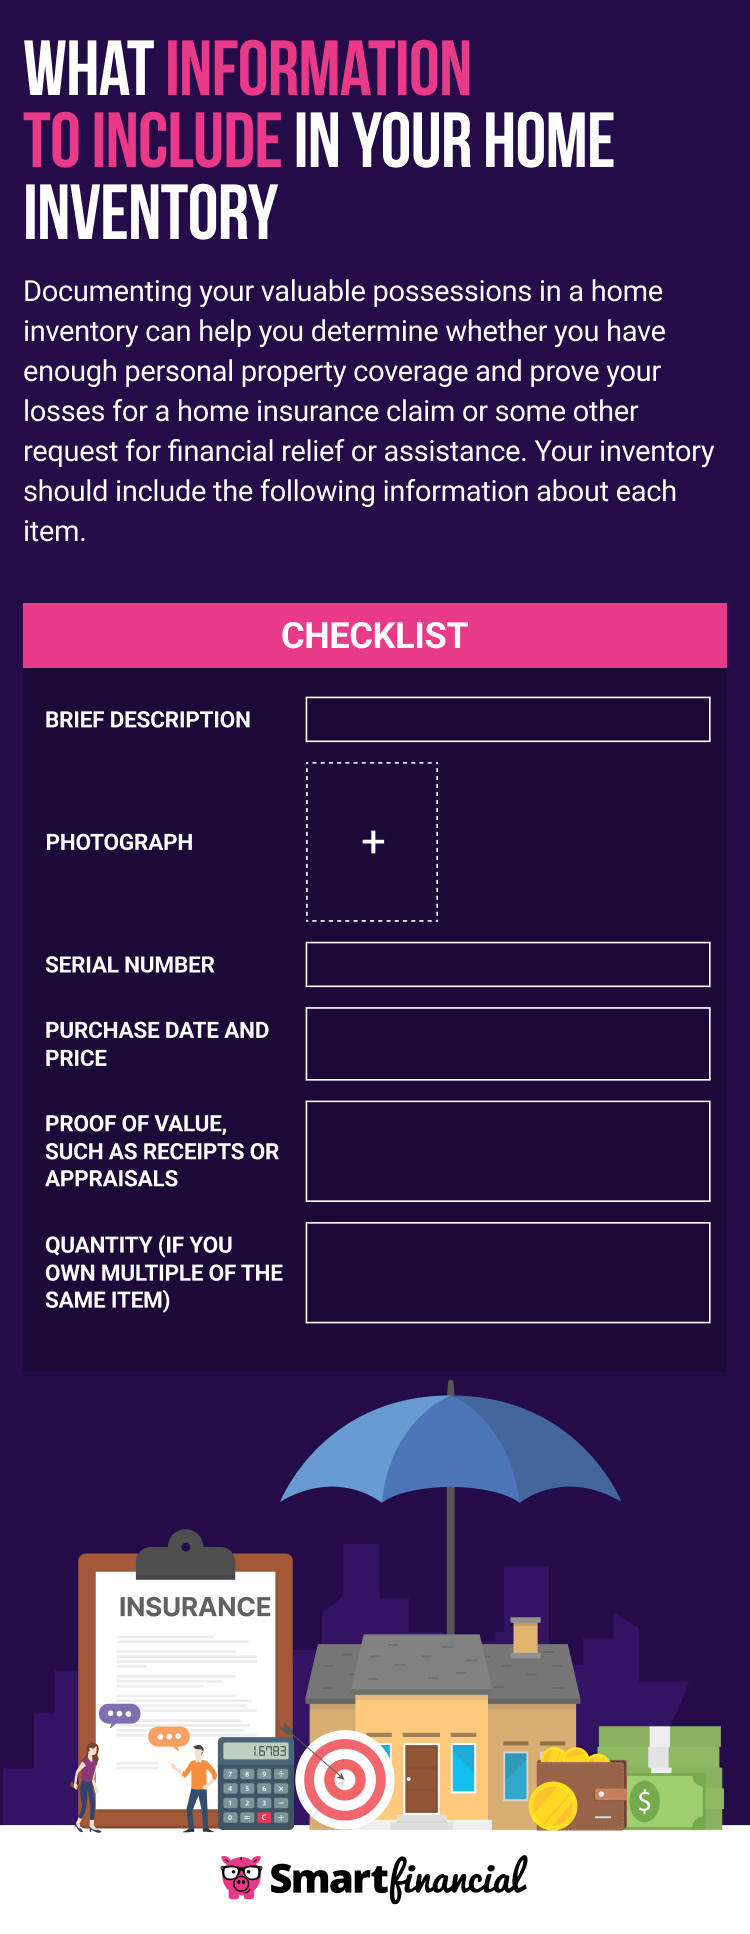
Determining the value of your possessions and your liability exposure can help you decide how high your renters insurance coverage limits need to be.[3] A home inventory is a great tool that can help you add up the value of all your items in order to settle on an appropriate personal property coverage limit. It can also help you prove your losses whenever you need to file a renters insurance claim.
Meanwhile, you may be more likely to encounter a property damage or bodily injury liability claim if you regularly invite guests to your home or have an attractive nuisance, such as a trampoline or swimming pool.[3] Most renters policies offer at least $100,000 worth of personal liability coverage and $1,000 worth of medical payments coverage, but you may want to raise those limits to $300,000 and $5,000, respectively, if you have a high liability risk.[2]
Even though renters insurance coverage is not required by law in any state, landlords often require their tenants to maintain coverage.[6] Furthermore, a renters insurance policy can provide crucial coverage for unavoidable perils and unpredictable liability claims, making it a wise investment even if your landlord does not require you to purchase one.
Where Can I Buy Renters Insurance?
Several national insurance carriers offer renters insurance policies, including Allstate, GEICO, Liberty Mutual, Nationwide, State Farm, Travelers and more. On average, renters insurance costs about $15 to $30 per month, depending on factors like the location of your rental unit and the value of your belongings.[1] If you need extra liability coverage, you may be able to purchase $1 million worth of umbrella insurance for around the same price.[2]
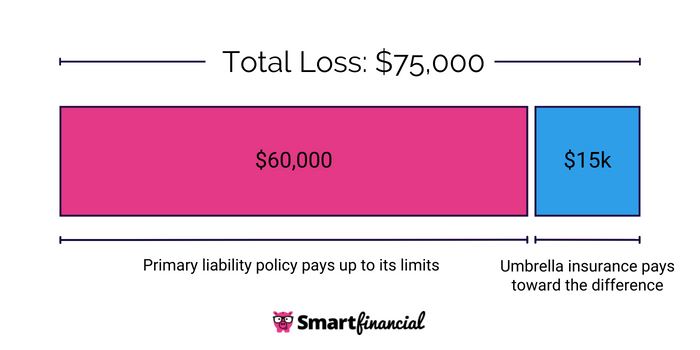
Each insurance company uses its own formula to calculate the risk of insuring any given individual, so one carrier may present you with a cheaper quote than another for the same coverage. By using an online marketplace, like SmartFinancial, you can find a renters insurance policy that suits your needs at the lowest price possible. Start comparing renters insurance quotes for free today!
- Insurance quotes /
- Renters /
- Renters Insurance Explained
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Renters Insurance Quote.
More on Renters Insurance
Looking for Renters Insurance?
Compare rates from dozens of companies in less than 3 minutes.