
What Is Personal Liability Insurance?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Personal liability insurance is a coverage type included in a standard homeowners insurance policy that can cover medical bills, property repairs, legal expenses and more if anyone in your household is held liable for injuring someone else or damaging their property. Insurers often offer up to $500,000 worth of personal liability coverage, but umbrella insurance can provide extra coverage if you have a high net worth or exposure to personal liability claims.
Read on to learn more about personal liability insurance for homeowners, including when it’s required and what types of losses it does and doesn’t cover.
|
Key Takeaways
|


How Does Personal Liability Insurance Work
Personal liability insurance is a type of home insurance coverage that steps in if you are held liable for someone’s injury or damage to their property. Claims on your personal liability coverage generally don’t require you to pay a deductible, meaning your insurance company will pay out 100% of the costs for covered claims — up to your coverage limit.[1]
Your personal liability coverage extends to every member of your household listed on your policy.[2] For example, it may apply if your child accidentally throws a football through and destroys your neighbor’s window. In addition, personal liability insurance can cover incidents that occur outside of your home or property, like if you accidentally break someone’s fingers by slamming a heavy door on their hand at a hotel while on vacation.[3]
Is Personal Liability Coverage Required?
You are not required by law to purchase a homeowners insurance policy that includes personal liability coverage in any state. That said, your lender will usually require you to maintain home insurance until you have paid off your mortgage. Additionally, homeowners coverage may be mandatory if you live in a neighborhood governed by a homeowners association (HOA).[4]
What Does Personal Liability Insurance Cover?
Personal liability insurance predominantly covers another person’s expenses if you are responsible for their injury or property damage. For example, it can pay the emergency room bills for a guest who breaks their arm after tripping over a loose board and falling down your deck stairs. Similarly, it can pay to repair or replace your neighbor’s roof if a tree that you failed to properly maintain falls on top of it.
Your insurance company may cover lost wages for someone who cannot work while recovering from an injury you caused and funeral expenses in the event that you are held liable for the death of a guest on your property. Also, personal liability insurance can cover your legal expenses — such as attorney fees, settlements and judgments — if someone sues you over a bodily injury or property damage claim.[3]

What Isn't Covered?
Personal liability insurance does not provide any coverage for intentional losses — like if you purposefully get into a fight with your neighbor or run over their mailbox because of a personal grudge. Meanwhile, your policy will also generally exclude coverage for losses that are covered by other types of insurance, such as the following:[5]
|
Personal Liability Insurance Exclusion |
What Type of Insurance Covers It |
|---|---|
|
Car accidents |
Bodily injury and property damage liability car insurance |
|
Damage to your property |
|
|
Injuries to your household members |
Health insurance |
|
Business-related claims |
Commercial insurance (e.g., general liability insurance) |
How Much Does Personal Liability Insurance Cost?
It costs an average of $2,408 per year to purchase a homeowners insurance policy that includes $500,000 worth of personal liability coverage.[6] Keep in mind that the amount you have to pay for homeowners insurance coverage will depend on various factors, such as your ZIP code, coverage limits, deductibles, claims history and overall liability exposure.
How Much Personal Liability Insurance Should I Get?
Home insurance policies generally come with at least $100,000 worth of personal liability coverage, although $300,000 to $500,000 is typically considered to be a more appropriate coverage level for most homeowners.[7] Another common recommendation is that you buy enough personal liability insurance to cover your entire net worth — that way, your home and all other assets you own will be fully protected in the event of a costly liability lawsuit.[8]
If your home insurance company doesn’t offer high enough personal liability coverage limits, you may want to invest in umbrella insurance, which can cover personal or auto liability claims that exceed the coverage limits of your basic liability insurance policies.[7] Insurers may offer you up to $10 million worth of personal umbrella insurance, with policies potentially costing just a few hundred dollars or less annually per $1 million in coverage.[8][9]
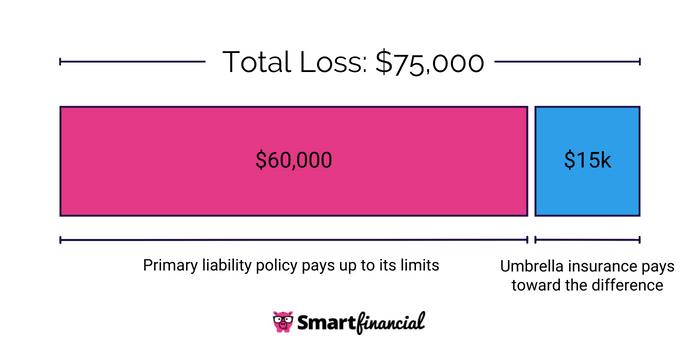
How To Get Personal Liability Insurance for My Home
The best way to find an affordable home insurance policy with a sufficient amount of personal liability insurance coverage is to compare quotes from multiple insurance companies — usually around three to five. Each insurance carrier will ask for information about your household, including where you live and how many people live in your home. However, it can be tedious to individually reach out to insurers to give them the same information over and over again.
That’s where SmartFinancial steps in. When you shop with us, you’ll only need to answer a single set of questions about your coverage needs and budget; then, we’ll get you in touch with agents who can help you compare personal liability insurance policies from the best insurance companies in your area. Start shopping for homeowners insurance for free by clicking here and entering your ZIP code!
- Insurance quotes /
- Home /
- Personal Liability Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Home Insurance Quote Online Now.
More on Home Insurance
Looking for Home Insurance?
Compare rates from dozens of companies in less than 3 minutes.