
Equipment Breakdown Insurance: Coverage for Small Businesses Explained
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Equipment breakdown coverage can help your business if crucial equipment fails due to sudden causes — such as power surges or mechanical breakdowns — reimbursing you for business interruption and the cost of replacing the equipment. Without this commercial insurance policy, your business may have to cover unexpected repair or replacement costs out of pocket, which could result in unnecessary financial stress.
Keep reading to learn more about the benefits of equipment breakdown coverage, what it protects against, exclusions, cost factors and whether your small business needs this protection.
|
Key Takeaways
|
On This Page

What Is Equipment Breakdown Insurance?
What Does Equipment Breakdown Coverage Cover?
What Equipment Breakdown Insurance Does Not Cover
Equipment Breakdown Coverage Examples
How Equipment Breakdown Coverage Differs From Commercial Property Insurance
Equipment Breakdown Insurance vs. Boiler and Machinery Coverage
How Much Does Equipment Breakdown Insurance Cost?
Who Needs Equipment Breakdown Coverage?
Is Equipment Breakdown Coverage Worth It for Small Businesses?
Equipment Breakdown Coverage at a Glance
How To Compare Equipment Breakdown Insurance for Your Business
FAQs

What Is Equipment Breakdown Insurance?
Equipment breakdown insurance coverage is a commercial policy that pays to repair or replace machinery or equipment that suddenly stops functioning, usually due to a mechanical defect, electrical breakdown or user error.[1] Standard commercial property insurance typically excludes this coverage, so equipment-dependent businesses that need it will likely need to obtain a separate equipment breakdown policy or endorsement, such as through a business owner's policy (BOP).
What Does Equipment Breakdown Coverage Cover?
Equipment breakdown coverage typically protects mechanical and electrical systems, computer equipment alongside HVAC and refrigeration equipment. It can also cover various manufacturing and production equipment. After a piece of business equipment experiences a sudden and unexpected breakdown, this coverage can help reimburse you for costs related to:[2]
- Replacing or repairing damaged equipment
- Lost income
- Spoiled inventory, such as food waste
- Necessary expenses during the restoration period, such as renting temporary equipment
Below, we’ll cover some of the different types of covered equipment in greater detail.
Mechanical and Electrical Equipment
Equipment breakdown coverage can protect your mechanical and electrical equipment, including motors, engines, generators, cables and electrical panels. For example, if the generator that powers your outdoor food truck dies, you could be reimbursed for lost income and replacement costs.
Heating, Ventilation and Air Conditioning Systems (HVAC)
Your various commercial heating, central air conditioning and climate control systems are typically covered by equipment breakdown insurance. For example, if theHVAC unit in your retail store fails, this coverage can pay for its repair or replacement.
Refrigeration and Food Service Equipment
Equipment breakdown coverage can protect your business’s refrigerators, walk-in coolers and ice machines if they experience a sudden failure. This coverage can also cover spoiled inventory, such as food, if a refrigeration unit fails, making it beneficial to restaurants, convenience stores and grocers.
Computers and Technology Systems
If your business’s server equipment, phone systems, point-of-sale machines or security systems experience a mechanical or electrical failure, equipment breakdown insurance can cover their repair or replacement. Additionally, power surges from external lines that cause internal damage by short-circuiting your computer and technology systems are typically covered.[3]
Production and Manufacturing Machinery
Equipment breakdown coverage can protect specialized production and manufacturing equipment, including CNC machines, printing presses and other pieces of specialized trade equipment. For example, if you run a t-shirt print shop and your printing equipment breaks down, this insurance coverage can help reimburse you for lost income and equipment repair.
What Equipment Breakdown Insurance Does Not Cover
An equipment breakdown insurance policy typically includes exclusions for claims unrelated to sudden and unexpected failures. Ensure you review your policy to know what you’re covered for. We’ll discuss some common exclusions below.
Normal Wear and Tear
Equipment breakdown coverage protects only against sudden and unexpected failures, so damage from normal wear and tear is typically excluded. Review the expected lifespan of your equipment to understand when a failure is likely to occur and how long coverage will typically extend for any covered piece of equipment.
Intentional Damage or Neglect
Damage you intentionally cause to equipment, such as an employee hitting a point-of-sale system in anger, is typically excluded from coverage. Similarly, breakdowns due to failure to maintain equipment, such as refusing to clean mold from a refrigeration unit, which then requires replacement, are typically excluded from coverage.
Losses Covered by Other Policies
Some losses due to external perils, such as fire, theft, vandalism and some natural disasters, are typically covered under a commercial property insurance policy and are therefore excluded in equipment breakdown coverage. Review the different types of commercial policies available to you, understand what each covers and determine which policies your business needs.
Equipment Breakdown Coverage Examples
Below are some real-world scenarios your business could face and how equipment breakdown coverage can help cover losses.
Restaurant Refrigeration Failure
Suppose your restaurant’s walk-in freezer fails overnight, leaving behind tons of spoiled food and preventing you from running your business until the unit is repaired. Making an equipment breakdown coverage claim can help reimburse you for lost income, the repair or replacement of the freezer’s failed compressor unit and the cost of restocking your spoiled inventory.
Office HVAC System Breakdown
In the event your office building’s air conditioning unit fails during high summer heat, it could make working inside unsafe and halt business operations. An equipment breakdown insurance claim can help pay for an emergency HVAC repair and may cover the cost of temporary cooling equipment to keep business running during the restoration process.
Manufacturing Motor Burnout
If you own a manufacturing business and the motor in an important piece of equipment fails due to electrical arcing, your operations may shut down until the equipment can be repaired. Equipment breakdown coverage can reimburse costs for repairs to the piece and lost business income.
Electrical Surge Damages Business Computers
Suppose a power surge fries all of the point-of-sale devices and server equipment in your retail store, resulting in a temporary closure due to the inability to make transactions. Equipment breakdown coverage can help reimburse your business for the cost of replacing this equipment and for the income you would have earned while it is being replaced.
How Equipment Breakdown Coverage Differs From Commercial Property Insurance
Equipment breakdown coverage protects your business from internal mechanical and electrical failures, while commercial property insurance covers damage caused by external perils like fire, theft and windstorms.[2] While both forms of coverage are critical for protecting your business from financial losses after unexpected damage to your equipment, it's essential to know what each covers when making a claim to avoid delays or denials of reimbursement.
|
Coverage Aspect |
Commercial Property Insurance |
Equipment Breakdown Insurance |
|
Fire damage to equipment |
Covered |
Not covered |
|
Theft of equipment |
Covered |
Not covered |
|
Motor burnout from electrical failure |
Not covered |
Covered |
|
Compressor failure |
Not covered |
Covered |
|
Power surge damage |
May be covered (depending on the cause of damage)[4] |
Covered |
|
Boiler explosion from pressure buildup |
Not covered |
Covered |
Equipment Breakdown Insurance vs. Boiler and Machinery Coverage
Equipment breakdown insurance and boiler and machinery coverage refer to the same type of policy. While “boiler and machinery coverage” served as the original term for this type of insurance for nearly 100 years, as coverage has expanded to include more technologies and types of equipment, “equipment breakdown coverage” has become the new standard term.[5]
How Much Does Equipment Breakdown Insurance Cost?
The cost of equipment breakdown insurance can vary based on several factors, such as the type of business you operate and the equipment you use. Additionally, whether you purchase equipment breakdown coverage as a standalone policy or as an endorsement to an existing commercial policy may affect your costs. Below, we’ll cover several factors that may affect your premiums.
Business Size and Annual Revenue
Larger businesses with higher annual revenue may end up with higher monthly payments, as they’ll need to account for greater reimbursement in the event of equipment halting business. Larger businesses may also use more equipment units across multiple business properties, which could increase the risk of a claim and lead to higher premiums.
Types and Value of Covered Equipment
Equipment that is more valuable and more expensive to repair or replace could result in higher premiums, as claims would be for larger reimbursement amounts in the event of a breakdown. Equipment that requires specialists for repair due to its age or a lack of available replacements will likely result in higher monthly costs.
Industry and Risk Classification
Certain industries with a higher risk of making a claim, such as restaurants, hospitals and food service, may end up paying more for equipment breakdown coverage than a low-risk industry, such as a business in an office building. Check with an insurance agent to understand the risks your business’s industry might face and how you could be classified by insurers.
Coverage Limits and Deductible Amounts
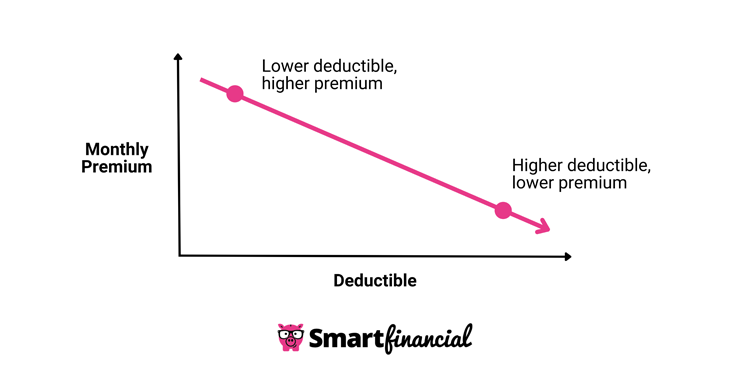
Generally, higher coverage limits result in higher insurance premiums, as they mean your insurer might have to pay larger reimbursement amounts after a claim. Similarly, a low deductible amount often leads to higher premiums. You can potentially lower your premiums by raising your deductible, but be wary of increasing the amount beyond what you’re capable of paying out of pocket when making a claim.
Who Needs Equipment Breakdown Coverage?
Businesses that rely heavily on equipment should consider equipment breakdown coverage to protect against financial losses from mechanical or electrical failures. This coverage is ideal for the following industries.
Restaurants and Food Service Businesses
Restaurants and food service businesses often use refrigeration and cooking equipment, and a breakdown could result in a temporary closure. Not only can equipment breakdown coverage help pay for equipment repair or replacement, along with lost income, but it can also reimburse the cost of spoiled inventory due to equipment failure.
Medical and Dental Practices
Medical and dental practices use expensive equipment that can be a financial burden to repair or replace if it fails, with many businesses relying on these machines to perform critical functions like diagnostics and sterilization. Equipment breakdown coverage can alleviate these high costs by covering repairs and replacements.
Manufacturing and Production Facilities
Manufacturing and production facilities use machines and specialized equipment to produce products, and any interruption caused by a faulty machine could dramatically impact revenue and worsen customer relationships. Ensuring your business has equipment breakdown coverage means you can purchase temporary equipment to continue operations while repairs are underway.
Contractor and Skilled Trade Businesses
Contractors and other skilled trade businesses often use specialized equipment for their industries, including welding tools and HVAC diagnostic equipment. Mechanical and electrical malfunctions in these tools could halt your business, so ensuring reimbursement for lost income makes equipment breakdown insurance a beneficial policy for these industries.
Retail Stores With Refrigeration or Climate Control
Retail stores, such as grocers, florists and pharmacies, often use refrigeration and climate-control equipment to store their inventory, and a breakdown could lead to significant product spoilage. Not only can equipment breakdown coverage reimburse for lost income and equipment repair, but it can also cover the cost of lost inventory due to the breakdown.
Is Equipment Breakdown Coverage Worth It for Small Businesses?
Equipment breakdown coverage may be worth it for small businesses that rely heavily on their equipment to operate and generate revenue. Businesses should evaluate the potential financial burden from lost income, spoiled inventory and equipment repair or replacement to determine whether this coverage is worth the monthly cost.
Consider some of the following factors in your business’s equipment to help you decide if equipment breakdown coverage is right for your small business:
- High equipment dependency: If your business relies on specific equipment to function, this coverage may be beneficial in the event of a breakdown.
- Aging equipment: Older equipment is more prone to mechanical failure, making this coverage more likely to be needed.
- Limited cash reserves: Sudden breakdowns may be more than your business’s finances can handle, but equipment breakdown coverage can help alleviate the cost of an internal mechanical or electrical failure.
- Perishable inventory: Businesses whose products could spoil due to equipment breakdowns can benefit from this coverage.
Equipment Breakdown Coverage at a Glance
Below, we’ll review the essential information you need to know about equipment breakdown coverage:
- Equipment breakdown coverage covers equipment failures caused by internal mechanical or electrical issues.
- Equipment breakdown insurance can cover lost income, equipment repair and replacement, additional expenses during restoration and spoiled inventory.
- Equipment breakdown coverage is separate from commercial property insurance, which protects against external perils, and can typically be purchased as a standalone policy or as an endorsement to an existing commercial policy, like a business owners policy (BOP).
- Businesses that rely heavily on equipment to function, such as retail stores, medical practices and contract workers, may benefit most from this coverage.
- The size of your business, its industry and the type of equipment you need covered can all affect your insurance premiums.
How To Compare Equipment Breakdown Insurance for Your Business
Below are a few tips on how to best compare equipment breakdown insurance for your business:
- Inventory your equipment: List all mechanical, electrical and pressure equipment, along with estimated replacement values, to determine how much coverage you’ll need in the event of a breakdown.
- Compare multiple quotes: Request quotes from several carriers to find competitive pricing — ideally three to five.
- Review policy exclusions: Understand what is not covered before purchasing coverage.
- Consider bundling: Adding equipment breakdown to a Business Owners Policy, instead of purchasing standalone coverage, may offer savings.
Gathering quotes can be tedious, as you’ll typically need to obtain them from each insurance carrier individually. Consider using an insurance marketplace like SmartFinancial to speed up the process. After connecting with one of our licensed insurance agents, we can help you get the commercial coverage you need. Click here for free commercial insurance quotes today!
- Insurance quotes /
- Commercial /
- Equipment Breakdown Coverage
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Commercial Insurance Quote.
More on Commercial Insurance
Looking for Commercial Insurance?
Compare rates from dozens of companies in less than 3 minutes.