

Small Business Insurance: Costs, Coverage and Requirements Explained
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
You may be able to secure small business insurance coverage to protect against liability lawsuits, property damage, professional mistakes, data breaches and other perils for as little as a few thousand dollars per year, depending on your policy details and risk exposure. Business insurance is often required if you have employees or use commercial vehicles, but insurance provides significant value for small businesses even when it isn’t mandatory.
Keep reading for a comprehensive overview of business insurance for small businesses, including what coverage types your enterprise may need and how you can find an affordable policy.
|
Key Takeaways
|
On This Page

What Is Small Business Insurance?
How Does Small Business Insurance Work?
What Does Small Business Insurance Cover?
What Isn’t Covered by Small Business Insurance?
Types of Small Business Insurance
What Types of Small Business Insurance Are Required by Law?
Who Needs Small Business Insurance?
How Much Does Small Business Insurance Cost?
How To Determine What Insurance My Small Business Needs
Small Business Insurance at a Glance
How To Get Small Business Insurance
FAQs

What Is Small Business Insurance?
Small business insurance is not a singular insurance product, but rather a collection of business insurance coverage types that can cover the various risks associated with running a small business, such as natural disasters, lawsuits and accidents involving guests or employees. Without sufficient insurance coverage, significant out-of-pocket expenses could put you at risk of going out of business in the event of an unexpected loss.
How Does Small Business Insurance Work?
As long as you regularly pay your premiums to your insurance company to keep your coverage active, small business insurance allows you to file a claim for reimbursement anytime you experience a loss covered by your policy. Many small and midsize businesses choose to secure coverage through an affordable insurance package known as a business owners policy.
That said, BOPs are designed to cover standard, small-scale risks, so not all businesses are eligible for coverage. For example, an insurance company may decline to offer BOP coverage to specific high-risk businesses — such as restaurants — or any company with more than 100 employees or $5 million in annual revenue.[1] Larger businesses or those that face unique risks may instead need a more highly customizable commercial package policy.[2]
|
|
Business Owners Policy (BOP) |
Commercial Package Policy (CPP) |
|---|---|---|
| Best For | Small businesses with standard risk profiles, fewer than 100 employees and less than $5 million in yearly revenue | Large or growing businesses and businesses facing specialized or complex risks |
| Benefits | Bundles basic coverages together into one convenient package at an affordable price | Enables businesses to more precisely customize their coverage while still reaping the benefits of an insurance bundle |
| Relative Cost | Cheaper than a CPP | More expensive than a BOP, though still cheaper than buying each coverage type separately |
What Does Small Business Insurance Cover?
What your small business insurance covers depends on the coverage types included in the policy. In general, you will want to maintain various types of liability coverage to shield you from lawsuits and other financial losses in case a client or customer, an employee or another business claims to have experienced some kind of harm because of your commercial operations.
In addition, you need various property coverages that can insure your buildings, items and vehicles against external sources of damage or loss. You may also want to buy industry-specific coverage types that address the unique risks facing your business. Examples of these types of coverage include crop insurance for agribusinesses and liquor liability insurance for bar and restaurant owners.
What Isn’t Covered by Small Business Insurance?
Business insurance exclusions may vary based on your policy’s coverage types and your insurance company. Most basic policies exclude coverage for the following:[3]
- Intentional losses: Deliberately damaging your own property or inflicting harm on someone else to collect an insurance payout is considered insurance fraud and is not covered by commercial insurance.
- Gradual or predictable damage: The primary purpose of insurance is to cover sudden and unexpected losses, so damage caused by poor maintenance or normal wear and tear is typically excluded from coverage.
- Floods and earthquakes: Basic commercial property policies generally don’t cover flood or earthquake damage. Fortunately, you can secure coverage for these perils by purchasing separate commercial flood or earthquake insurance.
- Criminal actions: Most types of business insurance don’t cover criminal acts committed by your employees, such as fraud or theft. However, these may be covered if you separately buy commercial crime insurance or a fidelity bond.
- Pandemics and government shutdowns: Due to their unpredictability, pandemics and government-ordered shutdowns are often considered uninsurable losses, meaning they aren’t covered by typical commercial liability or business interruption policies.
Types of Small Business Insurance
Read below for an overview of some of the most common types of small business insurance you may need to consider for your company.

General Liability
General liability insurance is one of the most fundamental commercial coverage types, as it can step in if your business is accused of causing physical, financial or reputational harm to someone else. It generally includes coverage for the following expenses:
- Medical treatments: Your general liability insurance can cover hospital bills, rehabilitation costs and related medical expenses for a guest who is injured on your business premises or because of your business operations.
- Property repairs: General liability coverage also takes care of property repairs if your business is held liable for damaging someone else’s property — like if one of your employees accidentally drops and breaks a customer’s phone while trying to scan their mobile payment app.
- Legal fees: If a bodily injury or property damage claim leads to a lawsuit, your general liability policy can cover attorney fees, judgments, settlements and other legal costs. This coverage also applies to personal and advertising injury claims, including lawsuits related to allegations of defamation or copyright infringement.
Commercial Property
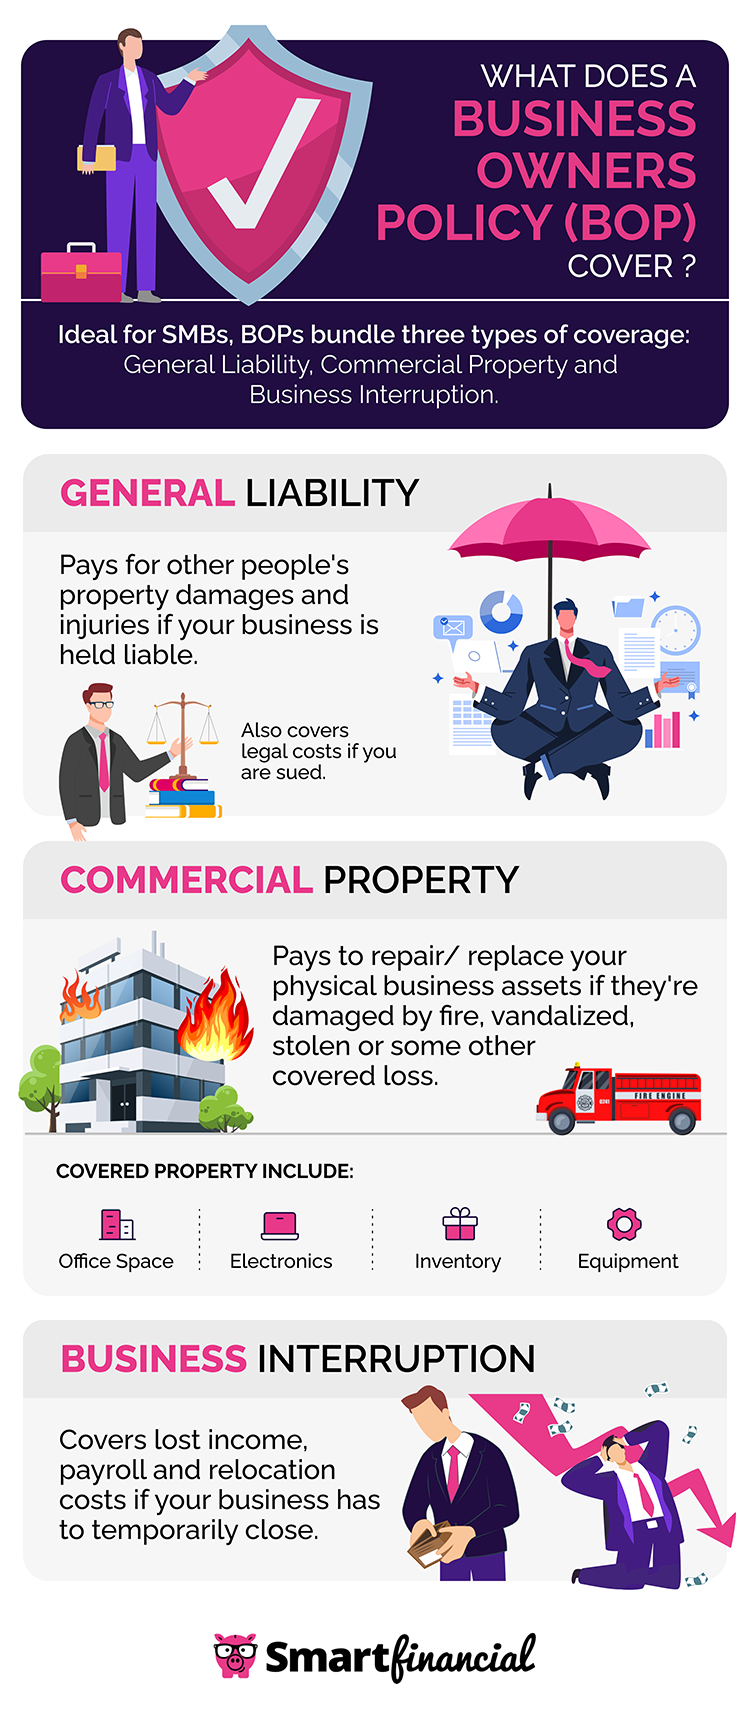
Commercial property insurance can help pay to repair or replace your commercial property if it is damaged or lost due to a sudden peril, such as a fire, a windstorm, vandalism or burglary. It insures both the physical structure of any buildings you operate out of and any items stored inside those buildings, such as equipment, electronics, inventory, documents and furniture.
Depending on your size, you may want to opt for a business owners policy to bundle general liability, commercial property and business interruption insurance together at an affordable price. Business interruption insurance takes care of expenses that may arise if a covered peril prevents your business from operating as usual, such as payroll, lost income, rent or mortgage payments and temporary relocation costs.
Professional Liability
Professional liability insurance can cover your legal expenses if you are sued for failing to correctly carry out your professional responsibilities and negatively impacting a client as a result. This coverage type is also called errors and omissions insurance because it covers claims related to professional mistakes, like negligence, misrepresentation and breach of contract.
Workers’ Compensation
Workers’ compensation insurance provides assistance for employees who become sick or injured on the job. For example, it can pay for their health care and rehabilitation, make up for any income they lose while they are out of work and offer long-term disability benefits, if necessary. In addition, workers’ compensation coverage can issue a death benefit payout to the beneficiaries of an employee who dies due to a work-related injury or illness.
Commercial Auto
Commercial auto insurance steps in if one of your drivers is involved in a commercial vehicle accident or experiences some other kind of vehicle-related loss. Here are some of the most important commercial auto coverage types your policy should include:
- Auto liability: Bodily injury liability insurance can cover someone else’s medical bills, lost wages or final expenses if your business is responsible for injuring, disabling or killing them in an accident. Meanwhile, property damage liability insurance can pay to repair or replace someone else’s vehicle or other property that you damage in a crash.
- Physical damage: Physical damage coverage insures your business-owned vehicles against external sources of damage. It includes collision insurance to cover damage from car accidents and comprehensive insurance to cover damage from other perils, such as natural disasters and vandalism.
- MedPay/PIP: Medical payments coverage and personal injury protection can both cover medical treatments for you or your employees if you are injured in a commercial vehicle accident. PIP provides broader coverage overall, though, as it can also cover lost wages while you are recovering.
- Uninsured and underinsured motorist: Uninsured motorist coverage takes care of your medical or repair costs if you are struck by someone without auto insurance while driving for business purposes, while underinsured motorist insurance covers the same expenses if you are struck by an insured driver whose coverage limits are too low to cover the entirety of your medical or repair expenses.
Cyber Liability
Cyber insurance can cover your company’s direct losses or legal expenses stemming from liability claims if your business is the victim of a cybercrime, such as a data breach. If you digitally store any of your clients’ personal information — like their credit card numbers or contact information — cyber liability insurance is crucial to help you deal with the fallout in the event that their information is illegally accessed or leaked.
Additional Types of Small Business Insurance
There are many other optional coverage types that may be worth considering for your commercial small business insurance policy, including the following:
- Product liability: Product liability insurance can cover your legal expenses if one of your customers claims they have been negatively impacted due to an error in the design, manufacturing or marketing of a product you sell or use at your business. Some insurance companies automatically include this coverage with your general liability insurance policy.[4]
- Inland marine: If your business ever transports products, tools or equipment from one location to another, you will likely need inland marine insurance to cover your business property while in transit. Motor carriers who haul freight need a specialized type of inland marine coverage known as motor truck cargo insurance.
- Equipment breakdown: Although commercial property coverage insures your business equipment against most types of external perils, you will need equipment breakdown insurance to cover equipment repairs or replacements necessitated by internal failures, like short circuits and mechanical breakdowns.
- D&O: Directors and officers liability insurance covers business executives in case they are sued for mismanaging their company, breaching their fiduciary duty, misusing company funds or otherwise neglecting to lead their business lawfully and effectively.
- Commercial crime: Commercial crime insurance can help mitigate financial losses stemming from employee dishonesty or related crimes, like forgery or embezzlement.
- EPLI: Employment practices liability insurance protects business owners and managers in case they are accused of violating an employee’s rights. It includes coverage for claims related to wrongful termination, discrimination, sexual harassment and retaliation.
- EBL: Employee benefits liability insurance can cover your legal fees if an employee sues you over an error in the administration of their benefits package. For example, your EBL insurance could kick in if your human resources manager gives an employee inaccurate information about their retirement benefits or forgets to enroll them in a work-based health insurance plan.
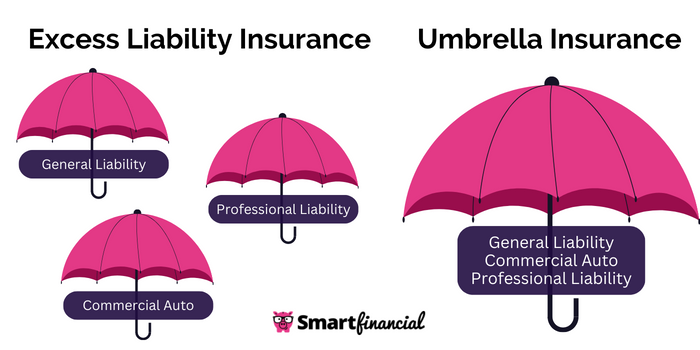
- Commercial umbrella: Commercial umbrella insurance is a type of excess liability coverage, meaning it can step in to provide extra coverage if a costly liability claim exceeds an underlying policy’s coverage limit. As its name suggests, commercial umbrella insurance can sit over and provide excess coverage for multiple liability insurance policies at the same time.
What Types of Small Business Insurance Are Required by Law?
Certain types of commercial insurance may be required by law for your small business, depending on your state and industry. See the following table for an overview of the most common small business insurance requirements:[5][6][7][8]
|
Coverage Type |
Who It’s Required For |
Requirement Type |
|---|---|---|
| Commercial auto insurance | Businesses that use vehicles to conduct business activities | State-level requirement that applies in most states |
| Workers’ compensation insurance | Businesses with employees — barring certain industry-specific exemptions | State-level requirement that applies in most states |
| Cargo insurance | Freight forwarders and for-hire carriers of household goods | Federal requirement that applies across the United States |
| Professional liability insurance | Certain professions, such as attorneys and doctors | State-level requirement that applies in some states |
Who Needs Small Business Insurance?
Generally speaking, all small businesses need commercial insurance to protect themselves against devastating losses stemming from common risks — and potentially to comply with certain legal requirements. Additionally, small business insurance is often necessary in the following situations:[9]
- Contractual requirements: You may not be able to secure a contract with a prospective client unless you can present a certificate of insurance proving that your client would be covered if you caused them to experience some kind of financial loss. This is especially common for professional services firms and contractors bidding for work with governmental agencies.
- Rental agreements: Commercial landlords may request proof of coverage before renting their property to you to confirm that they won’t be on the hook if you damage their property and that you can remain financially stable and continue making rent payments — even if you face a costly liability claim.
- Professional licensing: In industries that require professional licenses — such as real estate — commercial insurance may be necessary to comply with the requirements of your state’s occupational licensing board.
How Much Does Small Business Insurance Cost?
You can generally expect to pay at least $3,000 per year for a business owners policy and mandatory commercial auto and workers’ compensation coverages. However, your premiums may vary greatly, depending on the coverage types you elect to include in your policy. Take a look at the following table for a breakdown of average costs for some of the most common types of small business coverage:[10]
| Coverage Type | Average Annual Cost Range |
| Business owners policy | $500 to $3,000 |
| Standalone general liability insurance |
$500 to $1,200 |
| Standalone commercial property insurance | $800 to $5,000 |
| Commercial auto insurance | $1,500 to $7,000 |
| Workers’ compensation insurance | $1,000 to $2,500 |
| Professional liability insurance | $4,000 to $15,000 |
| Cyber insurance | $1,500 to $4,800 |
| Commercial crime insurance | $1,500 to $35,000 |
| D&O liability insurance | $9,000 to $30,000 |
Along with the coverages included in your policy, the following factors will influence how much you have to pay for small business insurance coverage:[10]
- Claims history: Businesses that have filed several insurance claims are generally viewed as riskier to insure, since they may be more likely to file additional claims going forward. For this reason, coverage is more expensive for companies with extensive claims records.
- Industry: Different industries have different risk exposures, so certain coverage types may be more expensive for you than for businesses in other industries. For example, a retail store with a large amount of foot traffic will likely pay much more for general liability insurance than a technology startup, but it may also pay much less for professional liability insurance.
- Size: The size of your business affects your risk exposure, so companies with higher annual revenue and more employees often pay more for liability and workers’ compensation insurance.
- Location: Where you operate can also impact your insurance costs. For example, you will likely pay more for commercial auto insurance if you operate in an area with a high rate of car accidents, while you may pay more for commercial property insurance if your region has high natural disaster or crime rates.
- Discount eligibility: You may be able to save money on business insurance by taking steps like bundling your policies together, paying your entire premium for the year up front or implementing comprehensive risk management strategies.
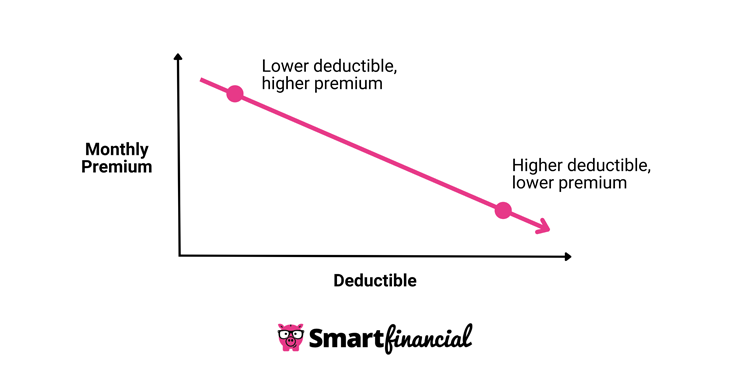
- Policy details: Usually, your policy will be cheaper if it comes with lower coverage limits and higher deductibles. That said, make sure you don’t sacrifice the level of coverage you need just to secure lower premiums.
How To Determine What Insurance My Small Business Needs
Taking the following steps can help you determine which types of commercial insurance you need for your small business:[11]
- Establish mandatory coverages: Most businesses need workers’ compensation and commercial auto insurance, but you should also check whether there are any other federal or state insurance requirements that apply to small businesses in your industry. Similarly, check whether you need to maintain certain coverage types or limits to comply with a client contract or rental agreement.
- Assess your coverage needs: If you merely carry the minimum amount of coverage required by law, you will likely be underinsured. For more comprehensive protection, you need to take a look at the risks your business is most likely to face and the value of the assets you could stand to lose, and make sure your insurance policy considers both of these to provide adequate coverage.
- Set a budget: Though commercial insurance is a necessary way to protect your finances, you may be overinsured if the premiums or out-of-pocket deductibles create such a significant strain on your finances that you can’t operate your business effectively. Comparing your budget to your level of risk tolerance can help you best determine where and how insurance fits into your broader risk management strategy.
- Begin shopping around: Once you’ve determined what types of insurance you need and how much you can afford to pay, you can begin collecting quotes from multiple commercial insurance providers. When comparing quotes, pay attention to details like their premiums, limits, deductibles, exclusions and discounts, along with information about the insurers, such as their customer service and claims handling reputations.
Small Business Insurance at a Glance
- Small business insurance refers to a collection of commercial insurance products that address the most common risks a given small business owner is likely to face during their day-to-day operations.
- Many small and midsize businesses opt to purchase business owners policies, which bundle basic general liability, commercial property and business interruption coverages together at a discounted rate.
- Depending on where you operate and what your business does, you may be required by law to carry coverage types like commercial auto, workers’ compensation, professional liability or cargo insurance.
- Other optional coverages you may need to consider for your business include cyber liability, commercial umbrella, commercial crime and directors and officers liability insurance, depending on the nature of your commercial operations.
- You may need various types of commercial insurance to satisfy the conditions of a client contract or rental agreement or to qualify for a professional license.
- Basic BOP coverage may be available for as little as $500 per year, but your business insurance premiums will ultimately depend on your policy details, claims history, industry, size, location and eligibility for discounts.
- To determine which types of small business insurance make the most sense for your budget, you need to determine what coverages are legally mandatory, identify the most pressing risks your business could encounter, establish an insurance budget and compare quotes from multiple insurance companies.
How To Get Small Business Insurance
It’s important to compare quotes from about three to five different insurance carriers so you can find the best possible deal on the coverage you need for your small business. However, the process of collecting quotes can be tedious, especially if you separately reach out to each carrier to provide the information needed to generate quotes, such as your company’s location, industry, annual revenue and employee headcount.
Thanks to SmartFinancial, insurance comparison shopping can be much easier. When you fill out our online questionnaire about your coverage needs, we’ll get you in touch with an agent who can help you rapidly find the best insurance policy for your situation. Click here to enter your ZIP code and get started on comparing commercial insurance quotes for free today!
- Insurance quotes /
- Commercial /
- Small Business Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Commercial Insurance Quote.
More on Commercial Insurance

Looking for Commercial Insurance?
Compare rates from dozens of companies in less than 3 minutes.