

Professional Liability Insurance: Coverage, Costs and Requirements Explained
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Professional liability insurance, also known as errors and omissions (E&O) insurance, can help protect you if you’re taken to court for professional negligence or breach of contract. In some states, this type of insurance is mandatory for small businesses in certain industries, and it may be beneficial for any business that provides specialized services or expertise rather than products.
Keep reading to learn everything you need to know about professional liability insurance for businesses, including what it covers and how much your business may have to pay for coverage.
|
Key Takeaways
|
On This Page

What Is Professional Liability Insurance?
What Does Professional Liability Insurance Cover?
What Isn't Covered by Professional Liability Insurance?
How Does Professional Liability Insurance Work?
Is Professional Liability Insurance Required?
Who Needs Professional Liability Insurance?
Professional Liability Examples
Professional Liability Insurance vs. General Liability Insurance
How Much Does Professional Liability Insurance Cost?
Professional Liability Insurance at a Glance
How To Get Professional Liability Insurance
FAQs

What Is Professional Liability Insurance?
Professional liability insurance is a type of commercial insurance that provides coverage if you are sued for failing to adequately carry out your professional responsibilities and causing your client to experience financial difficulty or another type of loss as a result.[1]
Keep in mind that lawyer fees often range from as little as $3,000 to as much as $150,000, and you could have to pay this entire amount out of pocket if you don’t have professional liability coverage.[1]
|
Professional Liability Insurance |
|
|---|---|
|
What Does it Cover? |
Financial losses from lawsuits over professional errors, omissions or negligence |
|
What Isn’t Covered? |
Fraudulent or intentional losses, physical injuries or property damage and claims involving discrimination, abuse or sexual misconduct |
|
Cost |
Often less than $100 per month for small businesses, depending on your insurer and other factors |
What Does Professional Liability Insurance Cover?
Professional liability insurance covers legal defense costs when a business is sued for errors or omissions, or for failing to deliver services as agreed.
Professional liability insurance may also cover lawsuits arising from allegations of defamation or copyright infringement.[2] However, many insurance carriers instead cover these claims through general liability insurance, so you may need to double-check the details of your policy to confirm how these personal and advertising injury claims are covered.
Below are some of the main types of business insurance claims typically covered by a professional liability insurance policy.
Negligence
Professional liability insurance would cover you if your business were sued due to negligence in providing service, such as when you overlook an issue that leads to damages or injuries.
Misrepresentation
Professional liability coverage would protect you from a misrepresentation lawsuit if your business doesn’t accurately describe itself or its capabilities to clients.
Breach of Contract
Professional liability insurance would cover you if you were sued for breaking the terms of your contract with a client.
Errors and Omissions
Professional liability coverage would pay for legal costs if you make a professional mistake, even if it is unintentional.
Inaccurate Advice
Professional liability insurance would protect you from expenses if you are sued for offering incorrect advice to a client or customer, such as during consulting.
What Isn't Covered by Professional Liability Insurance?
Your professional liability insurance won’t cover fraudulent or intentional losses. In addition, it won’t cover lawsuits related to physical injury or damage to someone else’s property that occurs on the premises of your business because these are typically covered by general liability insurance. Finally, your professional liability insurance provider will generally exclude coverage for employment practices liability claims, as well as any claim involving discrimination, abuse or sexual misconduct.[3]
How Does Professional Liability Insurance Work?
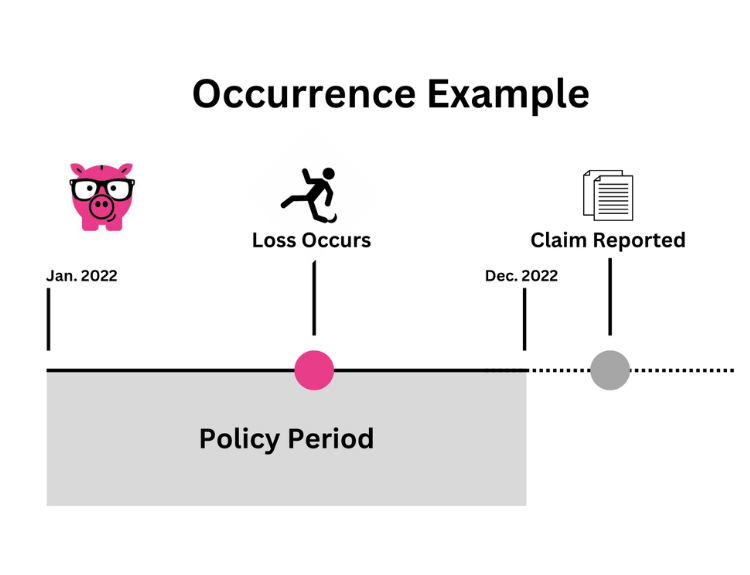
Professional liability insurance works by covering legal costs after a business is sued for failing to meet its professional obligations. Whether your insurer will cover a specific professional liability insurance coverage claim may depend on whether you have a claims-made or occurrence policy. Claims-made policies only cover claims that you file while your policy is active. Meanwhile, occurrence policies cover any losses that occur while your policy is active, even if you don’t file a claim until after your policy expires.[4]
Who Is Professional Liability Insurance Best For?
Professional liability insurance is best for businesses that provide professional services or advice rather than physical products. Examples of small businesses and individual professionals that may need this coverage type include the following:[1][2][4]
- Accountants
- Advertising and marketing firms
- Architects
- Barbershops and hair salons
- Doctors
- Educators
- Engineers
- Financial advisers, career coaches and other consultants
- Graphic designers
- Insurance agents
- Lawyers
- Mental health counselors
- Occupational therapists
- Personal trainers
- Pet groomers
- Photographers
- Printing and publishing companies
- Real estate agents
- Software developers
- Veterinarians
Is Professional Liability Insurance Required?
You could be required by law to carry professional liability insurance depending on your industry and the state you operate in. For example, real estate agents are required to purchase E&O coverage to be licensed in the following states:[5]
|
Alaska |
Louisiana |
North Dakota |
|
Colorado |
Mississippi |
Rhode Island |
|
Idaho |
Montana |
South Dakota |
|
Iowa |
Nebraska |
Tennessee |
|
Kentucky |
New Mexico |
Wyoming |
Who Needs Professional Liability Insurance?
You may be required to purchase professional liability insurance due to state law or federal regulations, depending on your industry. Additionally, this coverage may be necessary as part of a contract with a client to ensure you can cover damages should you make a mistake, error or break the contract.[6] However, most businesses should strongly consider professional liability coverage to protect themselves against financial fallout if they are sued for issues such as negligence, misrepresentation, or providing inaccurate advice to a client.
Professional Liability Examples
Below are a few examples of potential professional liability claims that would typically be covered by E&O insurance:
- E&O insurance could cover a doctor who fails to review a patient’s allergies in the medical chart and prescribes a medication to which the patient is allergic.
- Professional liability insurance could cover legal expenses if a personal injury lawyer falsely claims to have experience as a criminal defense attorney and their client loses the case and is sentenced to jail.
- If a marketing firm becomes the exclusive partner of an entertainment company but breaches the terms of the contract by failing to actually produce and distribute advertisements and merchandise for the entertainment company, E&O coverage could protect you from related lawsuit expenses.
- E&O coverage would cover legal costs if an architect made a mistake in designing the foundation of a new building, causing a portion of the building to collapse shortly after construction and resulting in a lawsuit.
- Professional liability coverage would apply to a compliance consultant who provides a technology company with incorrect information about consumer privacy laws in the company's state, resulting in the company being sued by the state government.
Professional Liability Insurance vs. General Liability Insurance
Below is a breakdown of the differences between professional liability and general liability insurance:[7]
|
|
General Liability |
Professional Liability |
|---|---|---|
| Purpose | Covers physical injury or property damage | Covers financial loss due to an error, omission or professional negligence |
| Types of Claims | Damage to someone’s property or injuries from a slip and fall | Incorrect advice, breach of contract or missed deadlines |
| Common Industries | Retail, manufacturing, restaurants, construction and real estate | Accountants, architects, business consultants and medical professionals |
| Covers Third-Party Injuries/Damage | Yes | No |
| Covers Errors and Omissions | No | Yes |
How Much Does Professional Liability Insurance Cost?
Professional liability insurance costs will vary based on several factors, including your insurance company. For example, small businesses with policies at The Hartford pay an average monthly premium of $76.[8] Alternatively, about 73% of NEXT Insurance customers pay $45 or less for their E&O coverage.[9]
Other factors that will impact your E&O insurance premiums include:[8]
- Your industry
- Location
- Coverage limits
- Deductible
- Size
- Years in business
- Claims history
Professional Liability Insurance at a Glance
- Professional liability insurance is also referred to as errors and omissions (E&O) insurance.
- Professional liability coverage can reimburse you for losses after your business is sued for making an error, omitting essential information or breaking the terms of a contract.
- While typically not required by law, some state or federal regulations may require your business to purchase professional liability insurance, depending on your industry.
- Personal liability insurance can cost less than $100 per month, depending on the insurer, your business’s industry, your coverage limits and other factors.
How To Get Professional Liability Insurance
You’ll want to compare professional liability insurance quotes from at least three to five different commercial insurance companies to find the best possible deal on the coverage your business needs. When you request quotes, you’ll need to share information such as your industry, location, annual revenue and number of employees.
While it can take a while to reach out to several insurers individually, SmartFinancial makes comparison shopping quick and simple. Once you fill out our online questionnaire, we’ll get to work on finding the best commercial insurance policies for your circumstances. Click here to start comparing business insurance quotes at no cost today.
- Insurance quotes /
- Commercial /
- Professional Liability Insurance
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Commercial Insurance Quote.
More on Commercial Insurance

Looking for Commercial Insurance?
Compare rates from dozens of companies in less than 3 minutes.