

Malpractice Insurance: Coverage and Costs Explained
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Medical malpractice insurance covers legal expenses for medical professionals if they are sued for causing a patient's injury or death. If you work in the health care industry, you should consider buying malpractice liability insurance due to the risk of being sued over a perceived error or omission in the performance of your professional duties.
Keep reading to learn what malpractice insurance covers, what malpractice insurance costs, how malpractice insurance claims work and how to obtain coverage to protect yourself and your assets.
|
Key Takeaways
|
On This Page

What Is Malpractice Insurance?
Who Needs Malpractice Insurance?
What Does Malpractice Insurance Cover?
What Isn't Covered by Malpractice Insurance?
Types of Malpractice Insurance Policies
Malpractice Insurance vs. Professional Liability Insurance
How Much Does Malpractice Insurance Cost?
Malpractice Insurance at a Glance
How To Get Malpractice Insurance for Your Business
FAQs

What Is Malpractice Insurance?
Malpractice insurance is a type of professional liability coverage that protects medical professionals against claims of negligence resulting in a patient's injury or death. For example, it could cover you if you are sued for misdiagnosing a patient, making a surgical mistake or recommending a poor treatment plan based on an improper reading of a patient’s chart.
Even if you did not make an error or omission while treating a patient and a court rules in your favor, you could still have to pay expensive legal fees out of pocket if you do not maintain medical malpractice insurance.
What Is Tail Coverage?
Tail coverage, also known as an extended reporting period, is an aspect of claims-based coverage that protects you for claims reported after your policy ends. However, tail coverage only insures against events that happen on or after the retroactive date of your policy through its termination date.[1] For example, if you’re planning to leave your medical practice and drop your medical malpractice insurance coverage, tail coverage could protect you against related lawsuits over perceived mistakes that aren’t brought forward until after you’ve left.
Tail coverage can extend protection for 30 days to three years or longer after your policy ends, depending on your policy. Your policy will typically allow you to add tail coverage as an endorsement if it’s not included automatically, even after canceling or not renewing the policy, though availability can vary by insurer and state requirements.[1]
Who Needs Malpractice Insurance?
All types of health care professionals and those with a risk of injuring clients or patients should consider malpractice insurance coverage, including:
- Paramedics
- Medical students and residents
- Physicians
- Surgeons
- Registered nurses
- Nurse practitioners
- Psychiatrists
- Psychologists
- Physical therapists
- Personal trainers
- Yoga instructors
- Social workers
- Medical technicians
What Does Malpractice Insurance Cover?
Medical professional liability insurance primarily covers legal expenses that stem from a malpractice lawsuit, including defense costs, settlements and judgments. It can also cover other damages you may be expected to pay if you lose your case, such as a patient’s additional medical costs.
Most malpractice insurance policies include Good Samaritan coverage that insures you against liability claims after you try to assist someone outside of your place of business. For example, if someone starts choking while you are at a restaurant and a waiter asks if anyone there is a doctor, your malpractice insurance would apply if you stepped in but failed to save the choking person. Keep in mind that your Good Samaritan coverage may come with a sub-limit.[2]
In addition, some policies may come with sexual misconduct liability insurance that covers legal expenses if you are accused of a non-criminal act of sexual misconduct, such as making an inappropriate comment to a patient.[3]
What Isn't Covered by Malpractice Insurance?
Your malpractice insurance policy won’t provide coverage if you intentionally harm a patient or are impaired by drugs or alcohol while treating a patient. It also doesn’t cover the destruction or falsification of medical records or any kind of criminal activity.
Likewise, your malpractice insurance coverage may not apply to accusations of criminal sexual misconduct, such as sexual assault.[3] In addition, you may need cyber liability insurance to receive coverage for Health Insurance Portability and Accountability Act (HIPAA) violations or other claims that stem from a data breach.
Types of Malpractice Insurance Policies
Medical malpractice insurance typically comes in one of two types that determine when coverage applies to claims: claims-made and occurrence coverage. We’ll cover the differences between these two types below.
Claims-Made Coverage
Malpractice insurance with claims-made coverage will only cover you for claims arising from events that occur while the policy is active. Claims made after this type of policy ends without tail coverage will be denied, even if the event occurred during the policy period. For example, if a claims-made policy was set to last for the calendar year 2027, but a claim involving an event that occurred during that year wasn’t made until 2028, you wouldn’t be covered without an extended reporting period.[4]
Occurrence Coverage
Malpractice insurance with occurrence coverage will protect you from claims arising from events that occurred during the policy period, even if the claim isn’t made until after the period has ended or the policy has been canceled. For example, if an occurrence policy was set to last for the calendar year 2027, but a claim involving an event that occurred during that year wasn’t made until 2028, you would still be covered.[4]
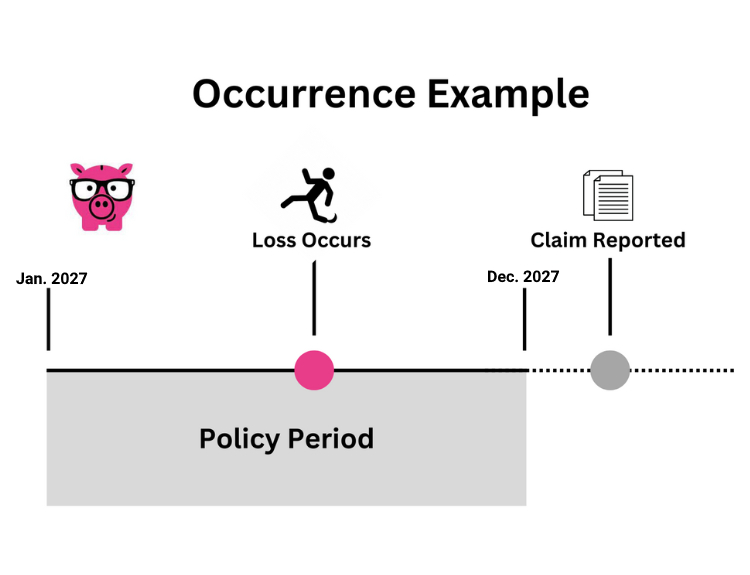
Occurrence coverage policies tend to be more expensive than claims-made policies due to the greater flexibility of coverage and protection from delayed claims. Some claims may not be filed until long after your coverage ends, as injuries or deaths from perceived malpractice often take time to become apparent, which could make the added protection and lower risk of out-of-pocket costs of an occurrence policy more ideal.[5]
Malpractice Insurance vs. Professional Liability Insurance
When comparing malpractice insurance and professional liability insurance, it's important to note that they differ in scope. Malpractice insurance is a specialized form of professional liability insurance designed for medical professionals. While professional liability insurance protects many types of professionals against negligence claims, malpractice insurance specifically addresses claims arising from medical treatment and patient care. We’ll break down these two types of commercial insurance below:[6]
|
Insurance Type |
What's Covered? |
Who’s it For? |
|
Malpractice Insurance |
Professional mistakes that lead to bodily injury or death, legal harm or breach of the expected standard of care. |
Doctors, surgeons, nurses, dentists and other types of health care providers. |
|
Professional Liability Insurance |
Professional negligence, mistakes and failure to deliver services that result in a client’s financial loss. |
Accountants, business consultants, engineers, real estate agents and other professionals. |
How Much Does Malpractice Insurance Cost?
The cost of medical malpractice insurance will vary widely based on the risk associated with your profession. For example, primary care physicians typically pay between $4,000 and $12,000 per year for coverage, while higher-risk specialists, such as neurosurgeons, may pay $50,000 or more per year. Where you work can also influence costs, as some states have higher litigation costs, which can result in higher premiums.[7]
Other factors that can influence your malpractice insurance costs include:[7]
- Claims history
- Policy type (claims-made or occurrence)
- Coverage limits
- Added endorsements, such as tail coverage
- Deductible
Typical Malpractice Coverage Limits
Your typical malpractice coverage limits will vary based on your business’s needs, as some industries may need higher limits than others. Policy limits are usually given as per claim and per policy period. In general, malpractice coverage limits range from $100,000 per claim and $300,000 per policy period to $1 million per claim and $3 million per policy period.[8]
Malpractice Insurance at a Glance
Below is the essential information you should understand about malpractice insurance:
- Malpractice insurance protects you from legal fees and settlements after a claim of malpractice that resulted in a patient’s injury or death.
- Malpractice coverage often also protects you when you act as a Good Samaritan and attempt to help someone outside of a professional setting, such as someone choking at a restaurant or having a heart attack on a plane.
- Malpractice insurance won’t cover you for criminal activity or intentional harm you do to patients. It also won’t cover you for actions taken while intoxicated or under the influence of drugs.
- Timing for claims depends on whether you have a claims-made or occurrence policy, as claims-made coverage requires you to submit any claims during the policy period when the events occur. Endorsements for tail coverage may be available to extend this time past the end of your policy by one or more months.
- Your role as a health care professional, along with the state where you work, can significantly impact your premium costs.
How To Get Malpractice Insurance for Your Business
You’ll want to shop around to find the most affordable malpractice insurance rates. Get quotes from three to five different insurance providers to understand your options. This process can become tedious, as you’ll typically need to gather each quote from insurers one by one.
Speed things up by using an insurance marketplace like SmartFinancial. After answering a brief questionnaire, we’ll connect you with a licensed insurance agent to help you get the coverage you need for your business. Click here for free commercial quotes today!
- Insurance quotes /
- Commercial /
- Malpractice Insurance
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Commercial Insurance Quote.
More on Commercial Insurance

Looking for Commercial Insurance?
Compare rates from dozens of companies in less than 3 minutes.