

Management Liability Insurance: Cost and Coverage Explained
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Management liability insurance can protect your company’s C-suite, managers and other leaders from serious financial losses by covering their legal expenses if they are held personally liable for decisions they make in their roles as corporate executives. Given the high-stakes coverage this category of business insurance provides, it is often more expensive than more basic commercial insurance coverage types.
Keep reading to learn more about insurance protection for your company’s leaders, including what management liability insurance types your policy should include and whether there are management liability requirements.
|
Key Takeaways
|
On This Page

What Is Management Liability Insurance?
How Does Management Liability Insurance Work?
Types of Management Liability Insurance
What Does Management Liability Insurance Cover?
What Isn’t Covered by Management Liability Insurance?
Who Needs Management Liability Insurance?
How Much Does Management Liability Cost?
Management Liability Insurance vs. Executive Liability Insurance
Management Liability Insurance at a Glance
How To Get Management Liability Insurance
FAQs

What Is Management Liability Insurance?
Management liability insurance refers to a suite of commercial insurance products designed to protect corporate directors, managers and other executives against claims of mismanagement or misconduct stemming from their professional roles. The right set of management liability policies can protect both individual executives and companies as a whole from significant financial losses in the event of a lawsuit.
Depending on your insurance carrier and the characteristics of your business, you may be able to bundle various management liability insurance coverages together into a single policy, or you may need to purchase each coverage type separately. The following types of businesses are generally eligible for bundled management liability coverage:[1]
- Privately held companies
- Not-for-profit organizations
- Publicly traded companies with less than $25 million in annual revenue
How Does Management Liability Insurance Work?
Management liability insurance works together with the corporate business structure to protect executive leaders’ personal assets from being jeopardized due to claims related to a company’s commercial operations. When a business is set up as a corporation, it becomes a separate legal entity from its owners, meaning they generally cannot be held personally liable for claims related to the business.[2]
However, a court can “pierce the corporate veil” if an executive commits fraud or conducts business activities to their own personal benefit such that the legal distinction between them and their company ceases to exist.[2] In this case, management liability insurance can cover relevant expenses so the officer’s personal assets aren’t at risk, allowing them to make business decisions confidently without the fear of losing their personal property or bank accounts.[1]
| Type of Protection | Explanation |
| Corporation structure | Prevents business owners’ and officers’ personal assets from being seized to pay off business debts in most situations |
| Management liability insurance | Covers legal fees and other related expenses in certain cases where a corporate executive is sued due to their work and a judge rules to “pierce the corporate veil,” keeping the executive’s personal assets from being seized to cover these expenses |
Types of Management Liability Insurance
Your management liability insurance package ought to include several different types of commercial insurance. Read on to learn about the most important coverage options you need to consider.
Commercial Crime
Commercial crime insurance can shield a business owner from major financial losses if they are the victim of criminal actions — including those committed by their own employees. Examples of covered crimes include the following:[3][4]
- Employee dishonesty
- Embezzlement
- Forgery or counterfeiting
- Robbery
- Wire transfer fraud
- Social engineering fraud
Directors and Officers Liability
Directors and officers liability insurance protects corporate leaders from lawsuits stemming from alleged wrongful acts related to their work as executives, such as poor stock performance, misrepresentation in financial reports or failure to comply with legal regulations.[5] Along with protecting the directors and officers themselves, D&O coverage keeps businesses from having to pay legal defense and settlement costs for their leaders out of pocket.[1]
Employment Practices Liability
Employment practices liability insurance can cover attorney fees, court-ordered damages and other legal expenses if a corporate executive is accused of violating an employee’s rights. For example, EPLI may step in if you are sued over any of the following allegations:[4]
- Discrimination
- Wrongful termination
- Sexual harassment
- Creation of a hostile work environment
- Breach of employment contract
- Failure to provide time off in accordance with the Family and Medical Leave Act
Fiduciary Liability
Fiduciary liability insurance covers officials accused of failing to adequately manage employee benefit plans or comply with the Employee Retirement Income Security Act.[3] Other covered claims may include bad financial advice or poor investment selections for employee retirement accounts. Some policies also cover benefit administration and enrollment errors, but certain insurers may cover these claims separately under employee benefits liability insurance.[4][6]
Kidnap, Ransom and Extortion
In the event that one of your executives is threatened and abducted, you can file a claim on your kidnap, ransom and extortion insurance to cover expenses like hiring negotiators and paying to secure the director’s freedom. This type of coverage may be particularly useful for large, multinational corporations operating in regions with a high rate of criminal activity.[1]
Nonprofit Board and Executive Liability
Even though they are often unpaid volunteers, nonprofit board members still need adequate management liability coverage to protect against claims of discrimination, misuse of funds and other executive failures. For example, the Nonprofits Insurance Alliance offers a specialized nonprofit insurance package known as board and executive liability insurance, which includes EPLI, D&O and fiduciary liability coverage.[7]
What Does Management Liability Insurance Cover?
Coverage specifics may vary based on the coverage types included in your policy, but you can generally obtain management liability coverage for the following expenses and situations:
- Lawyer fees, judgments, settlements and other legal costs
- Crimes committed by employees and third parties
- Corporate misconduct, misuse of company funds and regulatory noncompliance
- Harassment, discrimination and wrongful termination
- Errors and omissions in the administration of employee benefit programs
- Ransom payments for kidnapped executives
- Lawsuits targeting the members of a nonprofit’s board of directors
What Isn’t Covered by Management Liability Insurance?
While management liability insurance can cover numerous allegations of corporate failures or misconduct, it generally doesn’t protect against common losses you are likely to experience in your day-to-day operations. View the following table to see examples of losses that aren’t covered by management liability insurance — and which types of commercial insurance would cover them instead:
| Losses | Covered By |
| Third-party bodily injury, property damage and personal or advertising injury claims | General liability insurance |
| Damage to business-owned buildings or items from sudden perils, such as fire or vandalism | Commercial property insurance |
| Mistakes in the performance of professional services, such as negligence or breach of contract | Professional liability insurance |
| Bodily injury and property damage claims stemming from commercial vehicle accidents or other vehicle-related incidents | Commercial auto insurance |
| Employee injuries, illnesses or deaths | Workers’ compensation insurance |
| Losses stemming from cybercrimes, such as data breaches | Cyber insurance |
Who Needs Management Liability Insurance?
Any business with directors or officers tasked with making high-level corporate decisions would benefit from maintaining management liability insurance coverage. That said, coverage may be especially important if any of the following characteristics apply to your company:[1]
- Highly-regulated industry
- Complicated employment practices
- Involvement in substantial financial transactions
- Oversight of employee benefit plans
How Much Does Management Liability Cost?
A comprehensive management liability insurance policy can potentially cost tens of thousands of dollars per year, though you will likely qualify for discounted rates if you opt for a package policy rather than buying each coverage type individually.[1] In the upcoming table, you’ll see approximate premiums for some of the coverages that may be included in your management liability insurance policy:[7][8][9][10]
| Coverage Type | Starting Annual Rate or Average Annual Price Range |
| Board and executive liability insurance | $1,280 to $2,075 |
| Commercial crime insurance | $1,500 to $35,000 |
| D&O liability insurance | $9,000 to $30,000 |
| EPLI add-on to general liability insurance | $215 per employee |
| Fiduciary liability insurance | $500 to $2,500 |
What Affects the Cost of Management Liability Insurance?
These factors will likely play a significant role in determining how much you have to pay for commercial management liability insurance:[8]
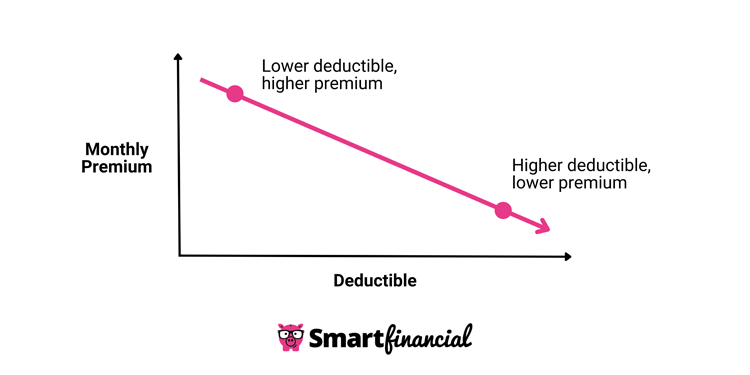
- Policy details: The higher your coverage limits and the lower your deductibles are, the more expensive you can generally expect your management liability insurance policy to be.
- Claims history: Businesses that have filed more insurance claims in the past often have to pay more for coverage, since they are viewed as more likely to file additional claims going forward.
- Industry: You could encounter higher management liability insurance premiums if the risks associated with your industry make you more likely to file claims. For example, national retail chains with a large number of employees may have a higher exposure to employment practices lawsuits, so they may have to pay more for EPLI.
- Size: Your insurance premiums will also depend on the size and scale of your business operations — with businesses that have many locations and high annual revenue generally encountering costlier insurance policies.
- Location: Certain regional risk factors may influence the amount you have to pay for business insurance coverage. For example, if you operate in a city with a high rate of break-ins, you may be charged more for commercial crime insurance.
- Risk mitigation procedures: Discounts are often available if you take steps to minimize your chances of experiencing a loss that would necessitate filing a claim on your management liability policy — such as requiring managers to undergo mandatory training to help prevent benefit administration mistakes or workplace harassment accusations.
Management Liability Insurance vs. Executive Liability Insurance
Executive liability insurance is another name for management liability insurance, so insurance companies may use the two terms interchangeably.[1] Keep in mind that neither of these terms refers to a singular insurance product, but instead a collection of business insurance coverage types that can address the risks most commonly facing corporate executives and other leaders.
Management Liability Insurance at a Glance
- Definition: Management liability insurance refers to a collection of business insurance policies that provide specialized protection for executives and other corporate directors or officers.
- Availability: You may be able to obtain management liability insurance coverage types separately or as part of a combined insurance package, depending on your company’s size and risk exposure.
- Protection: Management liability coverage works in conjunction with the corporate business structure to shield executives’ personal assets from being seized to cover business-related debts in the event of a costly lawsuit.
- Options: Coverage types you may want to purchase to protect your corporate managers include commercial crime, directors and officers liability, employment practices liability and fiduciary liability insurance. Other specialized coverage options may include kidnap, ransom and extortion insurance for businesses operating in especially high-risk regions or industries and board and executive liability insurance for nonprofit boards.
- Coverage: Your management liability insurance policy may cover claims related to theft and other crimes, poor management of finances or other business matters, violations of employee rights and failure to adequately fund or manage employee benefit plans.
- Exclusions: Management liability insurance isn’t designed to cover regular losses associated with everyday business operations, so you will also need to maintain coverages like general liability, commercial auto and workers’ compensation insurance.
- Cost: The cost of a management liability policy can reach upwards of $70,000 per year, depending on factors like your coverage details, industry, claims history and location.
How To Get Management Liability Insurance
It’s best to analyze quotes from around three to five separate insurance carriers before choosing a management liability insurance policy for your business. That way, you can ensure you’re getting the best possible deal on the coverage you need. However, individually contacting insurers to give them your information and request quotes can be incredibly time-consuming.
Instead, consider shopping through SmartFinancial. We’ll collect your information through a single questionnaire and do the bulk of the work of collecting quotes for you, resulting in a conveniently streamlined comparison shopping process. Enter your ZIP code and start comparing free commercial insurance quotes today — potentially in as little as a few minutes!
- Insurance quotes /
- Commercial /
- What Is Management Liability Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Commercial Insurance Quote.
More on Commercial Insurance

Looking for Commercial Insurance?
Compare rates from dozens of companies in less than 3 minutes.