

Directors & Officers Insurance Explained: Coverage, Costs & Benefits
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Directors and officers liability insurance, or D&O insurance, helps protect business executives if someone files a lawsuit against them for alleged mismanagement of a company, such as taking company funds for personal use or intellectual property theft. This type of business insurance coverage can be critical for some companies, as it helps protect their leadership talent from financial losses, alongside the companies if they’re bound to cover legal expenses.
Keep reading to learn more about this type of commercial insurance, including what it covers, what benefits it offers and what factors contribute to insurance costs.
|
Key Takeaways
|


What Is D&O Insurance?
D&O insurance is a type of business insurance that protects company directors and officers when they are sued for alleged wrongdoing while serving as corporate executives. For example, if an executive fails to implement corporate governance, steals intellectual property or misuses company funds, D&O insurance could help cover the costs of attorney fees, judgments and settlements and protect the executive’s personal assets.
Keep in mind that, while CEOs’ personal assets usually aren’t at risk over business-related claims, they can be held personally liable in certain circumstances, like when there is a conflation of their personal and corporate assets or they have failed to comply with laws intentionally or with gross negligence.[1]
Without D&O insurance, either the officer or the company would need to cover any legal fees associated with a lawsuit for mismanagement or noncompliance. Many companies employ indemnification clauses to protect their directors and officers and may take the brunt of a lawsuit’s legal fees, which D&O insurance can help reimburse.
Is D&O Insurance Required?
Although D&O insurance isn’t typically required by law, businesses should still consider it. Some executives may require this form of insurance to cover them before accepting a job at a company to give them peace of mind while performing the role, as they may otherwise risk personal financial loss if they are sued for making decisions on behalf of the company.
If the executive’s contract includes an indemnification clause, this insurance could cover the potential legal fees the business would be responsible for. In these instances, some executives, board members or investors may require D&O insurance to cover the company and prevent the financial burden of a lawsuit, which could disrupt operations or close the company.[2]
How Does D&O Insurance Work?
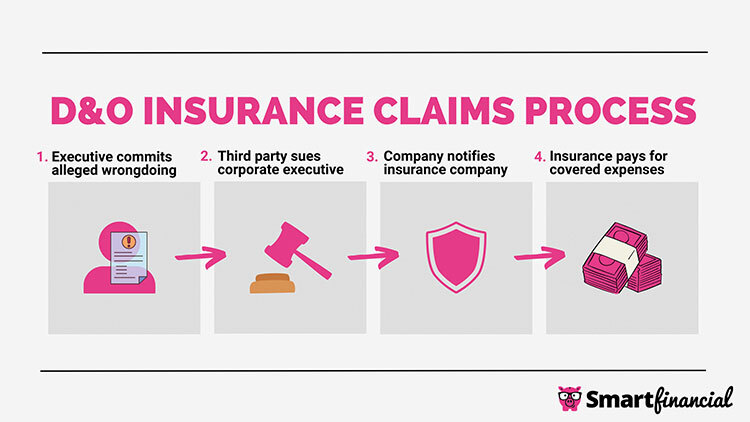
When a customer, employee, competitor, vendor or some other third party accuses a director or officer of wrongdoing, the company can file a claim with the D&O insurance carrier for reimbursement. The carrier will then investigate the claim to determine if it is covered under the policy. If the claim is covered, the carrier may pay for the executive’s legal defense, a settlement or any damages that may be awarded to the plaintiff.
In general, the alleged wrongful act must occur and the subsequent claim be filed while the policy is active for a D&O insurance claim to be approved. This means that claims made for acts that occurred before the policy began typically won’t be covered.[3]
Additionally, D&O insurance carriers do not have a legal obligation to defend the insured and may apply shrinking limits to defense costs, meaning any money spent on defending the director or officer may lower the amount of money available for settlements or court-ordered payments.[3]
Who Is D&O Insurance Best For?
D&O insurance can benefit businesses of any size, including nonprofit organizations, by protecting executives from the costs of potential lawsuits while they make company decisions. D&O insurance can also incentivize potential executive talent, as it provides peace of mind when making difficult decisions and potential missteps on behalf of a company.
Regardless of industry, businesses looking to grow or go public may want to consider D&O insurance. For example, it may allow companies to attract or retain leadership talent in addition to meeting the needs of investors who want to safeguard their financial backing. This insurance coverage is also significant for publicly traded companies, especially those that recently filed an initial public offering (IPO), as liability risks often increase during the first three years after an IPO.[4]
What Does D&O Insurance Cover?
D&O insurance will cover several types of misconduct or wrongful acts allegedly committed by a director or officer while performing their duties, including:[2]
- Poor performance of a company or its stock
- Mismanagement or neglect of company finances
- Misrepresentation
- Decisions beyond the executive’s authority
- Noncompliance with regulations or laws, including those related to the environment
- Human resources issues, such as discrimination
- Cyber liability issues
What Isn’t Covered by D&O Insurance?
D&O insurance generally does not cover the scenarios below:[2]
- Bodily injury
- Property damage
- Deliberate fraud
- Embezzlement
- ERISA violations, including errors in the administration of 401(k) plans and other employee benefits
- Claims that occurred before the policy coverage start date or after its end date
- Claims involving multiple insureds covered by the same policy who are suing each other
What Types of D&O Liability Insurance Are There?
Businesses can choose from three types of D&O insurance policies: Side A, B or C. Keep in mind that not all D&O policies will cover all sides, and some businesses will not require each form of coverage.
The policy recommended will depend on your company’s financial situation and whether it’s a private startup or a publicly traded industry leader. Below, we’ll break down the different sides to help you determine which might be best for your business.[2]
- Side A coverage: This type of D&O insurance provides coverage for directors or officers not indemnified by the corporation. This means the corporation will not cover the directors or officers and insurance payouts will go directly to the executive filing the claim.
- Side B coverage: This coverage insures directors or officers indemnified by the corporation. This means the corporation would reimburse the leader’s defense costs and damages after the alleged wrongdoing, and then the insurance company would reimburse the corporation.
- Side C coverage: Also called entity coverage, this type of policy covers the business if it is named in a lawsuit alongside a director or officer. This means that the company itself is directly protected from financial risk.
How Much Does D&O Insurance Cost?
Large companies earning up to $50 million annually pay an average of $5,000 to $10,000 per year for $1 million worth of D&O liability coverage.[5] You should note that D&O insurance premiums can vary between insurers, as they often use separate methods of underwriting that weigh factors differently. Some of these factors may include:
- Business size: Larger organizations and publicly traded companies may be considered higher risks and typically pay more for D&O insurance.
- Industry: Companies in specific industries, such as financial services or health care, may be considered higher risk and may pay more for D&O insurance.
- Number and types of directors and officers: The number and types of directors and officers can affect the cost of D&O insurance, as some individuals may be considered higher risk due to their position or responsibilities within the organization.
- Financial performance: Companies with a history of financial difficulties or unstable financial performance may be considered higher risk and may face higher D&O rates.
- Claims history: Companies with a history of claims or lawsuits may be considered higher risk and may pay more for D&O insurance.
- Coverage limits: Higher D&O coverage limits provide additional coverage but will also cost more.
- Policy deductible: Higher deductibles will generally result in lower premiums.
How To Get D&O Insurance
Shopping around for D&O policies can help you determine your range of premiums and coverage, so try to get quotes from three to five insurance companies. You’ll typically need to provide information about your company, its leadership and other factors to each company individually, which can become tedious.
You can speed up this process by using an insurance marketplace like SmartFinancial. After a brief questionnaire, we can connect you with a licensed insurance agent who can help you and your executive team obtain the commercial insurance coverage that meets your goals. Click here for a free commercial insurance quote today!
- Insurance quotes /
- Commercial /
- Directors And Officers Liability Insurance
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Commercial Insurance Quote.
More on Commercial Insurance

Looking for Commercial Insurance?
Compare rates from dozens of companies in less than 3 minutes.