

Liquor Liability Insurance: What Your Business Needs To Serve Alcohol
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
If you run a bar, restaurant or other business that serves alcohol, liquor liability insurance helps protect you from financial losses if an intoxicated guest causes bodily injury or property damage. This commercial insurance coverage may cost as little as a few hundred dollars per year, depending on your risk level and policy details.
Read below to learn more about liquor liability coverage, including what types of businesses need it, what it covers and how the cost of liquor liability insurance is determined.
|
Key Takeaways
|
On This Page

What Is Liquor Liability Insurance?
What Does Liquor Liability Insurance Cover?
What Doesn’t Liquor Liability Insurance Cover?
How Much Does Liquor Liability Insurance Cost?
Who Needs Liquor Liability Insurance?
When Is Liquor Liability Insurance Required?
Liquor Liability Insurance Requirements by State
Host Liquor Liability vs. Commercial Liquor Liability
Liquor Liability Insurance at a Glance
How To Get Liquor Liability Insurance
FAQs

What Is Liquor Liability Insurance?
Liquor liability insurance is a type of business insurance that can shield you from major financial losses if you are held responsible for the actions of an intoxicated individual who bought alcohol from your business or was served alcohol on your business premises. You may be able to add liquor liability coverage to your general liability insurance or buy it as a standalone policy.[1] Coverage may also be available through a one-time event insurance policy.[2]
What Is Dram Shop Insurance?
Dram shop insurance is another name for liquor liability insurance.[1] The name is derived from dram shop laws, which have been enacted in most states. These laws allow businesses that serve alcoholic beverages to be held liable for and sued over the actions of certain individuals they gave alcohol to — usually people under the age of 21 or those who were already visibly drunk before receiving alcohol from the liable business.[3]
|
|
Dram Shop Law |
Liquor Liability Insurance |
|
Explanation |
Allows individuals who are injured by or experience property damage because of drunken people to sue the businesses that served them alcohol in certain cases |
Covers medical treatments, property repairs and legal expenses in the event that a business owner is sued over the actions of someone who obtained alcohol from their business |
|
Function |
Protects the victims of intoxicated individuals — especially when the intoxicated person does not have their own insurance coverage |
Protects businesses that serve alcohol from bearing the full burden of costly legal action whenever they are sued due to their regular business operations |
What Does Liquor Liability Insurance Cover?
Liquor liability insurance can cover the following expenses if your company is held liable for harm caused by an intoxicated patron:[1]
- Medical bills: Your liquor liability insurance may cover medical treatments if one of your customers gets drunk and commits assault and battery or otherwise injures someone else. This coverage may also apply if the drunken guest hurts themselves — like if they fall off the stage at your karaoke bar and get a concussion.
- Property repairs: A standard liquor liability policy can also pay to repair or replace property that is damaged or destroyed by a patron you served alcohol to. For example, this coverage may step in if two customers at your restaurant get into a drunken argument and one of them shatters the other’s cell phone.
- Legal expenses: Bartender liability insurance may take care of attorney fees, judgments, settlements and other legal costs if a bodily injury or property damage claim escalates into a lawsuit. For example, you may be covered if you are sued after someone leaves an event you hosted and kills a pedestrian in a drunk driving accident.
What Doesn’t Liquor Liability Insurance Cover?
The primary role of liquor liability insurance is to cover other people’s expenses that your business is responsible for, so your policy likely won’t cover damage to your commercial building or business personal property inflicted by a drunken patron. In addition, liquor liability insurance policies generally exclude coverage for criminal actions — including selling alcohol to minors.[5]
How Much Does Liquor Liability Insurance Cost?
You may be able to get liquor liability insurance for as little as $300 per year through the Food Liability Insurance Program. However, your premiums may depend on how you choose to obtain coverage. For example, FLIP charges $100 for short-term event liquor liability coverage, while it offers a bundle with general liability and liquor liability insurance for $453 per year.[2]
The cost of your liquor liability insurance policy may also vary based on the following factors:[1]
- Industry: Naturally, certain industries have a higher likelihood of encountering liquor liability claims, so high-risk businesses can expect to pay more for coverage. For example, a wedding planner who organizes open bars may have higher premiums than a business owner who hosts wine tastings with relatively minimal alcohol consumption.
- Location: Certain location-based factors may influence the amount you have to spend on liquor liability insurance. For example, if you live in a densely populated city with a high amount of foot traffic, you may have a higher exposure to liability-related losses.
- Coverage limits: Policies that offer a higher amount of coverage typically require higher premiums, so your policy could be more expensive if your state requires high liquor liability coverage limits for businesses in your industry.
- Sales: Insurance companies may consider what percentage of your total revenue comes from alcohol sales when setting your liquor liability insurance rates. As a result, a bar that generates most of its income from alcohol sales will generally have to pay more than a grocery store that generates only a small portion of its income from alcohol sales.
Who Needs Liquor Liability Insurance?
Examples of the kinds of businesses and professionals that may benefit from maintaining liquor liability insurance include the following:[2][4]
- Bartenders
- Caterers
- Event and wedding vendors
- Food trucks
- Personal chefs
- Restaurants
- Liquor stores
- Grocery stores
- Breweries
- Nightclubs
- Music venues
- Wineries
- Hotels and resorts
- Sports stadiums
- Casinos
- Festivals and fairs
When Is Liquor Liability Insurance Required?
Liquor liability insurance may be required by law in some states. For example, South Carolina enacted a law in 2025 requiring businesses that sell alcohol for on-premises consumption after 5 p.m. to maintain at least $1 million worth of general or liquor liability insurance. That said, the South Carolina law allows businesses to lower the mandatory coverage amounts by taking steps like stopping alcohol sales at midnight or requiring employee training.[6]
Additionally, liquor liability insurance coverage may be necessary in the following situations:[7]
- Professional licensing: Some state licensing boards may require you to obtain liquor liability insurance in order to qualify for a liquor license.
- Property rentals: If you rent commercial property for your business, your landlord may request proof of liquor liability coverage to verify that you can stay in business and keep making rent payments in the event of a liability claim related to someone who received alcohol at your establishment.
- Loan covenants: Similarly, banks and other lenders may ask to see a certificate of liability insurance before approving you for a business loan.
Liquor Liability Insurance Requirements by State
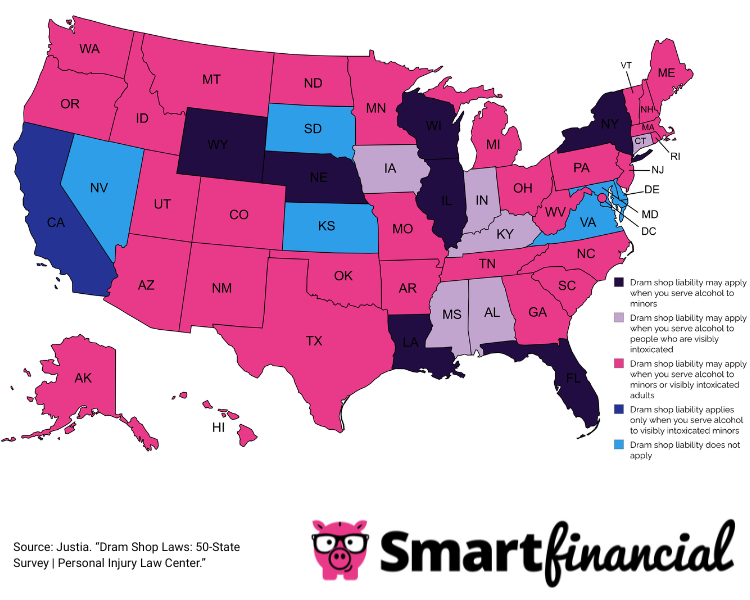
Although liquor liability coverage is recommended for most businesses that serve alcohol, the extent to which you need it may depend on your state’s dram shop statutes or court decisions. See the following table for an overview of when you could be held liable for the actions of a drunken patron of your business, depending on where you operate:[3]
|
State/District |
Dram Shop Law |
|
Alabama |
Businesses can be held liable if they serve alcohol to visibly intoxicated people |
|
Alaska |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people |
|
Arizona |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people |
|
Arkansas |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people |
|
Businesses can be held liable if they serve alcohol to visibly intoxicated minors |
|
|
Colorado |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people |
|
Connecticut |
Businesses can be held liable if they serve alcohol to visibly intoxicated people |
|
Delaware |
No dram shop law |
|
Florida |
Businesses can be held liable if they serve alcohol to minors or alcoholics |
|
Georgia |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people |
|
Hawaii |
Businesses can be held liable if they serve alcohol to minors, visibly intoxicated people, alcoholics or people who intend to drink while driving |
|
Idaho |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people |
|
Illinois |
Businesses can be held liable if they cause anyone to get drunk or enable alcohol consumption by a minor — such as by paying for a motel room for them so they will have somewhere to drink |
|
Indiana |
Businesses can be held liable if they serve alcohol to visibly intoxicated people |
|
Iowa |
Businesses can be held liable if they serve alcohol to visibly intoxicated people |
|
Kansas |
No dram shop law |
|
Kentucky |
Businesses can be held liable if they serve alcohol to visibly intoxicated people |
|
Louisiana |
Businesses can be held liable if they negligently serve alcohol to minors |
|
Maine |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people |
|
Maryland |
No dram shop law |
|
Massachusetts |
Businesses can be held liable if they negligently serve alcohol to minors or visibly intoxicated people |
|
Michigan |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people |
|
Minnesota |
Businesses can be held liable if they illegally sell alcohol or enable minors to consume alcohol |
|
Mississippi |
Businesses can be held liable if they serve alcohol to visibly intoxicated people |
|
Missouri |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people |
|
Montana |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people, force someone to drink alcohol or falsely say a drink does not contain alcohol |
|
Nebraska |
Businesses can be held liable if they serve alcohol to minors |
|
Nevada |
Liquor liability laws may apply to individuals who serve alcohol to minors but not to licensed sellers who do so |
|
New Hampshire |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people or otherwise serve alcohol in a reckless manner |
|
New Jersey |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people |
|
New Mexico |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people |
|
New York |
Businesses can be held liable if they sell alcohol illegally |
|
North Carolina |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people |
|
North Dakota |
Businesses can be held liable if they serve alcohol to minors, visibly intoxicated people or anyone else who is not competent to purchase alcohol |
|
Ohio |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people, and they may also be broadly liable for any liquor liability claims that occur on their business premises |
|
Oklahoma |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people |
|
Oregon |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people |
|
Pennsylvania |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people |
|
Rhode Island |
Businesses can be held liable if they recklessly or negligently serve alcohol to minors or visibly intoxicated people |
|
South Carolina |
Businesses may be held liable if they negligently serve alcohol to minors or visibly intoxicated people |
|
South Dakota |
No dram shop law |
|
Tennessee |
Businesses can be held liable if a jury finds beyond a reasonable doubt that they knowingly served alcohol to minors or intoxicated people |
|
Texas |
Businesses can be held liable if they serve alcohol to visibly intoxicated people — unless they can prove that they trained their employees to avoid such incidents — or to minors under the age of 18 |
|
Utah |
Businesses can be held liable if they serve alcohol to minors, visibly intoxicated people or anyone else who shouldn’t be able to make the decision to purchase alcohol for themselves |
|
Vermont |
Businesses can be held liable if they serve alcohol to minors, visibly intoxicated people, someone they could reasonably expect to be drunk due to the amount of alcohol they have consumed or anyone after legal serving hours |
|
Virginia |
No dram shop law |
|
Washington |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people |
|
Washington, D.C. |
Businesses can be held liable if they serve alcohol to minors or visibly intoxicated people |
|
West Virginia |
Businesses can be held liable if they serve alcohol to minors, visibly intoxicated people or anyone after legal serving hours |
|
Wisconsin |
Businesses can be held liable if they knowingly serve alcohol to minors, force someone to drink alcohol or falsely say a drink does not contain alcohol |
|
Wyoming |
Businesses can be held liable if they illegally sell alcohol |
Host Liquor Liability vs. Commercial Liquor Liability
Host liquor liability coverage is a subset of liquor liability insurance that can protect companies that serve alcohol at special events but do not otherwise sell alcohol as part of their regular business operations. Since it addresses relatively infrequent or minor liability exposures, host liquor liability insurance does not need to be purchased as a separate policy — instead, it is usually available through a general liability or event insurance policy.[1][5]
|
|
Liquor Liability Insurance |
Host Liquor Liability Insurance |
|
Function |
Insures businesses that regularly serve alcohol against liability claims related to customers who get drunk on their premises |
Covers incidental liquor liability exposures for businesses that don’t sell alcohol but occasionally allow people to drink on their premises |
|
Example |
You are sued after a regular customer at your bar gets into a drunken altercation and punches an innocent bystander |
One of your employees gets drunk and breaks a colleague’s serving dish at your office holiday party |
|
Who Needs It |
Bars, restaurants and other businesses that sell or serve alcohol as part of their normal business operations |
Consulting companies, accounting firms and other businesses that occasionally allow employees or other guests to drink at corporate events |
|
How To Obtain It |
Standalone policy or general liability insurance endorsement |
Automatically included in general liability insurance or special event insurance |
Liquor Liability Insurance at a Glance
- Definition: Liquor liability insurance is a type of commercial insurance that can shield business owners who sell or serve alcohol from claims involving guests who get drunk at or because of their business.
- Coverage: Your liquor liability policy can cover medical treatments, repair bills and legal fees if you are sued after a drunken patron causes bodily injury or property damage to another person.
- Exclusions: Typically, liquor liability insurance doesn’t cover damage to your own property or claims involving the intentional sale of alcohol to minors.
- Costs: You can generally expect to pay at least $300 per year for liquor liability insurance, but your premiums will ultimately depend on factors like your location, industry and policy details.
- Who needs it: Examples of businesses that often need liquor liability coverage include bars, restaurants, event venues, breweries, wineries, clubs and grocery stores.
- Dram shop liability: In most states, businesses can be held liable for the actions of certain individuals they sell or serve alcohol to, such as minors or adults who are already intoxicated. Liquor liability insurance may provide coverage in the event of a lawsuit, though coverage may be restricted if you are sued for selling alcohol illegally.
- Host coverage: Host liquor liability insurance provides coverage for businesses that don’t regularly sell alcohol but serve it on occasion — like for office holiday parties and similar corporate events. This coverage type is not available as a standalone policy but may be automatically included in your general liability or event insurance.
How To Get Liquor Liability Insurance
To find the best liquor liability insurance coverage at the lowest cost, you’ll need to compare quotes from at least three to five business insurance companies. That said, it can undoubtedly be frustrating to individually reach out to multiple carriers to give them the information needed to generate quotes, such as your company’s industry, location, annual revenue and employee headcount.
For a more seamless comparison shopping experience, try using SmartFinancial. Take just a few minutes to answer some questions about your coverage needs, and then we’ll help you sort through the best available insurance policies for your business. Click here to type in your ZIP code and begin the process of comparing commercial insurance quotes at no cost today!
- Insurance quotes /
- Commercial /
- Liquor Liability Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Commercial Insurance Quote.
More on Commercial Insurance

Looking for Commercial Insurance?
Compare rates from dozens of companies in less than 3 minutes.