
Rising Temperatures and Insurance: How Extreme Heat Impacts Coverage and Costs
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Rising temperatures and insurance prices may be correlated, as natural disasters triggered by hot weather can lead to an increase in property and casualty insurance claims — which can, in turn, lead to higher premiums. To minimize rate hikes and coverage restrictions, insurers and policyholders alike may need to adapt to climate change by leveraging predictive analytics and loss-prevention techniques.
Homeowners may also face insurance risks related to prolonged periods of extreme heat, including damage to roofs, HVAC systems and other property exposed to sustained high temperatures. While homeowners insurance may cover certain sudden and accidental losses caused by extreme weather, coverage for heat-related wear and tear is typically excluded.
Continue reading to learn more about heat waves and insurance, including how different types of policies are impacted and what insurance risks from rising temperatures you need to be aware of.
|
Key Takeaways
|
On This Page

Why Rising Temperatures Matter to the Insurance Industry
How Extreme Heat Impacts Insurance
Why Insurance Premiums Are Rising in Hotter Regions
What Are Insurers Doing To Adapt to Climate Risk?
Rising Temperatures and Insurance at a Glance
How To Reduce Heat-Related Insurance Risks
Rising Temperatures and Insurance FAQs

Why Rising Temperatures Matter to the Insurance Industry
Rising temperatures can have a significant impact on the insurance industry because heat waves are capable of causing property damage and health problems that may be covered by various types of insurance policies. If you file a claim on your homeowners or auto insurance for heat-related damage, you can generally expect your insurance premiums to go up.
Even if you do not personally experience any losses that require you to file claims, your insurance carrier could still raise your rates to offset its increased spending if a large number of people in your area file heat-related insurance claims. As a result, steadily rising temperatures have the potential to drive up home and car insurance prices more rapidly in affected regions.
Rising temperatures can also affect insurance availability, as some insurers limit coverage or stop writing new policies in areas facing elevated climate-related risks.
|
Factor |
Impact |
|---|---|
|
Rising temperatures driven by climate change |
Certain types of catastrophes become more common and powerful |
|
Increased prevalence of damaging disasters |
Insurance companies must spend more money on settlements for covered losses |
|
Increased insurance spending |
Insurers must raise their policyholders’ premiums to account for the fact that they are paying out more to those who file claims |
How Extreme Heat Impacts Insurance
How heat can affect insurance depends on the type of policy you have. The following sections explain how extreme heat can impact different types of insurance coverage.
Home Insurance
Here are examples of how extreme heat can have a relevant impact on your homeowners insurance:
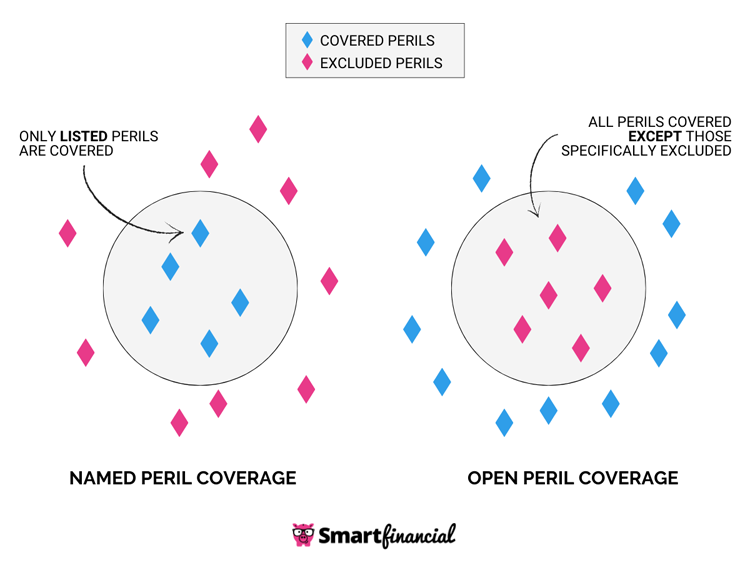
- Direct damage from heat: Most homeowners policies provide open peril coverage for the structure of your home, so damage directly caused by heat — such as a window that suddenly cracks — may be covered unless your policy specifically excludes coverage for heat waves. Conversely, your belongings are usually insured on a named peril basis, and heat is not among the named perils typically covered.
- Wildfires: Hot, dry weather conditions make it easier for wildfires to start and spread, potentially leading to a substantial amount of insured property losses. If the threat of wildfire damage is too high in a certain region, property insurers may stop selling policies in that area. Alternatively, they may opt to exclude coverage for fire from their policies — though this may require express written notice, depending on the state.[1]
- Other indirect heat damage: Record-breaking heat can help cause other types of perils that may be covered by home insurance as well. For example, warm air near the surface of the Earth contributes to the formation of thunderstorms.[2] Your homeowners policy may cover numerous storm-related perils, including lightning, wind, hail and falling objects, like trees.
- Progressive loss exclusions: Something to keep in mind is that insurance generally only covers unexpected losses. Although your home insurance policy may cover sudden damage due to a heat wave, it likely won’t cover gradual damage caused by temperatures going up over time.
Auto Insurance
Some of the ways rising temperatures can affect your car insurance coverage include the following:
- Sudden damage: If your car insurance policy includes comprehensive coverage, it may cover various heat-related perils that cause sudden damage to your vehicle. For example, your comprehensive insurance will likely pay for repairs if your car experiences wildfire or storm damage.
- Maintenance issues: Conversely, heat-related damage that occurs gradually or could have been prevented with proper care generally isn’t covered by auto insurance. For example, you may not be covered if your engine overheats and breaks down because you forgot to refill your coolant before taking a summer road trip.
- Increased crash risk: Fluctuating temperatures amid heat waves are associated with an increase in car accidents, potentially because heat can cause fatigue and discomfort that distracts drivers.[3] As a result, persistently rising temperatures can lead to more traffic crashes that may be covered under auto liability or collision insurance policies.
Business Insurance
Business owners must consider several different ways that extreme heat could interact with their commercial insurance, such as the following:
- Liability claims: If you don’t take proper steps to shield your customers from the heat, you could potentially be sued and need to file a claim on your general liability insurance. For example, you could be held liable for failing to provide proper shade if someone experiences a heat-related illness while playing on your outdoor mini-golf course.
- Food spoilage: Restaurants may need specialized spoilage and contamination insurance to cover costs like replacing food and cleaning equipment in the event that heat causes their inventory to go bad — like if an extended power outage occurs after everyone in town turns up their air conditioning amid a heat wave.[4]
- Property damage and business interruptions: Business insurance may also step in if a heat-related peril damages your property and prevents you from operating your business as usual. For example, in the event of a wildfire, commercial property insurance could pay to rebuild your office building, while business interruption insurance could help you rent another office space while you wait for a new permanent location.
- Workers’ compensation claims: Heat stress may lead to an increase in workers’ compensation insurance claims by causing exhaustion, cramps, rashes and other conditions.[5][6] For example, the owner of a construction company may need to file a workers’ compensation claim after their employee experiences heatstroke on the job.
Health Insurance
Read below to see how high temperatures may influence your health insurance plan:
- Adverse health effects: Heat waves can lead to numerous adverse effects on human health that may require medical attention — from triggering deadly conditions like heatstroke to worsening existing conditions, such as heart disease, mental illness, respiratory disease or diabetes.[7]
- Rate hike protections: Health Insurance Marketplace plans function differently from other types of insurance in that insurers can’t take your medical history into account when setting rates.[8] This means receiving medical care for heat-related ailments may not cause your insurance prices to go up in the same way that filing a home or auto insurance claim would.
- Out-of-pocket spending: Even if your insurer isn’t allowed to raise your premiums, you’ll still pay more if you need to receive medical services more frequently due to extreme heat because of cost-sharing requirements. Most plans come with a deductible that you must reach before your coverage takes effect for the year — after which, you may still have to cover a portion of the costs by paying copays or coinsurance.
Why Insurance Premiums Are Rising in Hotter Regions
Climate change can lead to higher insurance premiums in certain drought-prone regions by increasing the prevalence of devastating natural disasters — especially fires and windstorms. Because of their capacity to completely destroy homes, wildfires and hurricanes are often associated with very high insurance payouts.
Property and casualty insurance rates are also shaped by the cost of reinsurance — which refers to insurance policies purchased by insurance companies to help cover payouts in case of a high volume of costly claims. Reinsurance prices are currently trending downward and are expected to continue doing so, but they could increase in the event of unexpected climate catastrophes resulting in more than $100 billion worth of insured losses globally.[9]
These factors can lead to higher rates and instability in the insurance markets in certain states. For example, the six most expensive states for home insurance — Nebraska, Louisiana, Florida, Oklahoma, Kansas and Texas — all have a high exposure to hurricanes or tornadoes, which may be made stronger by warmer weather.[10] In addition, some insurers have scaled back or stopped offering coverage in wildfire-prone states, such as California and Colorado.
What Are Insurers Doing To Adapt to Climate Risk?
Perhaps the most straightforward way insurers have adapted to increasing climate risks is by implementing higher premiums or outright withdrawing from regions that have become too risky to profitably insure. That said, insurance carriers can also promote loss-prevention measures and take advantage of emerging technologies to help lower the odds of catastrophic losses that will lead to costly insurance claims.
Insurance companies often offer discounts to policyholders who take steps to lower their odds of experiencing severe property damage, such as removing fire hazards from their property or installing a hail-resistant roof. In some cases, insurance providers may even help fund home upgrades by paying into government-run grant programs, such as Strengthen Alabama Homes.[11]
Furthermore, insurers may leverage artificial intelligence systems to help identify potential risks in advance and show policyholders what steps they can take to prevent losses.[12] AI may also help bolster parametric insurance policies by analyzing climate models to predict severe heat events, connecting to satellite images to detect disasters in real time and instantly calculating and approving insurance settlements based on agreed-upon policy parameters.[13]
Rising Temperatures and Insurance at a Glance
- As climate change causes the world to get hotter, insurance policyholders may see a corresponding increase in their premiums, since high temperatures can lead to multiple kinds of losses that may be covered by insurance.
- In general, home and auto insurance cover sudden heat-related damage to your property, such as damage from wildfires, hurricanes and sudden cracking or warping. However, progressive heat-related damage that can be prevented through proper maintenance generally isn’t covered by insurance.
- Business owners may face a wide variety of covered claims due to rising temperatures, including liability lawsuits, property damage, business interruptions, food spoilage incidents and workplace illnesses or injuries.
- Extreme heat may raise health care costs by causing conditions like heatstroke or exacerbating conditions like cardiovascular disease. That said, health insurance differs from other types of insurance in that filing health insurance claims generally won’t cause your health insurance premiums to go up.
- Whenever reinsurance premiums rise or heat-related natural disasters become more common and powerful, property and casualty insurance companies may need to raise rates to offset their higher spending.
- Policyholders in states with a high exposure to heat-related natural disasters — such as California and Florida — can often expect to have a harder time finding affordable insurance coverage.
- Besides raising premiums or cutting coverage, insurance companies can respond to climate risks by promoting risk mitigation strategies and making use of AI or similar technologies to predict and prevent potential hazards.
How To Reduce Heat-Related Insurance Risks
To avoid higher insurance premiums and medical bills this summer, consider taking the risk management steps below to prepare for extreme heat and other climate-related risks.
Homeowners
Some of the steps you can take to help keep your home and your family safe from heat-related hazards include these:
- Keep your home cool: Examples of ways you can moderate the temperature inside your home include covering your windows with curtains or blinds, installing window reflectors that can keep heat out of your house and applying weather strips to the edges of your windows and doors.[14]
- Install home upgrades: Various types of home renovations can make your home more resistant to heat-related damage. For example, you could switch to wildfire-resistant roofing materials or install windows and doors that are designed to withstand flying objects carried by hurricane-force winds.[15][16]
- Plan for the long term: If your yard is large enough, a long-term strategy you could consider is planting trees to limit the amount of sunlight that reaches your home and reduce the urban heat island effect through a process known as evaporative cooling.[17]
- Take care of your health: To keep yourself safe from heat-related illness, be sure to stay hydrated, seek shade when outside and refrain from high-energy activities or outdoor work during the hottest parts of the day, if possible.[14]
Drivers
Drivers can protect against heat-related damage and injuries by taking the following actions:
- Maintain your vehicle: You can protect your vehicle from heat-related damage by regularly washing and waxing it, using seat covers and periodically testing your battery and checking your tire pressure. Also, make sure you check your car’s fluid levels, since heat may degrade your fluids — including coolant, motor oil and transmission fluid — or cause them to be consumed more quickly.[18]
- Keep your vehicle cool: Whenever you’re out and about during a heat wave, try to park your car in a shaded area to protect it from the sun — especially if you plan to drive again soon. If it’s safe to do so, consider leaving your windows slightly open to promote air flow and reduce interior heat. Of course, you’ll also want to make sure your air conditioning system is in working order before the peak of summer.
- Drive safely: Since extreme heat is associated with an increase in fatal car accidents, you need to be especially alert when driving through a heat wave. If you are exhausted after a long day of working outside, consider asking someone else for a ride home.
Businesses
To protect against costly legal claims and other losses, business owners need to implement the following safety measures:
- Require safety training: If your employees spend a lot of time on the road or working outside, make sure they undergo mandatory safety training in advance to help minimize the odds of commercial vehicle accidents or on-the-job illnesses.
- Check for signs of property damage: Since gradual damage generally isn’t covered by commercial property insurance, you need to be proactive about checking for signs of damage. As necessary, make minor repairs along the way to prevent more serious damage down the road.
- Monitor weather patterns: Keeping an eye on the weather forecast can help you plan appropriate commercial activities and be prepared in case a loss might occur and an insurance claim might be necessary. For example, specialty crop and livestock insurance policyholders need to be aware of the fact that plant and animal mortality are more common in extreme temperatures.[5]
- Insurance quotes /
- Rising Temperatures And Home Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Insurance Quote Online Now.
More on Insurance
Get a Free Insurance Quote.
Compare rates from dozens of companies in less than 3 minutes.