

Can I Deduct My Life Insurance Premiums on My Taxes?
 Written & Edited by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
In most cases, the premiums you pay for your life insurance policy are not tax deductible. However, there are a few situations where life insurance is tax deductible, such as if you are a business owner purchasing coverage for your employees or if you buy a policy that will pay someone outside of your family in the event that you die while the policy is active.
Read on to learn more about life insurance and taxes, including when life insurance premiums are tax deductible and what other life insurance tax benefits you may be able to take advantage of.
|
Key Takeaways
|
On This Page

Why Isn’t My Life Insurance Tax Deductible?
When Is Life Insurance Tax Deductible?
When Is Life Insurance Tax Deductible for a Business?
What Are the Tax Advantages of Life Insurance?
Do I Have To Pay Taxes on Life Insurance for the Accumulated Cash Value?
When Else Is It Required To Pay Taxes on Life Insurance?
FAQs

Why Isn’t My Life Insurance Tax Deductible?
The Internal Revenue Service (IRS) generally does not allow you to write off life insurance premiums on your taxes if you are the insured of the policy.[1] For example, if you have a standard life insurance policy that will pay out a death benefit to your spouse, children or other beneficiaries after you die, then you likely cannot deduct the amount you pay for that policy from your tax return.
When Is Life Insurance Tax Deductible?
Personal life insurance policies are only tax deductible in certain scenarios where someone outside of your immediate family is a beneficiary of the policy. For example, if you and your spouse divorced prior to 2019 and the terms of your alimony agreement have not changed since then, any premiums you pay for a life insurance policy that will pay out a death benefit to your ex-spouse after you die qualify as tax-deductible alimony.[2]
In addition, you may be able to write off money that you donate to a charity for the purchase of a life insurance policy. However, this deduction does not apply if the organization has to cover any of the premiums and you, a relative of yours or someone else you select is a beneficiary of the policy.[3]
When Is Life Insurance Tax Deductible for a Business?
Business owners are allowed to write off the premiums for life insurance policies they buy for their employees, as long as they are not directly or indirectly beneficiaries of the policy.[4] For example, you can deduct the payments for a burial insurance policy that covers your employees’ final expenses after they die, but you can’t deduct the payments for a key person insurance policy that pays out a death benefit to your business in the event of a certain executive’s death.
What Are the Tax Advantages of Life Insurance?
Unless you pay to become the beneficiary of a term life insurance policy, any life insurance proceeds you receive from that policy will not count as taxable income in most cases. Even in situations where you withdraw money from a permanent life insurance policy early, the majority of the payout will remain tax-free, and you won’t have to pay taxes on the taxable portion until after you have accessed it.[1][5]
Do I Have To Pay Taxes on Life Insurance for the Accumulated Cash Value?
If you are the beneficiary of a whole life insurance policy that will pay out the accumulated cash value along with the death benefit after the insured dies, then you likely won’t need to pay taxes on the cash value. However, you or the insured could have to pay taxes on some of the cash value if you withdraw it before the insured dies.
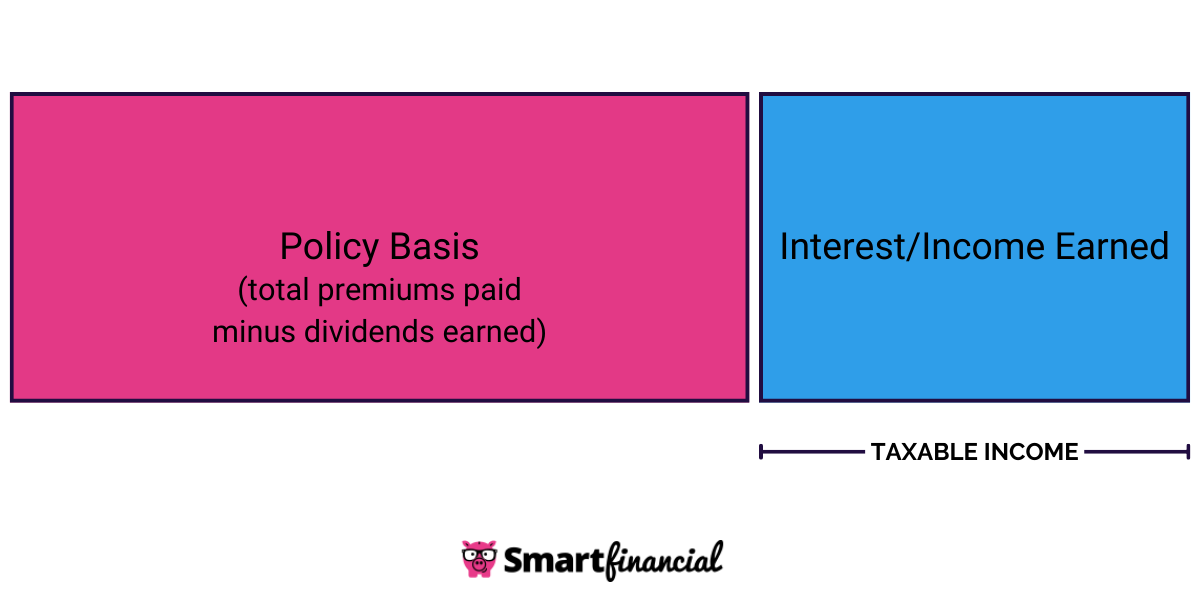
For example, if the covered individual opts to surrender their life insurance policy for cash, they could have to pay taxes on the payout if it is higher than the amount of money they paid into the policy through their premiums. Keep in mind that, in this scenario, only the amount of cash value that exceeds the amount of life insurance premiums paid is considered taxable income.[1]
When Else Is It Required To Pay Taxes on Life Insurance?
If your employer pays for you to have more than $50,000 worth of life insurance coverage, then you must subtract the cost of a policy with a $50,000 death benefit from the total amount your employer is spending on your policy and report the difference as taxable income on your federal tax return.[1]
Meanwhile, you are also required to pay taxes on your life insurance death benefit if it accrues interest. For example, if you are the beneficiary of a life insurance policy and the life insurance company pays you in installments after the insured dies, you must pay taxes on the amount of money you receive in any installment that is greater than the face value of the policy divided by the number of installments to be paid.[1]
- Insurance quotes /
- Life /
- Is Life Insurance Tax Deductible
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Life Insurance Quote Online Now.
More on Life Insurance
Looking for Life Insurance?
Compare rates from dozens of companies in less than 3 minutes.