

Life Insurance Shopping Guide: 9 Essential Steps To Find Your Perfect Policy
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
To shop for life insurance, you’ll need to evaluate your life insurance coverage requirements, compare quotes from multiple insurers to find a policy that provides the coverage you need at an appropriate cost and complete the application process — which may involve filling out a questionnaire and/or undergoing a medical examination, depending on the circumstances.
Read below to learn more about how to shop for life insurance, including tips that can help you decide when you should get life insurance and which coverage options may make the most sense for you.
|
Key Takeaways
|
On This Page

1. Determine Whether You Need Life Insurance
2. Decide How Much Life Insurance You Need
3. Know What To Look For When Shopping for Life Insurance
4. Learn What Types of Life Insurance Policies Are Available
5. Consider Whether You’ll Need Any Life Insurance Riders
6. Choose a Life Insurance Company
7. Fill Out the Application
8. Prepare for a Medical Exam (If Required)
9. Review and Purchase Your Life Insurance Policy
FAQs

1. Determine Whether You Need Life Insurance
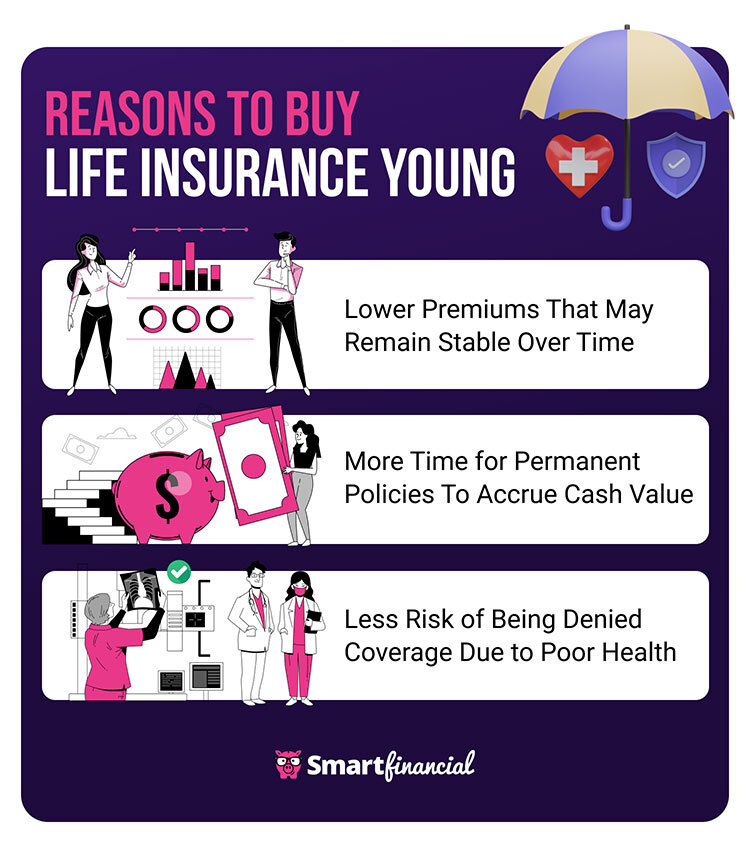
Before you start life insurance shopping, you’ll naturally have to determine whether you actually need life insurance. In general, life insurance is a worthwhile investment if you have — or ever expect to have — dependents relying on your income. Keep in mind that age and health status are among the primary factors influencing life insurance premiums, so it’s best to buy a policy while you are young and healthy to lock in the lowest rate possible.[1]
That said, not everyone needs life insurance. If you don’t have a spouse or children and don’t plan on ever starting a family, you can likely afford to go without coverage. In addition, wealthy individuals may not need life insurance, since they may already have enough money saved up to provide ongoing financial security for their dependents after they die.
2. Decide How Much Life Insurance You Need
The next step is to decide how big of a death benefit you’d like your life insurance policy to provide. According to some experts, a working adult should buy a policy with a death benefit between 10 and 30 times their current annual income, depending on their age — but your needs may ultimately differ based on your circumstances.[2] Consider how many beneficiaries you want to support and what expenses you want to help them cover after your death.
For example, you may opt for a larger death benefit if you want to use your policy to leave an inheritance for your children, help them pay off their student loans or grant a final donation to your favorite charity. Conversely, a smaller death benefit may suffice if you simply want to help your loved ones pay for your final expenses, like your funeral and burial.
3. Know What To Look For When Shopping for Life Insurance
While premiums and coverage limits are generally the most important things to look for in a life insurance policy, there are other factors worth paying attention to. For example, if you want to provide your beneficiaries with a steady stream of money to mimic your paycheck, you could look for a policy that pays out the death benefit in installments rather than as a lump sum.
Also, be sure to check whether the policy you are interested in comes with any restrictions. For example, many policies come with a two-year contestability period, during which claims may be denied if the insurer discovers any inaccurate information in your application. Meanwhile, some life insurance carriers may refuse to pay out a death benefit if you die by suicide within a year or two of purchasing your policy — though they may refund any premiums paid.[3]
4. Learn What Types of Life Insurance Policies Are Available
There are several different types of life insurance to choose from, so it’s worth weighing the pros and cons of each to see which type of coverage may be the best fit for your situation.
Term Life Insurance
Term life insurance provides coverage for a limited window of time — usually ranging from one to 30 years.[4] It tends to be cheaper than other types of life insurance because there is no guarantee that you will die during the coverage period, meaning your insurance company may be able to collect premiums from you without ever having to pay out a death benefit.
Term life coverage is generally the most affordable option if you simply want to make sure certain expenses are covered for your beneficiaries during a specific time frame. For example, you could buy a 30-year policy to last through the end of your mortgage so your spouse can pay it off after you die. Alternatively, you could get a 20-year policy at age 45 to effectively replace your income for your dependents in case you die before retirement.
Permanent Life Insurance
As its name suggests, permanent life insurance generally provides coverage for your entire life. Since it is nearly guaranteed that your insurer will have to pay a death benefit at some point, permanent life insurance typically costs more than term life insurance. Additionally, these policies accumulate cash value that you may be able to withdraw, borrow, put toward premium payments or use to raise the death benefit, depending on the details of the policy.[5]
The most common type of permanent life insurance is whole life insurance, which has stable premiums and earns cash value at a set rate.[7] Another option is universal life insurance, which allows you to adjust your premiums and death benefits over time. If you buy a traditional universal life insurance policy, you will accrue cash value at a fixed rate.[8]
Conversely, indexed universal life insurance earns interest at a fluctuating rate based on the performance of a stock market index — though part of the cash value remains in a standard account, limiting how much the policy can gain or lose. Finally, variable universal life insurance is a high-risk, high-reward option with no ceiling on how much money you can gain and no floor on how much money you can lose based on the performance of your underlying investments.[8]
Supplemental Life Insurance
Supplemental life insurance refers to a secondary policy for someone whose work-based life insurance doesn’t offer a high enough death benefit. About 60% of civilian workers in the United States receive life insurance coverage through their employer.[9] Nevertheless, these group policies typically only offer around $50,000 to $100,000 worth of coverage, which likely won’t be enough to provide long-term financial support for your dependents after you die.[2]
No-Exam Life Insurance
No-exam life insurance refers to a policy you can obtain without having to undergo a medical examination as part of the underwriting process. This type of policy may be ideal if you need to secure coverage quickly or if you have health conditions that may otherwise disqualify you from receiving coverage. However, no-exam life insurance policies generally provide low death benefits at a high price.
One example of no-exam coverage is simplified issue life insurance, which replaces the medical exam with a nonintrusive questionnaire. Another method is accelerated underwriting, which calculates your premiums by using an algorithm to analyze digital health data, such as your medical records. Finally, you can be approved for guaranteed issue life insurance regardless of your health status — potentially making it the only option for people in poor health.[10]

5. Consider Whether You’ll Need Any Life Insurance Riders
Many life insurance companies offer riders you can add to your policy to enhance your coverage in exchange for paying a higher premium. See the table below for examples of common life insurance riders.[11]
|
Rider Name |
Rider Description |
|---|---|
|
Return of premium |
Refunds some or all of the premiums you paid if you survive to the end of your term life insurance policy’s coverage period |
|
Term conversion |
Lets you convert your term life insurance policy into a whole life insurance policy at the end of the term without undergoing a second medical underwriting process |
|
Living or accelerated death benefit |
Allows you to claim a portion of your death benefit before dying if you develop a terminal illness — in exchange for lowering your beneficiaries’ death benefit after you die |
|
Critical illness |
Functions similarly to an accelerated death benefit rider but may apply for certain nonterminal illnesses, such as kidney failure or stroke |
|
Waiver of premium |
Exempts you from paying your life insurance premiums if you develop a debilitating disability |
|
Provides an extra payout if you die in an accident or survive an accident that causes you to lose a limb |
|
|
Child or spouse |
Adds limited coverage for your family members without requiring you to buy separate policies for them |
|
Guaranteed insurability |
Enables you to raise your death benefit at certain points during your policy’s coverage period — like when you get married or have a child — without undergoing another underwriting process |
|
Family income benefit |
Issues the life insurance payout as a steady income flow to your beneficiaries over a set number of years determined by you |
|
Allows you to subtract money from your policy’s death benefit and put it toward your long-term care expenses if you become unable to carry out basic daily living activities on your own |
|
|
Charitable giving |
Donates a percentage of your policy’s face value to a qualified charity after you die without subtracting from your beneficiaries’ death benefit |
|
Term insurance |
Adds temporary life insurance coverage on top of your existing permanent life insurance coverage |
|
Yearly renewable term |
Function similarly to a term insurance rider but requires you to renew your term coverage annually, meaning your premiums may increase as you get older |
|
Automatic premium loan provision |
Automatically uses cash value to cover your premium if you miss a payment |
|
Transfer of insured |
Changes the person covered by a commercial key employee life insurance policy if the previous insured leaves the company |
6. Choose a Life Insurance Company
Before settling on a life insurance policy, it can be helpful to research the financial strength and customer satisfaction ratings of various insurance companies to help you decide which insurer to choose. Also, check for special promotions or discounts you may be eligible for. For example, Protective Life offers lower rates to Costco members, while American Family policyholders may save on home and auto coverage by bundling them with life insurance.[12][13]
7. Fill Out the Application
Upon finding an appropriate policy, you may be able to apply for life insurance online. Be prepared to share personal details, like your name and contact information. The insurer may also request information it can use to calculate your life insurance rates, such as your age, gender, height, weight, health status and family medical history — along with information about your lifestyle, such as whether you smoke or have any dangerous hobbies, like extreme sports.
During the application process, you may need to indicate how much coverage you want, designate your beneficiaries and provide their contact information. In some cases, you may have the option to send in an initial life insurance premium payment to secure temporary coverage in case you die between submitting the application and being approved for a policy — though you may still have to meet preliminary underwriting requirements to qualify.[3]
8. Prepare for a Medical Exam (If Required)
Unless you apply for a no-exam policy, you’ll have to undergo a medical examination before being approved for life insurance. Life insurance exams typically last 15 to 45 minutes, and the medical examiner may come to your home or office to conduct the exam. Generally, you’ll need to fill out a questionnaire, and the examiner will perform a physical — they may also require an electrocardiogram, lab work, X-rays or other tests, depending on your circumstances.[14]
9. Review and Purchase Your Life Insurance Policy
Once you’ve settled on the right policy, you can activate it by paying your first premium. Depending on your state and insurer, you may be eligible for a free look period, during which you can cancel your policy and receive a refund with no penalty. For example, life insurance companies in North Carolina must offer you a free look period lasting at least 10 days for new policies and at least 30 days for replacement policies.[15]
If you need help finding coverage, consider shopping around for free through SmartFinancial. Simply fill out our online questionnaire about your coverage needs and budget, and we’ll connect you with a life insurance agent who can help you compare policies from multiple insurance carriers. Get started on comparing life insurance quotes now!
- Insurance quotes /
- Life /
- How To Shop For Life Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Life Insurance Quote Online Now.
More on Life Insurance
Looking for Life Insurance?
Compare rates from dozens of companies in less than 3 minutes.