

What Is a Life Insurance Premium?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
A life insurance premium is the regular payment you must make to maintain your life insurance coverage — often monthly or annually, though other payment options may be available. Insurance companies generally consider factors like your age, sex, medical history, type of coverage and more when calculating the cost of your life insurance policy.
Read below for more information about the types of life insurance premiums and how you can find the most affordable life insurance policy available.
|
Key Takeaways
|


How Do Life Insurance Premiums Work?
Your life insurance premium refers to the amount of money you have to pay to purchase and maintain life insurance. You may be able to make payments on a monthly, quarterly, semiannual or annual basis, depending on your insurance company and the details of your policy. In some cases, you may even be able to cover the entire cost of the policy with an upfront, lump-sum payment.[1]
Continually paying your premiums ensures that your insurance provider will pay out an agreed-upon sum of money — known as a death benefit — to your beneficiaries if you die during the coverage period. Conversely, if you fail to pay your premiums, your coverage may be canceled. That said, many policies come with a one-month grace period, during which you can make up your missed payment without forfeiting your policy.[2]
How Is a Life Insurance Premium Calculated?
In general, insurance companies set the price of your life insurance by determining how likely it is that you will die and require a death benefit payout while the policy is active. Some of the factors that are frequently used to calculate life insurance premiums include the following:[3]
- Age: The older you are when you take out a life insurance policy, the more expensive it will be, since you will be more likely to die during the life insurance coverage period. Young people may also qualify for cheaper premiums because they are expected to live longer and make more payments than their older counterparts.
- Medical history: If you have a preexisting condition with a high mortality rate — such as heart disease or diabetes — you will likely have to pay more for life insurance than someone with no prior medical issues. Even if you are in good health, you may have to pay more if your family has a history of experiencing terminal illnesses, like cancer.
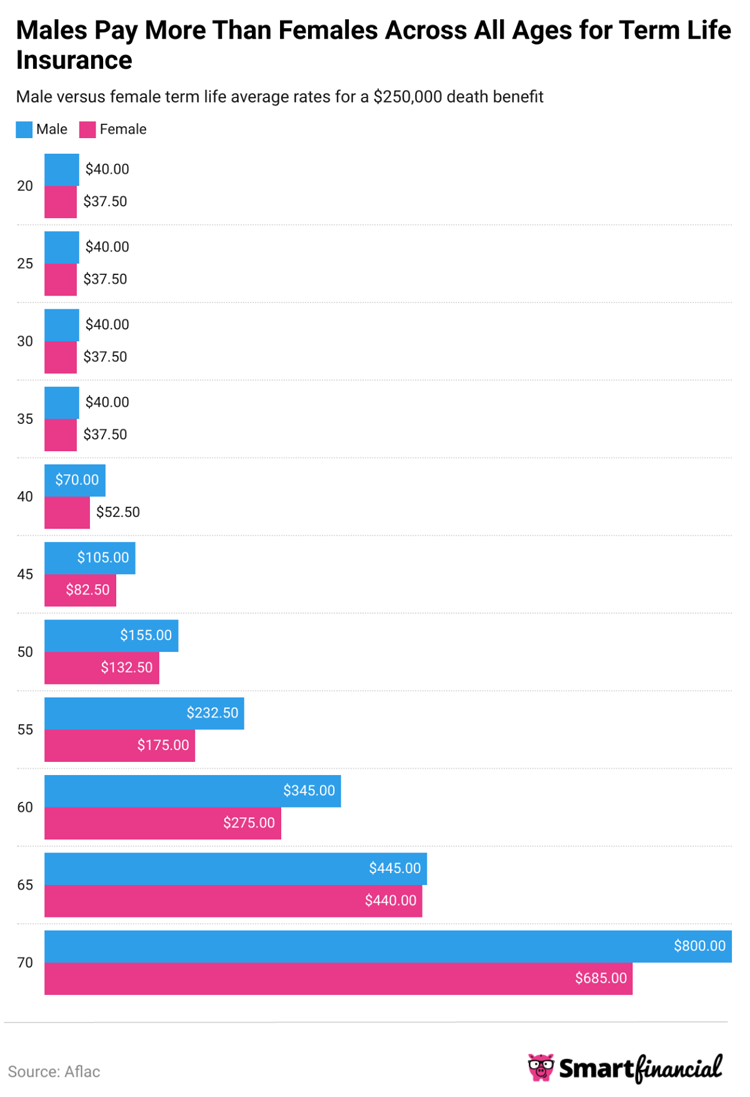
- Sex: Women live longer than men on average, so they are often charged less for life insurance.
- Occupation: You may have to pay more for life insurance if you have a high risk of dying due to an on-the-job accident. For example, a construction worker will likely have a higher premium than someone with a desk job.
- Lifestyle: If you regularly use tobacco or have a dangerous hobby — like skydiving — you can expect to pay more for life insurance because your lifestyle increases the risk that you will die early. Likewise, you may face higher rates if you have a poor driving record.
- Policy details: Various coverage specifics can influence the cost of your life insurance policy, such as the length of your coverage period and whether your policy offers any extra benefits.
Underwriting Methods
The cost of your life insurance also depends on whether you must undergo a medical exam as part of the underwriting process — which refers to an insurance company’s method for assessing the risk associated with insuring you. Below is an overview of the three main underwriting methods and how they could impact your life insurance rates.[4]
|
Method |
Description |
Pros |
Cons |
|---|---|---|---|
|
Full underwriting |
Uses a detailed, in-person medical examination to evaluate your risk |
Can lead to lower rates if you have a healthy lifestyle and no history of serious health issues |
Can lead to higher rates if you have an unhealthy lifestyle or a history of serious health issues |
|
Simplified issue |
Assesses your risk using a health questionnaire and potentially other external resources, such as prescription databases, medical records or motor vehicle records |
Allows for a quicker application and approval process and avoids the risk of a medical exam uncovering an underlying health issue that could raise your rates |
Generally results in higher rates and lower coverage limits than full underwriting because it gives your insurer less detailed information |
|
Provides life insurance coverage at a set rate without evaluating your risk |
May be the cheapest (or only) option you qualify for if you are very old or have serious health issues |
Typically offers the smallest death benefits and will likely cost more than full underwriting if you are healthy |
Types of Life Insurance Policies
The type of life insurance policy you select will also influence your premium costs. Policyholders typically choose between two categories of coverage: term life insurance and permanent life insurance.
Term Life Insurance
Term life insurance policies only last for a limited amount of time — usually between one and 30 years. At the end of the term, your coverage will expire, and your beneficiaries will no longer be eligible for a payout after your death. Term life insurance is generally cheaper than permanent life insurance, in large part because there is no guarantee that your insurance company will have to pay out a death benefit before your policy ends.[5]
You may be able to choose between two main types of term life insurance: level and decreasing. If you opt for level term life insurance, the potential death benefit will remain the same throughout the duration of the coverage period. But, if you purchase decreasing term life insurance, the potential payout will get lower over the course of the term — with the coverage limit usually dropping once per year.[5]
A term life insurance policy may be beneficial if you are a younger person who wants to ensure your family has financial support and can pay off any outstanding debts in case you die suddenly. For example, if you make $50,000 a year, you could purchase a 10-year policy with $500,000 in coverage, enabling your loved ones to effectively receive your income for the next decade, even if you die before then.
Whole Life Insurance
The most common type of permanent life insurance coverage is whole life insurance.[6] As its name suggests, whole life insurance generally provides coverage for your entire life as long as you continue to pay your premiums. That said, some whole life policies set maturity dates, at which point you may directly receive a payout from your insurer if you are still alive.[7]
Whole life insurance can be especially beneficial for older people who want to help their relatives cover their funeral expenses after they die without having to worry about the policy expiring and their beneficiaries missing out on a death benefit. Keep in mind that whole life insurance costs more than term life insurance, since it is essentially guaranteed that the insurer will have to pay out the policy’s death benefit at some point.[5]
Additionally, whole life policies can be expensive due to other benefits they offer, such as the cash value they accrue over time. This extra money is stored in a savings account that you may be able to access while you are still alive. For example, you could withdraw your policy’s cash value outright or take out a loan against it by lowering or completely forfeiting your beneficiaries’ potential death benefit.[5]
Universal Life Insurance
Universal life insurance is another type of permanent life coverage that offers more flexibility than whole life insurance, allowing you to raise or lower your premiums and death benefits over time as you see fit. Below are examples of common types of universal life insurance and how they accumulate cash value:[8]
- Guaranteed universal life insurance: This type of policy accrues cash value at a set rate, meaning it experiences guaranteed growth but doesn’t have as much growth potential as other kinds of universal life insurance.
- Indexed universal life insurance: These policies earn interest based on the performance of a stock market index, like the S&P 500. An indexed universal life insurance policy may set a cap on the amount of cash value you can accrue, but it may also come with an interest rate floor to ensure you don’t lose cash value.
- Variable universal life insurance: A variable universal life insurance policy can grow cash value based on a number of investment options. While this type of coverage has the greatest potential for growth, it is also possible to lose cash value with a variable universal life insurance policy.
Life Insurance Premium Examples
Life insurance premiums can vary considerably based on a person’s circumstances. For example, a healthy 35-year-old woman in North Carolina may pay around $20 per month for a 10-year term life insurance policy with a $1 million death benefit.[9] Meanwhile, a 65-year-old California man in poor health may have to pay upwards of $90 per month for a whole life insurance policy with a $10,000 death benefit.[10]
See the following infographic for a detailed breakdown of how average term life insurance rates differ by age and sex.[11]
How To Reduce Your Life Insurance Premium
One simple way to pay less for coverage is to get life insurance sooner rather than later. While many policies offer rates that don’t increase over time, those initial rates will generally be lower for a younger buyer than for an older one. Healthier people also tend to pay less for life insurance, so you may be able to secure a cheaper premium by improving your diet and establishing an exercise routine before purchasing your policy.
Another way to save money is to reduce your coverage amounts or change the type of life insurance you purchase. In general, a term life insurance policy with a low death benefit will be much cheaper than a whole life insurance policy with a high death benefit, so it’s important to evaluate how much coverage you actually need and which policy can provide the best value for your budget.
Finally, you need to compare quotes from multiple life insurance companies, since each insurer has its own method for calculating premiums and one carrier may offer you a more favorable rate than another for the same coverage. If you shop through SmartFinancial, we’ll help you compare life insurance quotes for free after you complete a simple questionnaire. Click here to enter your ZIP code and get started on comparing life insurance quotes online!
- Insurance quotes /
- Life /
- Life Insurance Premiums
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Life Insurance Quote Online Now.
More on Life Insurance
Looking for Life Insurance?
Compare rates from dozens of companies in less than 3 minutes.