

Is My Life Insurance Policy Taxable?
 Written & Edited by Dan Marticio Dan MarticioDan Marticio is the content manager at SmartFinancial and has written 150+ articles across multiple insurance verticals.... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Generally, a life insurance death benefit is not taxable, but there are a few exceptions, especially if you have a permanent life policy. Any income you or your beneficiary receive above the total premiums you’ve paid — usually from interest earned or the sale or surrender of the policy — can be considered taxable income. Additionally, taxes may apply if you designate your estate as the beneficiary.
In this article, we will list taxable scenarios related to life insurance plus examples.
|
Key Takeaways
|


When Is Life Insurance Taxable?
In most cases, the IRS does not classify the death benefit from a life insurance policy as taxable gross income, and the beneficiary will not need to report it on their annual tax return.[1]
However, there are some situations when the payout may be subject to taxes, especially if you have a permanent life policy, like whole life insurance, that earns interest. Specifically, you must look at the policy basis — your total premiums minus dividends earned. Not including the death benefit, the IRS considers any income earned above the policy basis as taxable income. Additionally, listing your estate as the beneficiary can create a taxable event.
Unlike the death benefit, you will have to count any premiums that you pay toward your life insurance policy as taxable income. The IRS classifies these payments as personal expenses, similar to paying for rent and utilities.[2] However, there are some exceptions, and these will usually involve being a business owner or donating to a charity.
When Do You Pay Taxes on Life Insurance?
Beneficiaries may owe taxes on their life insurance payout depending on how the death benefit payout was structured and on any income earned above the policy basis. Additionally, taxes may apply if the death benefit is made payable to the insured’s estate.
Beneficiary Chooses Installment Payments
If the beneficiary chooses to receive the death benefit in installments instead of a single lump sum, it can create a taxable event. The beneficiary will need to report a part of each installment but can exclude a portion. To calculate how much you can exclude from your taxable income, divide the total lump sum by the number of installments. Any amount that is higher than this calculation is considered interest and must be reported as taxable income.[3]
Example calculation: The death benefit is $100,000, and the beneficiary chooses to receive 100 monthly installments of $1,200. To calculate the amount that is excludable from income, divide $100,000 by 100, which equals $1,000. The remaining $200 each month ($1,200-$1,000) is taxable income and must be reported as interest income. Over 12 months, this would be $2,400 that should be reported on the beneficiary’s income tax return.
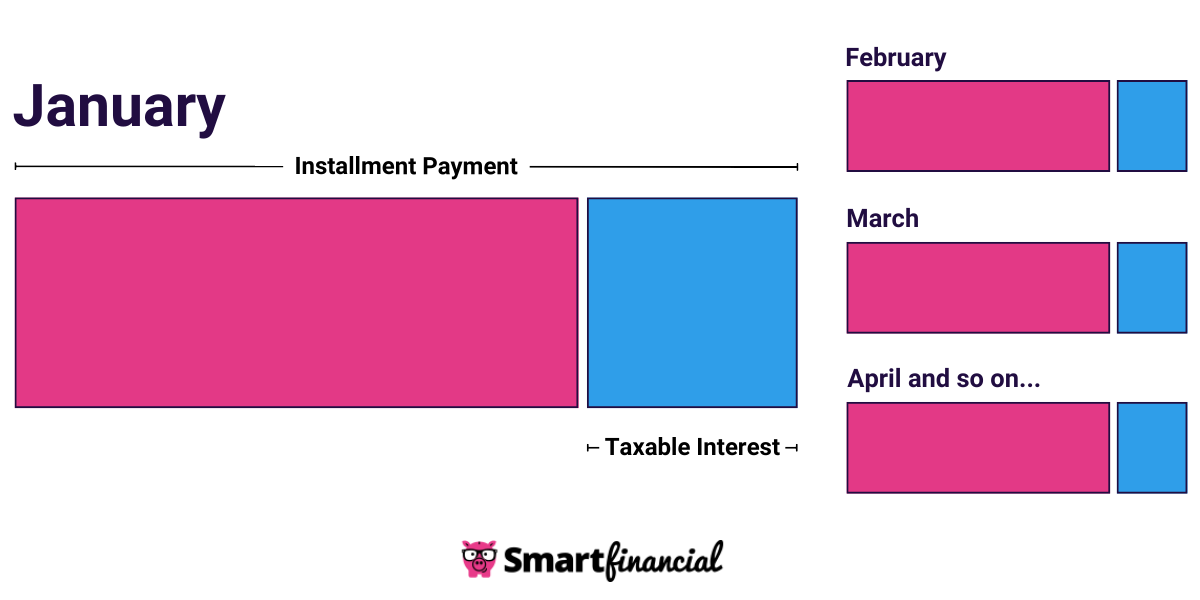
If you are a surviving spouse receiving life insurance proceeds from a spouse who died before Oct. 23, 1986, you can exclude up to $1,000 a year from the interest income mentioned above, even if you remarry.[3] Using the earlier example, the beneficiary would only have to pay taxes on $1,400 ($2,400-$1,000) of the interest income.
Interest Accrued on Delayed Death Benefit
If the beneficiary waits to receive the death benefit instead of receiving it promptly after the insured’s death, then any interest the death benefit earned is generally subject to taxation. Keep in mind the taxes are only levied on the interest, not on the entire benefit amount.
Example: James is entitled to a death benefit of $750,000 and waits one year before he decides to receive it. Over one year, it earned 5% interest which increased the amount to $787,500. As a result, James must pay taxes on the $37,500 growth and not the $750,000 death benefit.
You Take Out a Cash Value Loan
You can borrow from your life insurance policy through cash-value loans, and the borrowed amount is not taxable if you repay it. However, failing to repay the loan can create a taxable event for any amount that exceeds the policy basis.
Example: Ryan’s life insurance policy has $8,000 in cash value, and the policy basis is $3,000. Ryan borrows $7,000 from the policy. However, Ryan falls behind on his premium payments and does not repay the loan, so his life insurer cancels the policy. As a result, Ryan must report the $4,000 as taxable income on his income tax return.
You Surrender the Policy for the Cash Value
Surrendering the policy means canceling the policy to withdraw the accrued cash value. Any amount that exceeds the policy basis is taxable income. That means if the amount you withdraw is over the total premiums you paid minus dividends or unrepaid loans, then the difference must be reported on your income tax return.[3]
Example: Sarah has a variable life insurance policy that has accumulated $15,000 in cash value, and she has paid $10,000 in premiums over the years. Sarah decides to surrender the policy for the cash value. As a result, she would have to pay taxes on the $5,000 difference because it exceeds the basis of $10,000.
You Sell the Policy
When selling a life insurance policy, the seller should be aware that taxes can apply to the proceeds received. Proceeds in excess of the policy basis up to the cash surrender value of the policy are taxed as ordinary income. Any remaining proceeds are taxed as capital gains.[4]
To estimate the amount taxed as ordinary income, subtract the total premium paid from the policy's cash value. So, if the policy basis was $25,000 and the cash value amount was $30,000, then $5,000 would be taxed as ordinary income.
Next, to find the capital gains tax portion, subtract the total premium plus the portion taxable as ordinary income from the amount the policy sold for. So, if the policy was sold for $40,000, then the amount taxable at the capital gains rate would be $10,000 ($40,000-$25,000-$5,000).
Your Estate is the Beneficiary
If you choose your estate as your beneficiary, then it may be subject to an estate administration tax. Listing “payable to my estate” as your primary beneficiary means the death benefit can go through probate court, and it may even be used to pay outstanding debts. Whatever is left (if anything) will go to your loved ones.[5]
Is Life Insurance Tax Deductible?
Below we will discuss the tax implications on various types of life insurance policies.
Is Term Life Insurance Taxable?
The death benefit in a term life insurance policy is usually not taxable so long as your beneficiary is your spouse or adult child. If your estate is currently listed as your beneficiary, you should take steps to update it to a specific individual as soon as possible.[6]
Is Whole Life Insurance Taxable?
Similar to term life, the death benefit of a whole life insurance policy is generally not taxable if an actual individual is listed as the beneficiary. However, its cash value component can have tax implications.
If you borrow against the cash value and don’t repay it or if you surrender the policy to cash it out, any portion that exceeds the policy basis is subject to taxes.
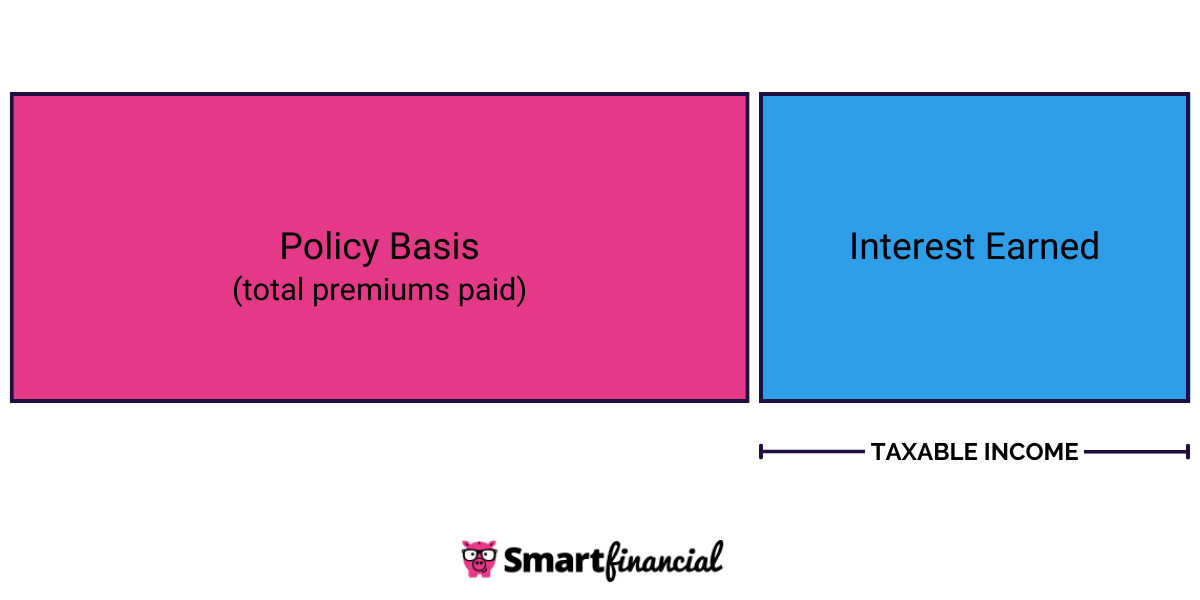
This applies to other types of life insurance with lifelong coverage like universal or variable life policy. You should consider this added complexity when choosing if life insurance is right for you.
Is Employer-Paid Group Life Insurance Taxable?
An employee will not have to pay taxes if employer-provided life insurance coverage is $50,000 or lower. If the coverage is higher than $50,000, then taxes will apply on the premiums paid to purchase coverage in excess of that $50,000 threshold.[7]
Are Life Insurance Dividends Taxable?
Life insurance dividends are usually not taxable as long as they are not greater than the premiums you have paid into the policy. In fact, the IRS considers dividends as a return on your premium and instructs policyholders to subtract dividends from their total premiums when calculating their policy basis.[3] However, if, over the years, the total dividends earned somehow exceed the total premium paid, then the difference would be subject to taxes.
Are Accelerated Death Benefits or Viatical Settlements Taxable?
An accelerated death benefit is a rider that allows the insured to receive their life insurance money while they are still living. A viatical settlement, on the other hand, involves the sale of a life insurance contract to a third party.
In either case, the insured often suffers from a chronic or terminal illness and needs the death benefit or sale proceeds to pay for costly hospital and medical treatment. If the insured has a terminal illness, then the payout is generally tax-free. However, a limit can apply if the insured has a chronic illness that is not terminal.[3]
Are There Ways To Avoid Paying Taxes on Life Insurance?
Not including the death benefit, the beneficiary usually has to pay taxes on any income earned that exceeds the policy basis. However, there are ways to avoid estate-related taxes, and that usually starts with designating your spouse as the beneficiary.
However, estate taxes may still apply if the value of your assets exceeds a certain amount set by your state. If you suspect your life insurance payout will be subject to estate administration taxes, talk to an attorney about setting up an irrevocable life insurance trust (ILIT), which can help you avoid such taxes.[8]
- Insurance quotes /
- Life /
- Is Life Insurance Taxable
Dan Marticio is the content manager at SmartFinancial and has written 150+ articles across multiple insurance verticals. His past experience writing in small business and personal finance verticals has earned him bylines on prominent fintech brands, including LendingTree, ValuePenguin, Fundera, The Balance and NerdWallet. His guides always aim to assist everyday consumers and entrepreneurs make informed decisions about their finances and business.


Get a Free Life Insurance Quote Online Now.
More on Life Insurance
Looking for Life Insurance?
Compare rates from dozens of companies in less than 3 minutes.