

The 10 Most Expensive Cars To Insure
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
The most expensive cars to insure are generally luxury models, such as the BMW i7, Bentley Continental GT and Mercedes-Benz EQS. That said, the cost of car insurance also depends on your personal characteristics and coverage details, and you may be able to mitigate high insurance costs by shopping around, practicing safe driving habits and looking into discount opportunities.
Keep reading to learn about the top 10 most expensive cars for insurance and the types of vehicles that tend to require higher auto insurance premiums.
|
Key Takeaways
|


What Are the Most Expensive Cars To Insure?
The most expensive car to insure is the BMW i7, with an average full coverage car insurance rate of $8,665 per year for a sample population of 40-year-olds with good driving records who have good credit and drive 13,000 miles per year.[1] In comparison, the national average cost of full coverage across all vehicles and drivers is only $2,697 per year as of November 2025.[2]
See below for an overview of the top 10 luxury models with the highest insurance prices:[1]
|
Make and Model |
Average Annual Car Insurance Premium |
|---|---|
|
BMW i7 |
$8,665 |
|
$7,580 |
|
|
Mercedes-Benz EQS |
$7,295 |
|
BMW 760 |
$7,053 |
|
BMW XM |
$6,877 |
|
$6,719 |
|
|
Aston Martin DB12 |
$6,627 |
|
BMW M8 Cabriolet |
$6,397 |
|
$6,383 |
|
|
Aston Martin DBX |
$6,342 |

What Types of Cars Are the Most Expensive To Insure?
A car’s make and model are significant factors in determining the cost of auto coverage, and certain types of vehicles tend to be more expensive to insure than others as a result. Read the following sections for more information on which categories of cars usually carry high car insurance premiums and why.
Luxury Vehicles
Luxury vehicles tend to be expensive to insure because of how valuable they are. In general, the higher your car’s actual cash value is, the more your car insurance company will have to pay you after a total loss. As a result, insurers generally charge high premiums for luxury cars to account for the risk that they will have to pay out a large sum of money in the event that your vehicle is declared a total loss.
Furthermore, luxury cars often come with advanced technology and premium parts, which are especially costly to repair or replace. Additionally, highly valuable luxury vehicles are more likely to be stolen, meaning your insurance carrier may charge you more because of the increased risk that you will need to file a comprehensive insurance claim due to theft.[3]
Sports Cars
Sports cars may require high car insurance premiums due to how they are used. These high-performance vehicles are often designed to travel at high speeds, which may promote speeding and other high-risk behaviors. For this reason, sports car drivers may be more likely to receive traffic tickets or get into car accidents that result in serious property damage, bodily injury or even death — necessitating higher insurance rates to offset that risk.[3]
Exotic Cars
Exotic cars are often customized with unique parts that may be expensive to replace in the event that the vehicle is damaged — especially if those parts must be imported from a foreign country. In addition, exotic automakers may only produce a limited volume of specific models, raising the value of each vehicle and thereby driving up the price of auto insurance.[4]
Cars With Modifications
Performance upgrades, custom paint jobs, sound system enhancements and other modifications can be expensive to replace, so vehicles that have them can be expensive to insure — especially considering your insurance company may not provide coverage for those modifications unless you purchase an extra custom parts and equipment endorsement for your auto insurance policy.[5]
EVs
Because of their customized batteries and other high-tech parts, electric vehicles may need to be repaired by specialized technicians after an accident, which may lead to higher repair costs and — correspondingly — higher insurance bills. That said, some insurers offer eco-friendly discounts to drivers of EVs and hybrids, which may help mitigate their high base premiums.[3]
What Makes a Car Expensive To Insure?
Some of the main factors that can make a car more expensive to insure are high repair and replacement costs, since these are the expenses your insurer has to cover if you get into an accident that damages or destroys your vehicle. That said, high-value cars may avoid sky-high insurance premiums if they come with advanced safety features that lower the odds of a costly insurance claim, such as blind spot detection or automatic emergency brakes.[6]
Your car insurance premiums also depend on other factors, including the following:[7]
- Driving record: Drivers with a history of safe driving are generally considered less likely to get into accidents and file insurance claims, so they get to pay less for coverage.
- Usage: The more mileage you put on your car, the more you can expect to pay for car insurance coverage. For example, someone who works from home will generally have a lower premium than someone with an extensive commute.
- Location: Various regional characteristics can influence your car insurance costs, such as the rates of accidents, thefts and uninsured drivers in your area, along with local medical and repair costs, insurance fraud prevalence and weather patterns.
- Age: Teenagers pay the most for auto insurance because they have the least driving experience and the highest accident rate of all age groups. Meanwhile, adults over the age of 25 tend to pay lower premiums.
- Gender: On average, women are charged less for auto insurance than men because they are statistically less likely to get into serious car accidents or commit DUI violations.
- Credit score: Individuals with poor credit tend to be more likely to file claims, so insurers may use a credit-based insurance score to calculate your car insurance prices.
- Vehicle characteristics: Insurance companies may also consider details about your car other than its repair or replacement costs, including the model’s safety record and the amount of damage it will likely inflict on another vehicle in the event of a collision.
- Policy details: Your policy’s coverage specifics — such as the coverage types, coverage limits and deductibles you select — will also influence the cost of the policy.
How Do I Get Low Rates on Car Insurance?
Taking steps like these can help you save money on car insurance:
- Consistently follow traffic laws and practice safe driving habits to maintain a clean driving record.
- Ask your insurance company about car insurance discounts you may qualify for, such as good student, bundling or military discounts.
- Maintain continuous car insurance coverage, since your rates will often go up after a coverage lapse.
- If you rarely drive, join a pay-per-mile car insurance or usage-based telematics program.
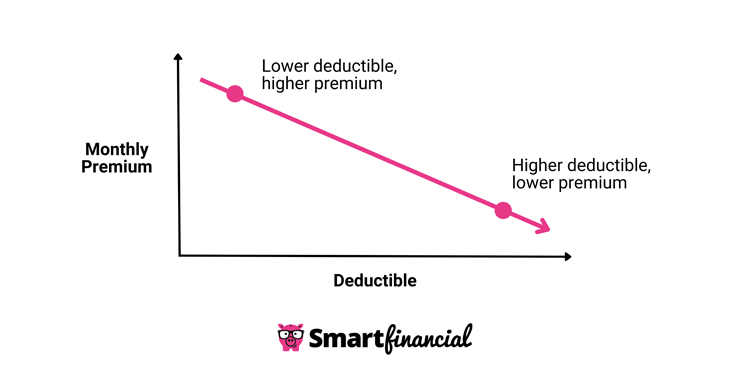
- Raise your deductible — as long as you have enough money in savings to cover the deductible you choose.
In addition, it’s important to shop around to make sure you’re getting the best possible deal on the coverage you need. After you fill out a brief questionnaire, SmartFinancial can help you compare rates from reliable car insurance companies in as little as a few minutes. Click here to type in your ZIP code and begin comparing auto insurance quotes for free!
- Insurance quotes /
- Auto /
- Most Expensive Cars To Insure
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Auto Insurance Quote Online Now.
More on Auto Insurance

Looking for Auto Insurance?
Compare rates from dozens of companies in less than 3 minutes.