

Tiny Home Insurance Requirements and Costs
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Tiny homes are an excellent way to find affordable housing for people with minimalist space needs or those who prefer to live off-grid, but they may have insurance requirements depending on how the tiny home is classified or whether it’s financed. However, tiny homes are often much cheaper to purchase than standard single-family homes, making them an affordable option for first-time homebuyers.
Keep reading to learn more about what tiny homes are, whether you’ll need tiny home insurance, and what potential costs look like.
|
Key Takeaways
|


What Is a Tiny Home?
A tiny home is a smaller dwelling, typically measuring between 100 and 500 square feet, although some areas may limit them to a maximum of 400 square feet.[1] Compared to the size of an average single-family home — approximately 2,146 square feet — tiny homes provide people who want to downsize or live a minimalist lifestyle with a more affordable and sustainable housing option.[2] Some tiny homes include utilities such as plumbing or heating, while others may reduce space to a single large room without amenities.
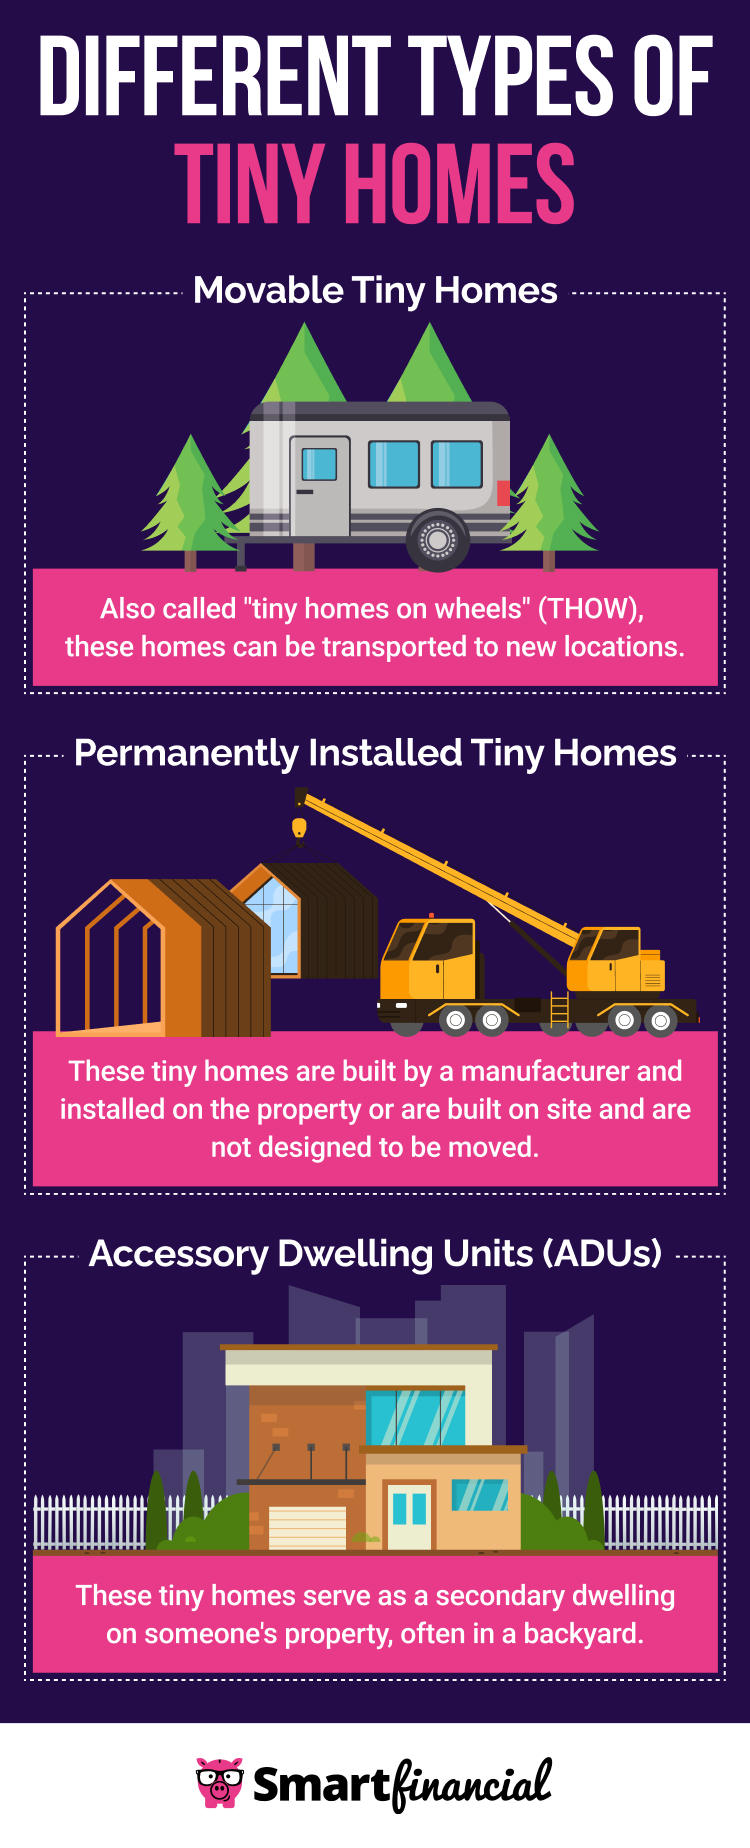
Tiny homes come in a variety of designs:[3]
- Movable Tiny Homes: Sometimes referred to as tiny homes on wheels (THOW), these homes are constructed from a trailer or RV and can be easily moved or driven to new locations. They’re often classified as park model RVs, which can affect their insurance requirements.
- Permanently Installed Tiny Homes: These types of tiny homes are built on a permanent foundation and can’t be moved — similar to a traditional house or condo. They may be built by a manufacturer and installed on-site or constructed directly at the location.
- Accessory Dwelling Units (ADUs): ADUs are classified based on how the tiny home is used in relation to a primary residence — often serving as secondary dwellings for relatives or guests on the same property. They’re typically built in backyards and can be either movable or permanently installed, depending on local regulations. Some regions may have different rules for ADUs compared to primary-residence tiny homes.
Is Home Insurance Required for Tiny Homes?
Whether your tiny home requires insurance coverage depends on how it's classified. For example, if your tiny house is stationary and not regularly transported like an RV, and you're paying for it out of pocket, there are no federal or state laws requiring tiny home insurance. However, if your home is financed, your lender will likely require you to purchase insurance to get approved for the loan.[4]
If your tiny house will be moved frequently and is classified as an RV, then you’ll likely be required by law to carry RV insurance in most states. Similar to auto insurance, minimum coverage requirements must be met before you can legally drive it on public roads — even if it’s your primary residence.[5]
Why Does a Tiny Home Need Insurance?
While tiny homes differ from traditional houses or condos in terms of design and mobility, they still face risks that can be mitigated with the right insurance. For example, tiny homes are vulnerable to wind damage, vandalism and accidental kitchen fires – all of which can be covered by a tiny home insurance or comprehensive RV insurance policy, depending on how the home is classified.[6][7]
Types of Insurance for Tiny Homes
The type of tiny house coverage you need depends on whether your home is mobile or stationary.
Insurance for a Mobile Tiny Home
If your tiny home is regularly on the road, you’ll likely need to buy RV insurance. With an RV insurance policy, you can access several auto insurance coverages, such as:
- Bodily injury liability: Covers medical bills or emergency care costs from a collision for which you’re responsible
- Property damage liability: Covers property damage in a collision you cause
- Uninsured/underinsured motorist coverage: Covers medical expenses to you and your passengers along with property damage if the other at-fault driver doesn’t have sufficient or any insurance
- Collision coverage: Covers repair costs if another vehicle hits your tiny home
- Comprehensive protection: Protects your tiny home from non-collision losses, such as vandalism or a falling tree
- Personal property coverage: Protects your belongings inside your tiny house
Keep in mind that tiny homes intended to serve as permanent residences — even if they’re built on an RV chassis — likely won’t qualify as RVs for insurance purposes.[8] In those cases, you may need to purchase a tiny home insurance policy instead.
Insurance for a Permanently Installed Tiny Home
Manufactured home or mobile home insurance is recommended if your tiny home is stationary. A manufactured home or mobile home insurance policy covers most of the perils as a standard homeowners insurance policy, including:
- Dwelling: Covers the structure of your tiny home
- Additional structures: Covers fences, detached garages, sheds and other buildings on your property
- Personal property: Covers personal belongings inside your tiny home (for example, electronics, clothing and furniture)
- Liability: Pays for property damage or medical expenses you’re legally responsible for — for instance, if a guest trips and gets injured inside your home
- Loss of use: Pays for approved living expenses if your tiny home becomes temporarily uninhabitable after a covered peril (for example, while it’s being repaired after a fire)
Some insurers may deny insurance coverage if you intend to move your tiny home frequently. In that case, you may need to shop around for more flexible coverage or purchase RV insurance.
Insurance for a Tiny Home You Build Yourself
If you build your tiny house instead of purchasing it, you’ll still need to meet insurance requirements if a lender is financing the DIY project. However, securing insurance can be more challenging without construction experience. Tiny home insurers may hesitate to work with inexperienced builders because mistakes can lead to violations of local building or zoning regulations.
How Much Is Tiny Home Insurance?
The average cost of a tiny home insurance policy typically ranges from $600 to $1,000 per year.[9] Meanwhile, the average RV or motorhome insurance generally costs under $1,500 per year, but can range from $200 to $3,000 annually.[10]
Your tiny house insurance cost will depend on multiple factors, including:
- Square footage
- Number of household members
- Age of the structure
- Replacement cost value of the tiny home
- Value of personal belongings
- Whether the tiny home is movable or stationary
- Deductible amount
- How often the tiny home is transported
- Claims history
- Credit score
Which Insurance Carriers Offer Coverage for Tiny Homes?
Several insurance companies offer tiny home insurance coverage, including:
- Strategic Insurance Agency[11]
- Foremost Insurance Group (a Farmers Insurance subsidiary)[12]
- American Family Insurance[13]
- American Modern Insurance Group[14]
- State Farm[15]
- GEICO[16]
- Liberty Mutual[17]
Keep in mind that how your tiny home is classified may exclude certain options, and not all carriers operate in every state.
Which States Allow Tiny Homes?
There are currently no state laws that ban using tiny homes as primary residences. However, tiny homes are still subject to local housing and zoning regulations. For example, California has expanded support for tiny homes by allowing movable tiny homes to be classified as accessory dwelling units (ADUs), giving them legal status even when placed in backyards.[18]
Other states, such as New York, have more restrictions on movable tiny homes, typically prohibiting them from serving as permanent residences. New York also enforces minimum size requirements for building permits, which can make it difficult to construct a DIY tiny home that meets those standards.[18]
How Much Do Tiny Homes Cost?
Rocket Mortgage estimates that the average cost of a tiny home is about $45,000, though many factors can influence the final price.[19] Purchasing a tiny home typically costs between $29,000 and $250,000, depending on factors such as the materials used, utility installation and total square footage. Below is a quick breakdown of average tiny home costs by size:[1]
|
Tiny Home Size in Square Feet |
Average Total Cost |
Total Cost Range |
|---|---|---|
|
100 |
$29,000 |
$19,000 – $45,000 |
|
200 |
$58,000 |
$35,000 – $85,000 |
|
300 |
$87,000 |
$50,000 – $130,000 |
|
400 |
$112,000 |
$70,000 – $170,000 |
|
500 |
$172,000 |
$100,000 – $250,000 |
However, these costs are significantly lower than the average price of a standard home, which is about $400,000.[1] Building your tiny home yourself can lead to savings, but it’s a challenging project that requires understanding local zoning laws, securing materials and meeting construction standards. Mistakes in DIY builds may also disqualify you from getting approved for tiny home insurance.
How To Get Tiny Home Insurance
To get tiny home insurance, you’ll likely need to shop around based on the classification of your tiny home. Search for insurers that offer coverage for tiny homes or manufactured or mobile homes if it’s a permanent fixture, while RV insurance may be required for movable tiny homes.
Try to obtain quotes from three to five different insurance carriers — depending on how your tiny home is classified — which will help you understand your options for premium costs and deductibles. You’ll need to provide information about your tiny home to each insurer, including square footage, location, materials used and more. This process can become tedious, as you’ll typically need to get quotes from each insurer one at a time.
You can speed up this process by using an insurance marketplace like SmartFinancial. After answering a brief questionnaire, we can connect you with a licensed insurance agent to help you get the tiny home coverage you need. Click here for your free home insurance quotes today!
- Insurance quotes /
- Home /
- Tiny Home Insurance
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Home Insurance Quote Online Now.
More on Home Insurance

Looking for Home Insurance?
Compare rates from dozens of companies in less than 3 minutes.